
Bienvenidos

Text Styles

These are styles that can be added through the tools and style dropdown in the rich text editor (Content blocks, other areas with a rich text editor like the content blocks')


H2 Title

H3 Title

H4 Title

H5 Title
H6 Title

Paragraph Copy Lorem Ipsum

Color Text

Color2 Text

Color3 Text

Grey Text

Large Text

Larger Text

Small Text

Uppercase Text

Thin Text

Extra Bold Text

Color, Color2, Color 3, and Grey Text in a title

Lists

  1. List Item 1
  2. List Item 2
    • List item 1
    • List item 2
  3. List Item 3
  4. List item 4

Other

Callout Text Here

Quotation Cite

Line Rules

Separator


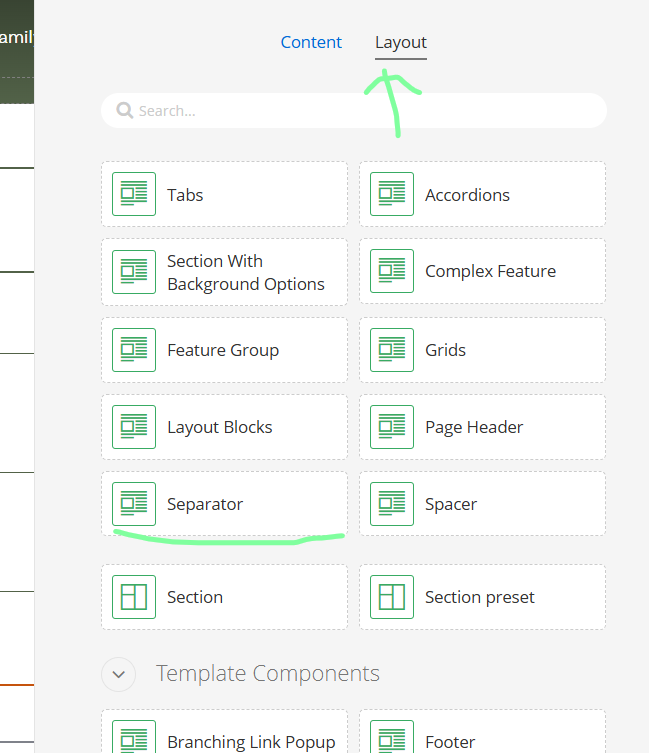
Further styles and more customized separators are available under the "separators" tool under "layout" 


Link Styles

The button variants should only be used when a single button is needed and it doesn't need to be shared anywhere. These can be added through the "Link Style" dropdown under "More Options" when creating a link in the rich text editor.

Basic Link

Link Style Button

Link Style Secondary Button

Link Style Accent Button

Emphasized Link

Buttons

There are four ways to create a button.

A button can be added through the link style dropdown in any link within a rich text editor or content block.

CTAs widget can provide buttons unique to a page.

Furthermore, buttons can be added to the buttons widget. Buttons added to the buttons widget are shared between all instances of the button. Shared buttons are recommended because if a link is changed later, then all buttons linking to the link be changed at once.

Call to Action (CTAs) Widget

CTAs are recommended when no more than two buttons are needed, and the buttons are unique to the page and aren't to be used anywhere else on the site.

The options available in the CTAs widget are also more limited than the options available through the shared buttons widget.

CTA Button Learn More about CTAs

Shared Buttons

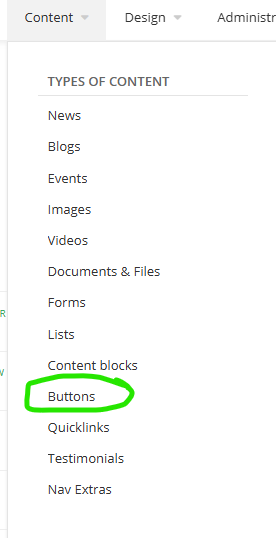
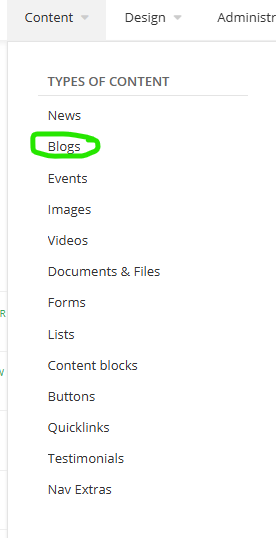
Buttons can be created under content.

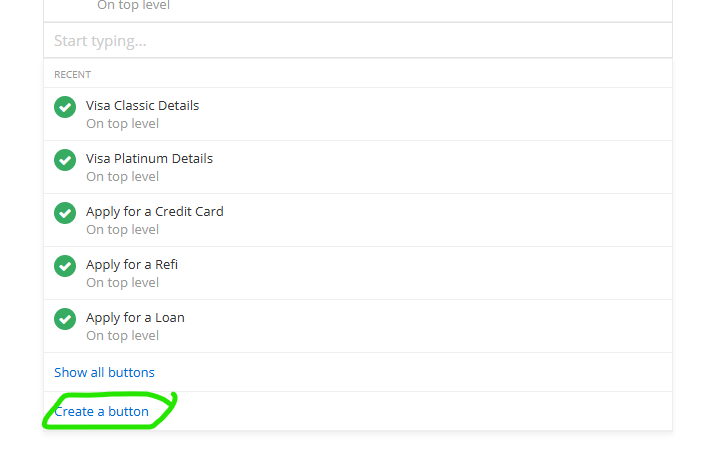
They can also be created when selecting buttons in the widget.

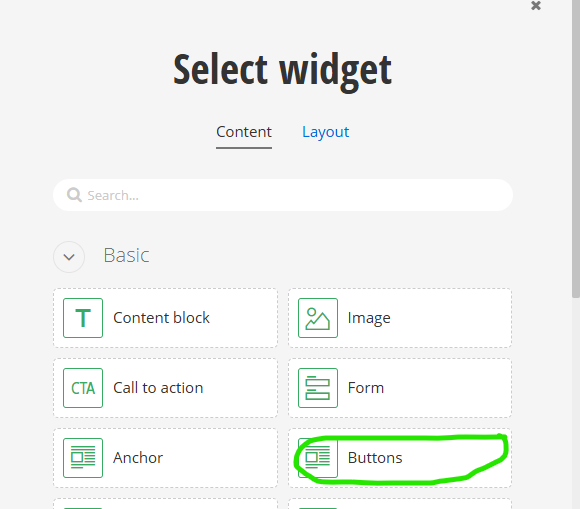
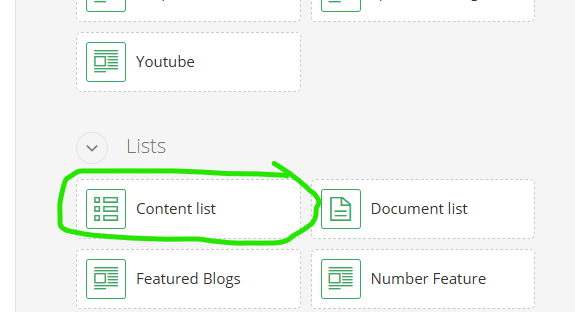
Buttons can be added to the page either through the dedicated, full-optioned button widget or through the content list widget.

Using the buttons widget to add buttons

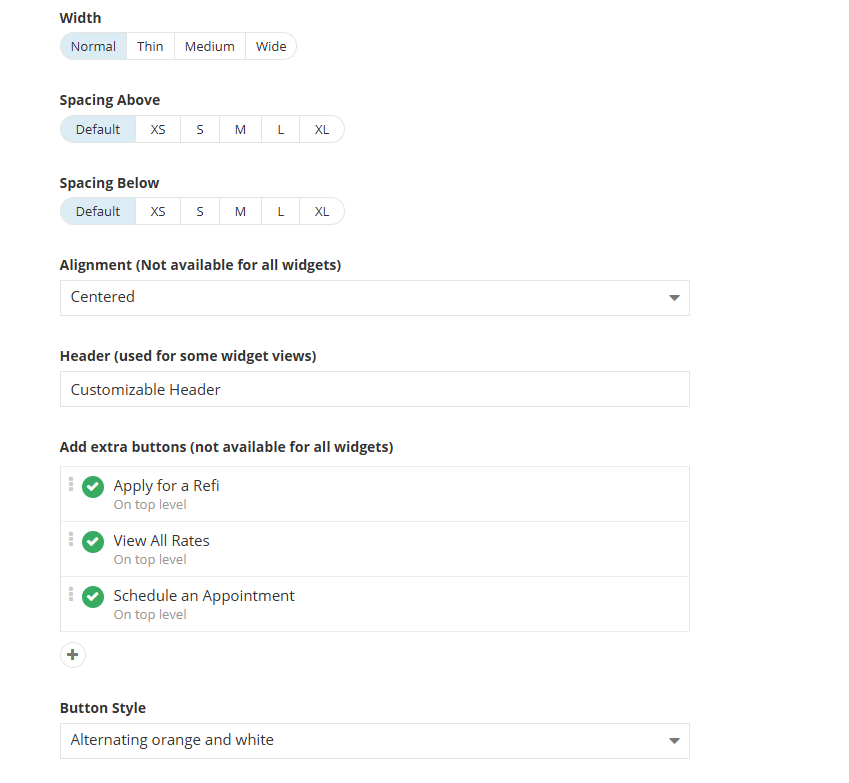
The buttons widget is specialized for buttons and contains all button options.

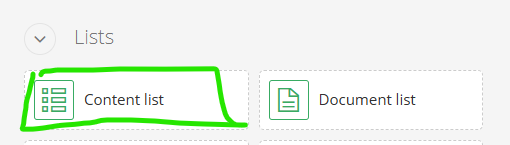
Using the content List widget to make buttons

Buttons can also be added through the site's standard content list widget.

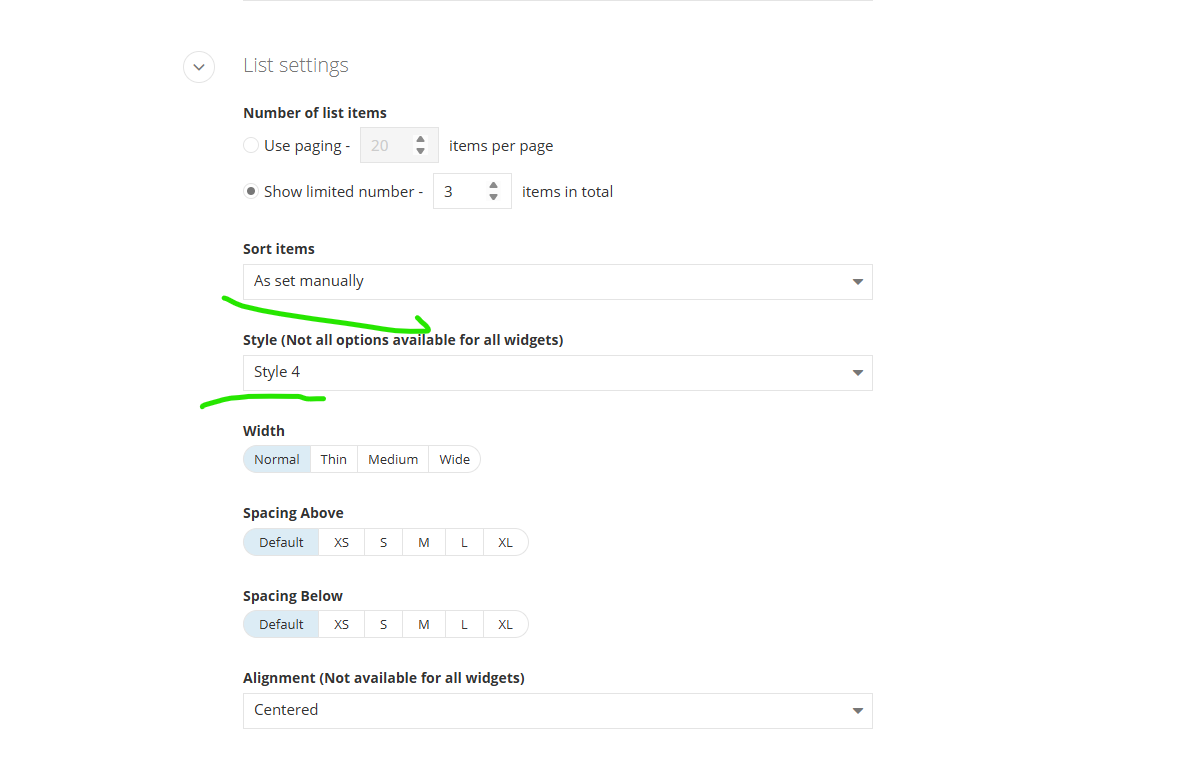
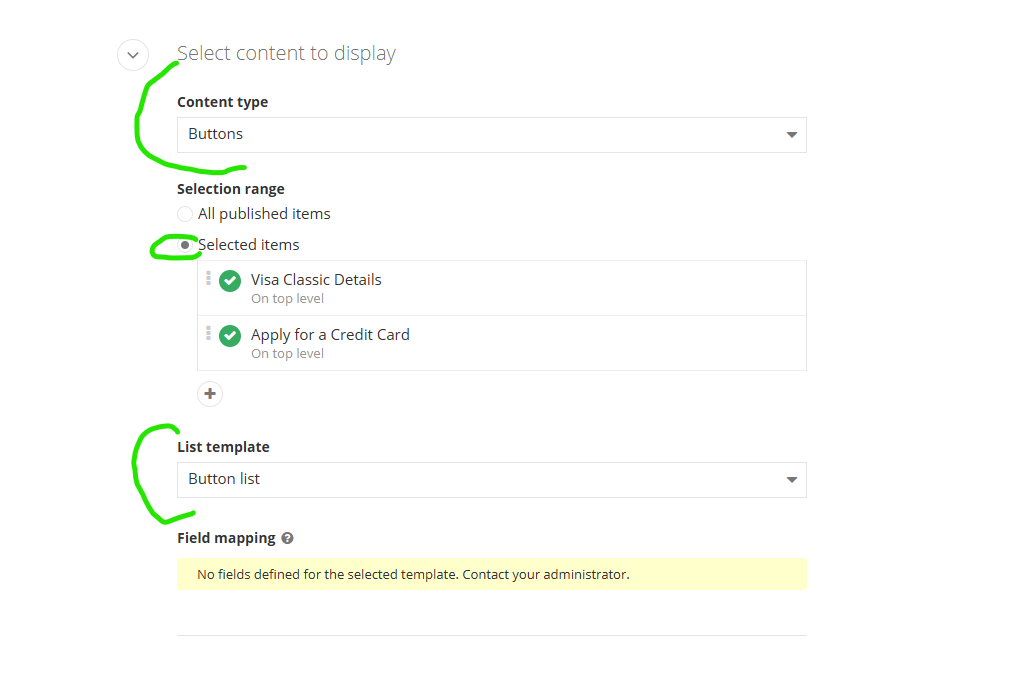
Once dropped, the list settings must be adjusted as follows: 

Only 5 styles are available in the content list widget.

Flip Badge Callout

A very simple way of making this callout.

By default, the front is the fibre logo, but it can be customized.

Just drop content here after adding the widget

  • It's simple
  • It's easy

Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor .

Splash Heading

These are the headings used on the home page. Although they are not used on the inside pages by default, support for them exists to allow future use in potential landing pages.

Pre-Heading

Splash Heading

Anchor

Anchor is used to easily add a location to the page that can be linked to by any link's "anchor" field. Note that each anchor's value can only be used once per page, or the linking will break.

Click to jump to the anchor below the paragraph

Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. 

Youtube

Allows easy embedding of a youtube video. Simply copy this part of the end of the youtube video's url (after ?v= and before any other &) 

and paste it into the video id field in the widget's edit panel. 

The Content List

A number of different types of content can be selected through this widget.

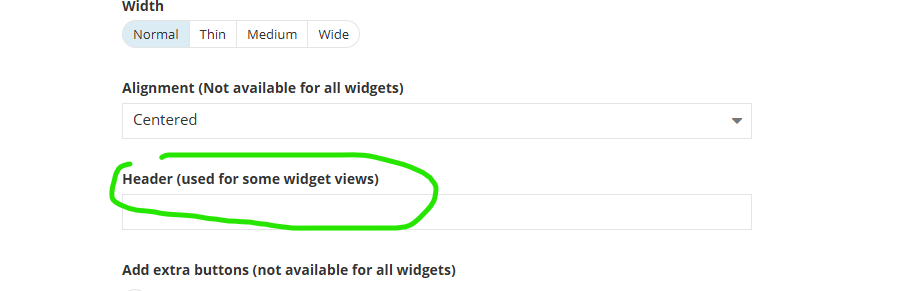
Depending on the widget, various other options may be available under list settings. Order By, Spacing, and Width are available for all widgets. Buttons are available for quicklinks, lists, and some testimonial templates and styles. Header is available for quicklinks, lists, blog lists, and some testimonial templates. Alignment is only relevant for buttons (for now).

Only blog and news take advantage of the items  under detail view settings.

Blogs

Blog posts can be added under content - > Blogs, then clicking into the blog the post should be added to.

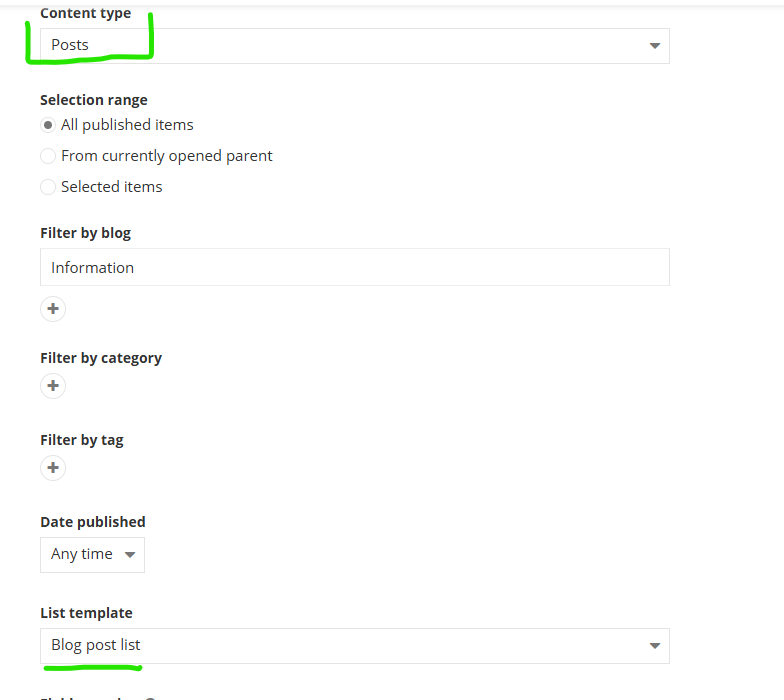
To add the posts to the page, "Posts" should be set as the Content type, and "Blog post list" should be set as the template.

To display all blog posts, all published items can be set to show without modification. However, the posts can be set to draw only posts from a specific blog and/or category, which allows more nuanced selection of content. For example, featured posts on the auto loans page can be set to draw only posts from the Information blog and the Auto Loans category. This allows for a much easier maintenance of the post system across multiple pages, because the post lists can then automatically update with the latest information as new posts are added, without each post list needing the posts selected manually every time.

Style 1 shows all posts.

Not all home loans are the same, and mortgage terms can vary significantly. That's why understanding how home loans work is so important. Knowing how different loan terms and types of mortgages affect your budget can help you choose the right home loan for your needs. Let's take a look at how different loan terms work, what they mean for your monthly payment, and how they affect your total borrowing costs.

UNDERSTANDING MORTGAGE TERMS

When you take out a mortgage, the loan term is the maximum amount of time you have to repay the money you borrowed, plus interest. For example, a 30-year mortgage gives you 30 years to pay off your home loan. However, you can always make extra payments or pay off your mortgage early to save on interest. 

If your financial goals change, refinancing may allow you to switch to a shorter or longer loan term. Refinancing replaces your mortgage with a new mortgage that may have a different interest rate and monthly payment. Closing costs apply when you refinance, so be sure to consider whether the benefits outweigh the costs.  

How long are home loans? In the U.S., the most common home loan term is 30 years. At Fibre Federal, we offer mortgages with terms of 10, 15, 20, and 30 years. The right term for you depends on your budget, long-term plans, and how quickly you want to build equity. 

The chart below compares the advantages and trade-offs of common mortgage terms:

Mortgage Term

Monthly Payment

Total Interest Paid

Equity Growth

10 Years

Highest

Lowest

Fastest

15 Years

Higher

Lower

Faster

20 Years

Moderate

Moderate

Moderate

30 Years

Lowest

Highest

Slowest

The shortest mortgage term lenders offer is 10 years, while the longest is 40 years. While 30-year mortgages are the most popular option, terms longer than 30 years aren't common. A 40-year loan may give you a lower monthly payment, but it usually has stricter qualification requirements and a higher interest rate, meaning you'll pay significantly more interest over time.

HOW MORTGAGE AMORTIZATION WORKS

Mortgage amortization is the process that determines how much of your monthly payment goes toward the principal and interest over the life of the loan. When you start making payments on your loan, a larger portion goes toward interest. As you continue paying down the loan, more of your payment goes toward the principal.

Amortization affects how quickly you can build equity. Because more of your payments go toward interest in the beginning, your equity grows slowly at first. Later, as more of your payments go toward the principal, you build equity more quickly. Making extra payments can increase your home equity, reduce the amount of interest you pay, and potentially help you pay off your loan sooner.

The chart below shows how principal and interest are allocated:

Loan Stage

Payment Allocation

Equity Growth

Early Years

More interest, less principal

Slower

Middle Years

More balanced

Moderate

Later Years

More principal, less interest

Faster

HOW MORTGAGE TERMS AFFECT INTEREST RATES

When comparing mortgage terms, it's important to look at the annual percentage rate (APR) rather than just the interest rate. The APR includes the interest rate, loan fees, and mortgage points, giving you a more complete picture of your borrowing costs. 

The length of the mortgage term can have a significant impact on your APR. Short-term fixed-rate loans of 10 or 15 years usually have lower APRs because they're considered less risky and are repaid more quickly. On the other hand, longer loan terms of 20 or 30 years typically have higher APRs because the longer repayment period extends the loan and increases the lender's risk. 

Here are the key differences between shorter and longer mortgage terms:

Short-term mortgages (10 to 15 years)

  • Typically have lower APRs

  • Have higher monthly payments

  • Cost less in total interest 

Long-term mortgages (20 to 30 years)

  • Typically have higher APRs

  • Have lower monthly payments

  • Cost more in total interest 

With adjustable-rate mortgages (ARMs), your interest rate can increase or decrease over time based on market conditions. With fixed-rate mortgages, your rate is locked in and won't change over the life of the loan. Other factors can also affect your interest rate, including your credit score, loan-to-value (LTV) ratio, down payment amount, and current market conditions.

HOW MORTGAGE TERMS AFFECT MONTHLY PAYMENTS & BORROWING COSTS

The loan term you choose doesn't just affect your APR; it also affects your monthly payment. A longer loan term of 30 years allows you to spread out your payments over more time, giving you lower monthly payments. This can make your mortgage easier to fit into your budget, and it may even give you the flexibility to afford a higher-priced home.

If you finance a home with a shorter term, you'll pay off your loan balance sooner. Although a shorter term typically gives you a higher monthly payment, it often comes with a lower APR and allows you to build equity in your home more quickly.

A longer loan term can lower your monthly payment, but it can significantly increase your borrowing costs. The longer your repayment period, the more total interest you'll pay.

The chart below compares the monthly payment and total interest paid for a $400,000 fixed-rate conventional mortgage at 6% interest for 15- and 30-year terms.

Mortgage Term

Monthly Payment

Total Interest Paid

15 Years

$3,375.43

$207,576.92

30 Years

$2,398.20 

$463,352.76 

A 30-year mortgage can cost more than twice as much in total interest as a 15-year mortgage. That's why it's important to choose the shortest loan term that you can comfortably afford. 

WHEN TO CHOOSE A SHORT-TERM MORTGAGE

A short-term home loan can help you save money and build equity faster, but it’s not the right choice for every borrower. A 15- or 20-year mortgage may be a good fit if:

You Can Afford a Higher Monthly Mortgage Payment 

Although a shorter loan term will increase your monthly payment, it could help you save tens of thousands of dollars in interest over the life of your mortgage, depending on your loan balance. It can help you become mortgage-free sooner and free up money for other goals, like planning for retirement.

You Want to Build Equity Faster  

With a 15-year mortgage, a larger portion of your payment goes toward the principal each month. This allows you to build home equity more quickly than you would with a longer loan term. Having more equity can give you additional borrowing options in the future, like a home equity loan or HELOC, which can be used for home improvements, debt consolidation, or other major expenses. 

You Don’t Plan to Stay in Your Home Long

If you expect to sell your home within a few years, a shorter mortgage term may help you pay down your loan balance more quickly. This could leave you with more equity when you sell, potentially increasing the amount you can put toward your next home.

WHEN TO CHOOSE A LONG-TERM MORTGAGE

A long-term mortgage of 20 to 30 years helps you spread your loan payments over a longer period. A longer loan term may make sense when:

You Want a Lower Monthly Mortgage Payment

A 30-year loan provides more time to pay off your home, which lowers your monthly payment. This can give you more breathing room in your budget to cover daily expenses, build an emergency fund, contribute to retirement savings, or work toward other financial goals. Lower monthly payments may also make it easier to qualify for a home that fits your needs.

You Want the Flexibility to Make Extra Payments

Choosing a longer-term mortgage doesn't mean you have to pay it off slowly. You can make additional payments toward the principal whenever your budget allows. This gives you the benefit of lower monthly payments while allowing you to pay off your mortgage ahead of schedule if your financial situation changes.

You Want to Buy the Most House You Can Afford

A longer loan term may increase the amount you qualify to borrow by lowering your monthly mortgage payment. This can give you more flexibility when choosing a home and help you find one that truly fits your needs. It may allow you to purchase a larger home or choose a property in a preferred neighborhood.

Frequently Asked Questions

Can you change your mortgage term?

Yes. You can change your mortgage term later by refinancing your home loan. Keep in mind, however, that refinancing may change your interest rate and involve closing costs, so it's important to compare your options before making a decision.

What's the difference between a fixed-rate and adjustable-rate mortgage?

With a fixed-rate mortgage, the interest rate stays the same throughout the life of the loan, and your principal and interest payments won't change. An adjustable-rate mortgage (ARM) offers a fixed interest rate that may be lower than fixed-rate mortgages for an introductory period. After that, the rate can increase or decrease over time based on market conditions.

What is the average mortgage term?

The most common mortgage term is 30 years. However, many lenders also offer mortgages with terms of 10, 15, and 20 years.

Should I get a 15- or 30-year mortgage?

It depends on your budget and financial goals. A 15-year mortgage can help you pay off your home sooner, build equity faster, and save money on interest, but it comes with higher monthly payments. A 30-year mortgage offers lower monthly payments, but you'll typically pay more interest over the life of the loan. 

Can you pay off a mortgage early?

It depends on the mortgage lender. With Fibre Federal, there are no early prepayment penalties. Paying off your mortgage early could help you save money on interest, depending on your remaining balance.

CHOOSE THE MORTGAGE THAT’S RIGHT FOR YOU

Choosing the right mortgage term is one of the most important financial decisions you'll make when buying a home. That's why comparing different loan terms and considering how long you plan to stay in your home is essential. The mortgage you choose will affect your monthly payment, total borrowing costs, and how quickly you build equity. 

Ready to take the next step? Explore our low-rate mortgage loans and find the term that works best for your needs and budget.
See Our Low-Rate Mortgage Loans

Style 2 shows the latest 4 posts. 

Not all home loans are the same, and mortgage terms can vary significantly. That's why understanding how home loans work is so important. Knowing how different loan terms and types of mortgages affect your budget can help you choose the right home loan for your needs. Let's take a look at how different loan terms work, what they mean for your monthly payment, and how they affect your total borrowing costs.

UNDERSTANDING MORTGAGE TERMS

When you take out a mortgage, the loan term is the maximum amount of time you have to repay the money you borrowed, plus interest. For example, a 30-year mortgage gives you 30 years to pay off your home loan. However, you can always make extra payments or pay off your mortgage early to save on interest. 

If your financial goals change, refinancing may allow you to switch to a shorter or longer loan term. Refinancing replaces your mortgage with a new mortgage that may have a different interest rate and monthly payment. Closing costs apply when you refinance, so be sure to consider whether the benefits outweigh the costs.  

How long are home loans? In the U.S., the most common home loan term is 30 years. At Fibre Federal, we offer mortgages with terms of 10, 15, 20, and 30 years. The right term for you depends on your budget, long-term plans, and how quickly you want to build equity. 

The chart below compares the advantages and trade-offs of common mortgage terms:

Mortgage Term

Monthly Payment

Total Interest Paid

Equity Growth

10 Years

Highest

Lowest

Fastest

15 Years

Higher

Lower

Faster

20 Years

Moderate

Moderate

Moderate

30 Years

Lowest

Highest

Slowest

The shortest mortgage term lenders offer is 10 years, while the longest is 40 years. While 30-year mortgages are the most popular option, terms longer than 30 years aren't common. A 40-year loan may give you a lower monthly payment, but it usually has stricter qualification requirements and a higher interest rate, meaning you'll pay significantly more interest over time.

HOW MORTGAGE AMORTIZATION WORKS

Mortgage amortization is the process that determines how much of your monthly payment goes toward the principal and interest over the life of the loan. When you start making payments on your loan, a larger portion goes toward interest. As you continue paying down the loan, more of your payment goes toward the principal.

Amortization affects how quickly you can build equity. Because more of your payments go toward interest in the beginning, your equity grows slowly at first. Later, as more of your payments go toward the principal, you build equity more quickly. Making extra payments can increase your home equity, reduce the amount of interest you pay, and potentially help you pay off your loan sooner.

The chart below shows how principal and interest are allocated:

Loan Stage

Payment Allocation

Equity Growth

Early Years

More interest, less principal

Slower

Middle Years

More balanced

Moderate

Later Years

More principal, less interest

Faster

HOW MORTGAGE TERMS AFFECT INTEREST RATES

When comparing mortgage terms, it's important to look at the annual percentage rate (APR) rather than just the interest rate. The APR includes the interest rate, loan fees, and mortgage points, giving you a more complete picture of your borrowing costs. 

The length of the mortgage term can have a significant impact on your APR. Short-term fixed-rate loans of 10 or 15 years usually have lower APRs because they're considered less risky and are repaid more quickly. On the other hand, longer loan terms of 20 or 30 years typically have higher APRs because the longer repayment period extends the loan and increases the lender's risk. 

Here are the key differences between shorter and longer mortgage terms:

Short-term mortgages (10 to 15 years)

  • Typically have lower APRs

  • Have higher monthly payments

  • Cost less in total interest 

Long-term mortgages (20 to 30 years)

  • Typically have higher APRs

  • Have lower monthly payments

  • Cost more in total interest 

With adjustable-rate mortgages (ARMs), your interest rate can increase or decrease over time based on market conditions. With fixed-rate mortgages, your rate is locked in and won't change over the life of the loan. Other factors can also affect your interest rate, including your credit score, loan-to-value (LTV) ratio, down payment amount, and current market conditions.

HOW MORTGAGE TERMS AFFECT MONTHLY PAYMENTS & BORROWING COSTS

The loan term you choose doesn't just affect your APR; it also affects your monthly payment. A longer loan term of 30 years allows you to spread out your payments over more time, giving you lower monthly payments. This can make your mortgage easier to fit into your budget, and it may even give you the flexibility to afford a higher-priced home.

If you finance a home with a shorter term, you'll pay off your loan balance sooner. Although a shorter term typically gives you a higher monthly payment, it often comes with a lower APR and allows you to build equity in your home more quickly.

A longer loan term can lower your monthly payment, but it can significantly increase your borrowing costs. The longer your repayment period, the more total interest you'll pay.

The chart below compares the monthly payment and total interest paid for a $400,000 fixed-rate conventional mortgage at 6% interest for 15- and 30-year terms.

Mortgage Term

Monthly Payment

Total Interest Paid

15 Years

$3,375.43

$207,576.92

30 Years

$2,398.20 

$463,352.76 

A 30-year mortgage can cost more than twice as much in total interest as a 15-year mortgage. That's why it's important to choose the shortest loan term that you can comfortably afford. 

WHEN TO CHOOSE A SHORT-TERM MORTGAGE

A short-term home loan can help you save money and build equity faster, but it’s not the right choice for every borrower. A 15- or 20-year mortgage may be a good fit if:

You Can Afford a Higher Monthly Mortgage Payment 

Although a shorter loan term will increase your monthly payment, it could help you save tens of thousands of dollars in interest over the life of your mortgage, depending on your loan balance. It can help you become mortgage-free sooner and free up money for other goals, like planning for retirement.

You Want to Build Equity Faster  

With a 15-year mortgage, a larger portion of your payment goes toward the principal each month. This allows you to build home equity more quickly than you would with a longer loan term. Having more equity can give you additional borrowing options in the future, like a home equity loan or HELOC, which can be used for home improvements, debt consolidation, or other major expenses. 

You Don’t Plan to Stay in Your Home Long

If you expect to sell your home within a few years, a shorter mortgage term may help you pay down your loan balance more quickly. This could leave you with more equity when you sell, potentially increasing the amount you can put toward your next home.

WHEN TO CHOOSE A LONG-TERM MORTGAGE

A long-term mortgage of 20 to 30 years helps you spread your loan payments over a longer period. A longer loan term may make sense when:

You Want a Lower Monthly Mortgage Payment

A 30-year loan provides more time to pay off your home, which lowers your monthly payment. This can give you more breathing room in your budget to cover daily expenses, build an emergency fund, contribute to retirement savings, or work toward other financial goals. Lower monthly payments may also make it easier to qualify for a home that fits your needs.

You Want the Flexibility to Make Extra Payments

Choosing a longer-term mortgage doesn't mean you have to pay it off slowly. You can make additional payments toward the principal whenever your budget allows. This gives you the benefit of lower monthly payments while allowing you to pay off your mortgage ahead of schedule if your financial situation changes.

You Want to Buy the Most House You Can Afford

A longer loan term may increase the amount you qualify to borrow by lowering your monthly mortgage payment. This can give you more flexibility when choosing a home and help you find one that truly fits your needs. It may allow you to purchase a larger home or choose a property in a preferred neighborhood.

Frequently Asked Questions

Can you change your mortgage term?

Yes. You can change your mortgage term later by refinancing your home loan. Keep in mind, however, that refinancing may change your interest rate and involve closing costs, so it's important to compare your options before making a decision.

What's the difference between a fixed-rate and adjustable-rate mortgage?

With a fixed-rate mortgage, the interest rate stays the same throughout the life of the loan, and your principal and interest payments won't change. An adjustable-rate mortgage (ARM) offers a fixed interest rate that may be lower than fixed-rate mortgages for an introductory period. After that, the rate can increase or decrease over time based on market conditions.

What is the average mortgage term?

The most common mortgage term is 30 years. However, many lenders also offer mortgages with terms of 10, 15, and 20 years.

Should I get a 15- or 30-year mortgage?

It depends on your budget and financial goals. A 15-year mortgage can help you pay off your home sooner, build equity faster, and save money on interest, but it comes with higher monthly payments. A 30-year mortgage offers lower monthly payments, but you'll typically pay more interest over the life of the loan. 

Can you pay off a mortgage early?

It depends on the mortgage lender. With Fibre Federal, there are no early prepayment penalties. Paying off your mortgage early could help you save money on interest, depending on your remaining balance.

CHOOSE THE MORTGAGE THAT’S RIGHT FOR YOU

Choosing the right mortgage term is one of the most important financial decisions you'll make when buying a home. That's why comparing different loan terms and considering how long you plan to stay in your home is essential. The mortgage you choose will affect your monthly payment, total borrowing costs, and how quickly you build equity. 

Ready to take the next step? Explore our low-rate mortgage loans and find the term that works best for your needs and budget.
See Our Low-Rate Mortgage Loans

Style 3 is a slider of posts.

Please do not use this one inside of a tab, unless the tab is the first tab (being hidden on page load can cause issues with the slider's initial calculations.)

Not all home loans are the same, and mortgage terms can vary significantly. That's why understanding how home loans work is so important. Knowing how different loan terms and types of mortgages affect your budget can help you choose the right home loan for your needs. Let's take a look at how different loan terms work, what they mean for your monthly payment, and how they affect your total borrowing costs.

UNDERSTANDING MORTGAGE TERMS

When you take out a mortgage, the loan term is the maximum amount of time you have to repay the money you borrowed, plus interest. For example, a 30-year mortgage gives you 30 years to pay off your home loan. However, you can always make extra payments or pay off your mortgage early to save on interest. 

If your financial goals change, refinancing may allow you to switch to a shorter or longer loan term. Refinancing replaces your mortgage with a new mortgage that may have a different interest rate and monthly payment. Closing costs apply when you refinance, so be sure to consider whether the benefits outweigh the costs.  

How long are home loans? In the U.S., the most common home loan term is 30 years. At Fibre Federal, we offer mortgages with terms of 10, 15, 20, and 30 years. The right term for you depends on your budget, long-term plans, and how quickly you want to build equity. 

The chart below compares the advantages and trade-offs of common mortgage terms:

Mortgage Term

Monthly Payment

Total Interest Paid

Equity Growth

10 Years

Highest

Lowest

Fastest

15 Years

Higher

Lower

Faster

20 Years

Moderate

Moderate

Moderate

30 Years

Lowest

Highest

Slowest

The shortest mortgage term lenders offer is 10 years, while the longest is 40 years. While 30-year mortgages are the most popular option, terms longer than 30 years aren't common. A 40-year loan may give you a lower monthly payment, but it usually has stricter qualification requirements and a higher interest rate, meaning you'll pay significantly more interest over time.

HOW MORTGAGE AMORTIZATION WORKS

Mortgage amortization is the process that determines how much of your monthly payment goes toward the principal and interest over the life of the loan. When you start making payments on your loan, a larger portion goes toward interest. As you continue paying down the loan, more of your payment goes toward the principal.

Amortization affects how quickly you can build equity. Because more of your payments go toward interest in the beginning, your equity grows slowly at first. Later, as more of your payments go toward the principal, you build equity more quickly. Making extra payments can increase your home equity, reduce the amount of interest you pay, and potentially help you pay off your loan sooner.

The chart below shows how principal and interest are allocated:

Loan Stage

Payment Allocation

Equity Growth

Early Years

More interest, less principal

Slower

Middle Years

More balanced

Moderate

Later Years

More principal, less interest

Faster

HOW MORTGAGE TERMS AFFECT INTEREST RATES

When comparing mortgage terms, it's important to look at the annual percentage rate (APR) rather than just the interest rate. The APR includes the interest rate, loan fees, and mortgage points, giving you a more complete picture of your borrowing costs. 

The length of the mortgage term can have a significant impact on your APR. Short-term fixed-rate loans of 10 or 15 years usually have lower APRs because they're considered less risky and are repaid more quickly. On the other hand, longer loan terms of 20 or 30 years typically have higher APRs because the longer repayment period extends the loan and increases the lender's risk. 

Here are the key differences between shorter and longer mortgage terms:

Short-term mortgages (10 to 15 years)

  • Typically have lower APRs

  • Have higher monthly payments

  • Cost less in total interest 

Long-term mortgages (20 to 30 years)

  • Typically have higher APRs

  • Have lower monthly payments

  • Cost more in total interest 

With adjustable-rate mortgages (ARMs), your interest rate can increase or decrease over time based on market conditions. With fixed-rate mortgages, your rate is locked in and won't change over the life of the loan. Other factors can also affect your interest rate, including your credit score, loan-to-value (LTV) ratio, down payment amount, and current market conditions.

HOW MORTGAGE TERMS AFFECT MONTHLY PAYMENTS & BORROWING COSTS

The loan term you choose doesn't just affect your APR; it also affects your monthly payment. A longer loan term of 30 years allows you to spread out your payments over more time, giving you lower monthly payments. This can make your mortgage easier to fit into your budget, and it may even give you the flexibility to afford a higher-priced home.

If you finance a home with a shorter term, you'll pay off your loan balance sooner. Although a shorter term typically gives you a higher monthly payment, it often comes with a lower APR and allows you to build equity in your home more quickly.

A longer loan term can lower your monthly payment, but it can significantly increase your borrowing costs. The longer your repayment period, the more total interest you'll pay.

The chart below compares the monthly payment and total interest paid for a $400,000 fixed-rate conventional mortgage at 6% interest for 15- and 30-year terms.

Mortgage Term

Monthly Payment

Total Interest Paid

15 Years

$3,375.43

$207,576.92

30 Years

$2,398.20 

$463,352.76 

A 30-year mortgage can cost more than twice as much in total interest as a 15-year mortgage. That's why it's important to choose the shortest loan term that you can comfortably afford. 

WHEN TO CHOOSE A SHORT-TERM MORTGAGE

A short-term home loan can help you save money and build equity faster, but it’s not the right choice for every borrower. A 15- or 20-year mortgage may be a good fit if:

You Can Afford a Higher Monthly Mortgage Payment 

Although a shorter loan term will increase your monthly payment, it could help you save tens of thousands of dollars in interest over the life of your mortgage, depending on your loan balance. It can help you become mortgage-free sooner and free up money for other goals, like planning for retirement.

You Want to Build Equity Faster  

With a 15-year mortgage, a larger portion of your payment goes toward the principal each month. This allows you to build home equity more quickly than you would with a longer loan term. Having more equity can give you additional borrowing options in the future, like a home equity loan or HELOC, which can be used for home improvements, debt consolidation, or other major expenses. 

You Don’t Plan to Stay in Your Home Long

If you expect to sell your home within a few years, a shorter mortgage term may help you pay down your loan balance more quickly. This could leave you with more equity when you sell, potentially increasing the amount you can put toward your next home.

WHEN TO CHOOSE A LONG-TERM MORTGAGE

A long-term mortgage of 20 to 30 years helps you spread your loan payments over a longer period. A longer loan term may make sense when:

You Want a Lower Monthly Mortgage Payment

A 30-year loan provides more time to pay off your home, which lowers your monthly payment. This can give you more breathing room in your budget to cover daily expenses, build an emergency fund, contribute to retirement savings, or work toward other financial goals. Lower monthly payments may also make it easier to qualify for a home that fits your needs.

You Want the Flexibility to Make Extra Payments

Choosing a longer-term mortgage doesn't mean you have to pay it off slowly. You can make additional payments toward the principal whenever your budget allows. This gives you the benefit of lower monthly payments while allowing you to pay off your mortgage ahead of schedule if your financial situation changes.

You Want to Buy the Most House You Can Afford

A longer loan term may increase the amount you qualify to borrow by lowering your monthly mortgage payment. This can give you more flexibility when choosing a home and help you find one that truly fits your needs. It may allow you to purchase a larger home or choose a property in a preferred neighborhood.

Frequently Asked Questions

Can you change your mortgage term?

Yes. You can change your mortgage term later by refinancing your home loan. Keep in mind, however, that refinancing may change your interest rate and involve closing costs, so it's important to compare your options before making a decision.

What's the difference between a fixed-rate and adjustable-rate mortgage?

With a fixed-rate mortgage, the interest rate stays the same throughout the life of the loan, and your principal and interest payments won't change. An adjustable-rate mortgage (ARM) offers a fixed interest rate that may be lower than fixed-rate mortgages for an introductory period. After that, the rate can increase or decrease over time based on market conditions.

What is the average mortgage term?

The most common mortgage term is 30 years. However, many lenders also offer mortgages with terms of 10, 15, and 20 years.

Should I get a 15- or 30-year mortgage?

It depends on your budget and financial goals. A 15-year mortgage can help you pay off your home sooner, build equity faster, and save money on interest, but it comes with higher monthly payments. A 30-year mortgage offers lower monthly payments, but you'll typically pay more interest over the life of the loan. 

Can you pay off a mortgage early?

It depends on the mortgage lender. With Fibre Federal, there are no early prepayment penalties. Paying off your mortgage early could help you save money on interest, depending on your remaining balance.

CHOOSE THE MORTGAGE THAT’S RIGHT FOR YOU

Choosing the right mortgage term is one of the most important financial decisions you'll make when buying a home. That's why comparing different loan terms and considering how long you plan to stay in your home is essential. The mortgage you choose will affect your monthly payment, total borrowing costs, and how quickly you build equity. 

Ready to take the next step? Explore our low-rate mortgage loans and find the term that works best for your needs and budget.
See Our Low-Rate Mortgage Loans

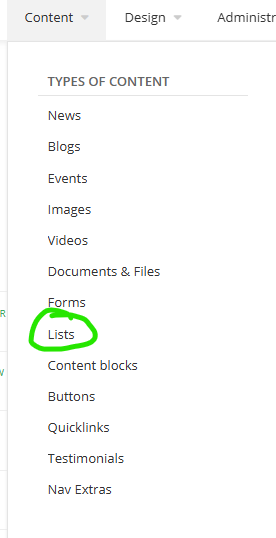
List Items

The list content type is an easy and convenient way to create and sort lists of simple FAQs and similar content. List Items display like layout accordions. 

Lists can be created under Content - > Lists.

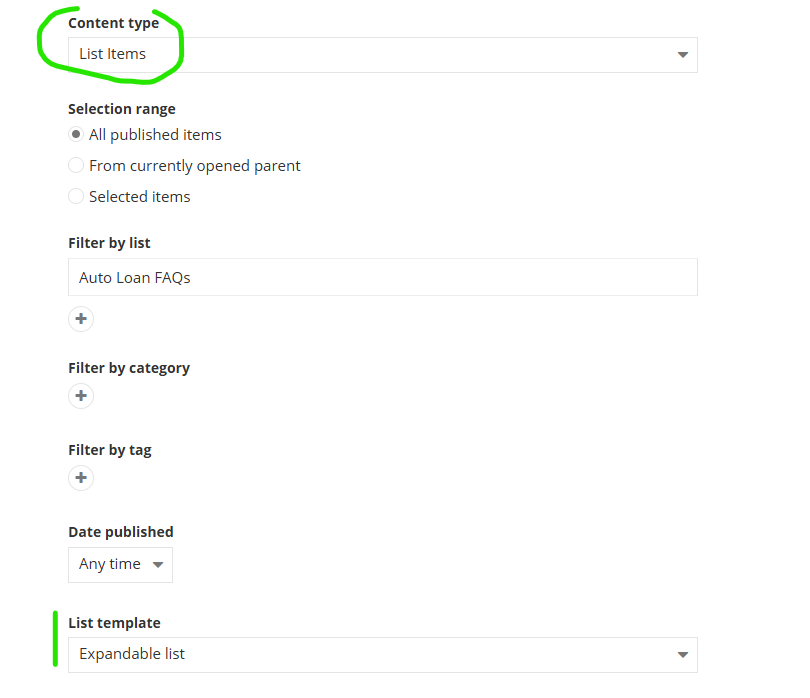
To show list items, select Content type : Lists. It can then be filtered by parent list. List items can also be manually selected if needed. 

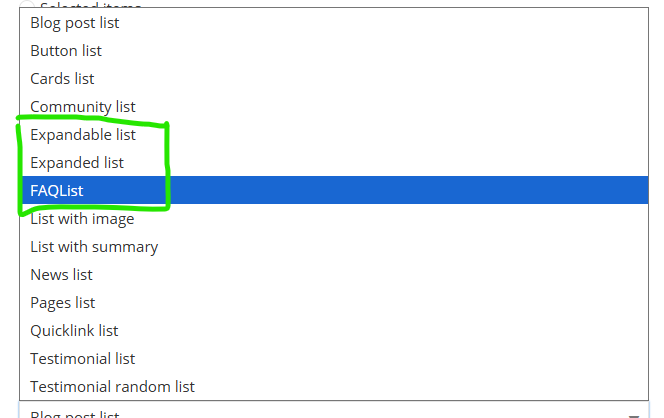
Set the template to either Expandable List, Expanded List, or FAQ list. FAQ list comes pre-programmed with SEO relevant to FAQs. 

For all list templates, Style 1 is basic, Style 2 adds an expand all button, and Style 3 is a double column. With the FAQ list template, a title is automatically added at the top, which can be customized through the Title field in the widget's edit panel if needed. The other list templates only create the title if it is explicitly provided in this field.

Can I finance with Fibre Federal & TLC at the dealership?

Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.

Can I get help with starting my auto loan application?

Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.

Can you help me find a new car?

Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.

What benefits can I expect from a Fibre Federal & TLC auto loan?

We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.

What is the Drive4Less loan?

Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.

Frequently Asked Questions

Can I finance with Fibre Federal & TLC at the dealership?

Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.

Can I get help with starting my auto loan application?

Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.

Can you help me find a new car?

Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.

What benefits can I expect from a Fibre Federal & TLC auto loan?

We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.

What is the Drive4Less loan?

Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.

How to set up help-page-styled FAQs

Drop a grid. set the template to Responsive Grid and the style to "Style 3". Set the width to "Medium". Add the class "help-grid". The width setting is optional, the others are important. Technically, for a 3-wide help grid, Style 1 and "wide" width could be used.

Drop FAQs. Select three. Set the Style to Style 4. 

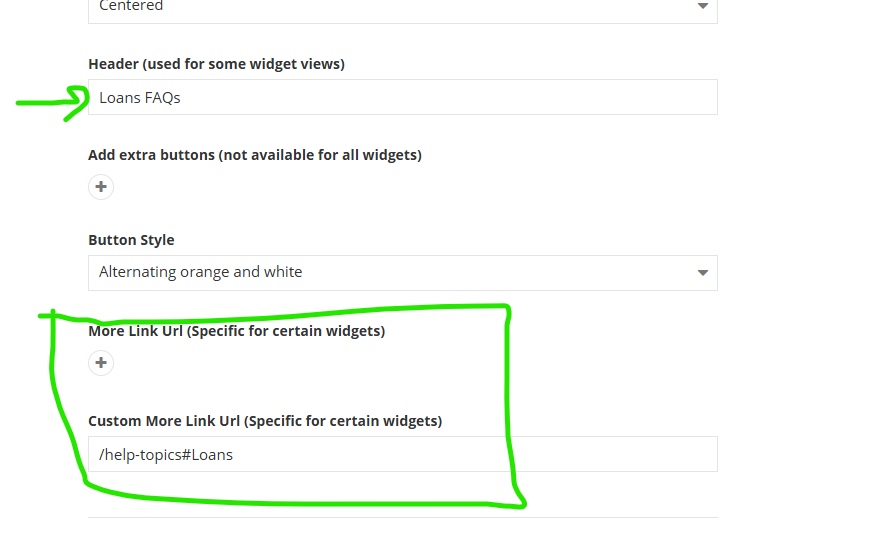
Each FAQ group's title and link are added through the Header and the two More Link fields under "List Settings". The first link allows selection of pages, the second is for pasting an url -- useful when linking to an anchor. If available, a page link will always take precedence over the custom link, so if using a custom link, ensure that More Link Url doesn't have a page selected.

Loans FAQs

How do I prevent fraud on my account?

Being proactive about fraud and scam situations is essential! You can find helpful tips and tricks for stopping fraud before it happens on our Fraud Prevention page.

What can I do if I am a fraud victim?

If you’ve provided sensitive account information to a scammer, contact us right away to help secure your accounts. If you believe you’ve become a victim of identity theft, refer to the Federal Trade Commission’s information about Identity Theft: What To Know – What To Do.
See All

Auto Loan FAQs

See All

To use similar styling and link structure for normal full-width  FAQs, the grid can simply be left out. 

Auto Loan FAQs

See All

Quicklinks

Despite the name, quicklinks should be considered as  "quicklinks and features" because it also can be used to add icon-title-summary sets to pages. These can have a link but do not need to. They can be displayed either through the "Quicklinks group" widget (discussed later) or the Content List widget.

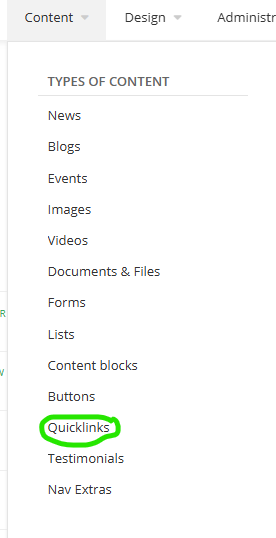
Quicklinks can be created either under Content -> Quicklinks

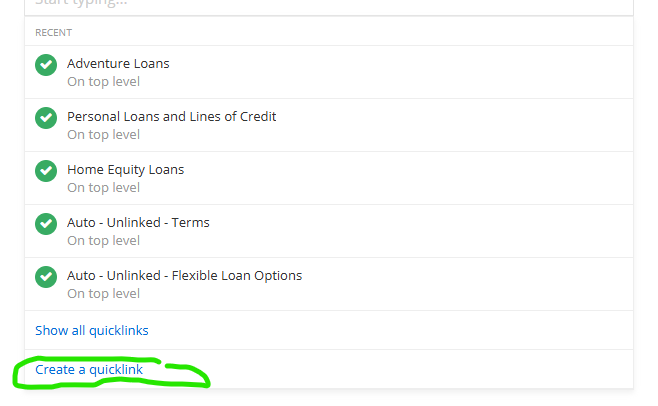
Or when selecting quicklinks to add to the list

Quicklinks can be displayed through the Content List widget by setting the Content type to "Quicklinks" and the list to "Quicklink List" 


Further styles can be added to the Content List for Quicklinks if needed--for now, only one exists.

Testimonials

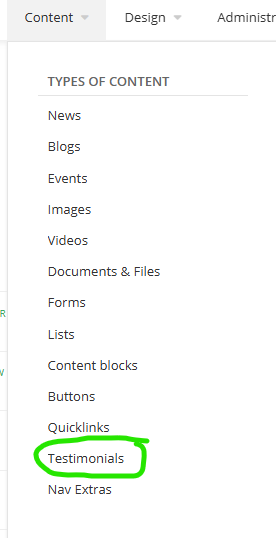
Testimonials can be created under Content -> Testimonials

Or when selecting testimonials in the content list widget.

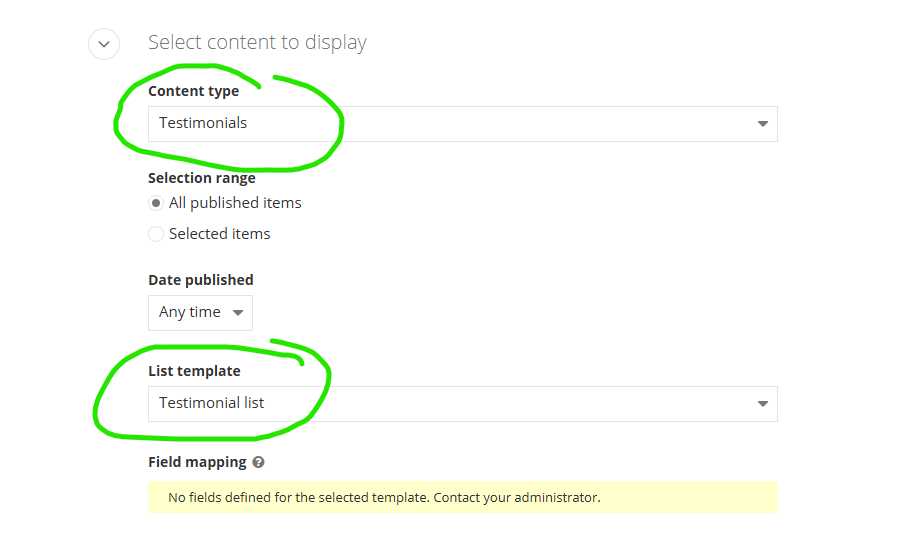
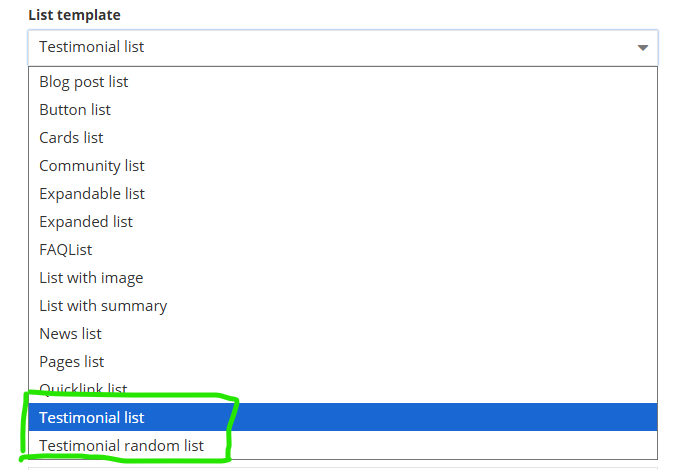
They can be shown using the content list widget with the Content type set to Testimonials and the template set to Testimonial List or Testimonial Random List. 

Testimonials have two templates: "Testimonial List" and "Testimonial Random List".


Testimonial list shows all selected testimonials, either as a list or slider. 

Style 1 is a basic list. Style 2 is a simple slider. Style 3 is the same slider, but with additional styling and a title/button area. 

My friends, family and I do all of our banking at Fibre Federal because they consistently provide such good service. Their employees and branches are so professional, and the staff is so helpful that I don't want to go to any other bank.
Maddie W., Longview, WA
It was reported to me by a life insurance company that they had a data breach and my banking information was stolen. The thief tried to charge my card, but Fibre saw the charge as suspicious and declined the charge. Thank you, Fibre Federal Credit Union, for having my back. I have a tight budget and losing any amount of my money could be devastating to me and my family.
Cherilynn
I am very satisfied with my experience, especially due to the fact it was my first time using the text feature. The agent I talked to was very professional, answered all of my questions, operated in timely fashion, and left me with a good first impression. I will be using this again because of her.
Brad O.
I used the chat feature in the Fibre Federal Credit Union app to resolve a problem with funds in one of our accounts and I couldn’t be happier with the experience. I work in a loud environment where phone calls aren’t always the best option for contacting people, so having the ability to chat with someone is a great option I think all banking institutions should implement.
Trevor N.
I would like to start off by saying that I really appreciate all the ways available to communicate with tellers: they have an online chat, call, video call, and online assistant to help with basic things. Whenever I interact with the tellers, they are kind and intelligent. I have always been able to fix the issues I come across with this credit union!
Tabatha B.
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Carolena Q.
I love being a part of the Fibre Family! Everyone is always so kind and helpful and I really appreciate the drive up ITM with virtual help!
Melissa T.
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.
Shantelle
The loan department at Fibre CU was extremely helpful with our needs and were quick to communicate and help solve any concerns we had. Would recommend Fibre CU and their helpful staff!
Rolly B.
Great customer service! I accidentally made a loan payment 2x and instead of telling me, ‘Sorry, Charlie,' as I expected, they reversed it right away no questions asked! Never had a bad experience with them. Great job all.
Danielle
The first loan I got was for a pickup, then I had an RV, and now I have a boat loan. Each loan was simple and went through so good that I’ve come back to deal with Kim every time. That was the quality that made me decide to switch to Fibre Federal.
Kelly
They’ve never wanted to push me into any kind of direction as far as loans. We sit down, they tell you the truth [and] the right path to go.
Mark
We have both personal and business accounts with Fibre, and have only good things to say! The staff is extremely helpful and friendly, especially in the business aspect of things. We couldn't ask for a better credit union!
Bryce B.
Fibre FCU has been a shining light for our business. We are always met with professionalism and know they care about us and the business we have brought to the Longview community. Thank you, thank you FibreFCU. We look forward to another great year.
Martha S.
I have been with them for both personal and business accounts. I find their checking to be great (online is easy to use) and their Choice Checking account pays some of the best rates on my balance. Visa account has some of the lowest interest rates available.
David L.
Very helpful and informative. All my questions were answered to the fullest and everything was made crystal clear in reference to opening my accounts.
Jordan M.
Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.
They are always friendly, fast, and always helpful with anything you need. I come here for all my banking needs and always leave feeling appreciated. This place is absolutely amazing.
Lisa W.
Best financial institution I have ever used! Super friendly, helpful staff members who give excellent service and are very knowledgeable about their products and services. I love how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
Fibre Federal have been my backbone in every time of need. They have been my credit union now for nearly 10 years and I would not have it any other way! Thank you to Fibre Federal for always being amazing and going above and beyond for your members even if we aren't on top of the game ourselves!
Holly
I would like to start off by saying that I really appreciate all the ways available to communicate with tellers: they have an online chat, call, video call, and online assistant to help with basic things. Whenever I interact with the tellers, they are kind and intelligent. I have always been able to fix the issues I come across with this credit union!
Tabatha B.
We have both personal and business accounts with Fibre, and have only good things to say! The staff is extremely helpful and friendly, especially in the business aspect of things. We couldn't ask for a better credit union!
Bryce B.
Best financial institution I have ever used! Super friendly, helpful staff members who give excellent service and are very knowledgeable about their products and services. I love how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Carolena Q.
The first loan I got was for a pickup, then I had an RV, and now I have a boat loan. Each loan was simple and went through so good that I’ve come back to deal with Kim every time. That was the quality that made me decide to switch to Fibre Federal.
Kelly
Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.
Fibre FCU has been a shining light for our business. We are always met with professionalism and know they care about us and the business we have brought to the Longview community. Thank you, thank you FibreFCU. We look forward to another great year.
Martha S.
I love being a part of the Fibre Family! Everyone is always so kind and helpful and I really appreciate the drive up ITM with virtual help!
Melissa T.
Fibre Federal have been my backbone in every time of need. They have been my credit union now for nearly 10 years and I would not have it any other way! Thank you to Fibre Federal for always being amazing and going above and beyond for your members even if we aren't on top of the game ourselves!
Holly
My friends, family and I do all of our banking at Fibre Federal because they consistently provide such good service. Their employees and branches are so professional, and the staff is so helpful that I don't want to go to any other bank.
Maddie W., Longview, WA
I am very satisfied with my experience, especially due to the fact it was my first time using the text feature. The agent I talked to was very professional, answered all of my questions, operated in timely fashion, and left me with a good first impression. I will be using this again because of her.
Brad O.
They are always friendly, fast, and always helpful with anything you need. I come here for all my banking needs and always leave feeling appreciated. This place is absolutely amazing.
Lisa W.
The loan department at Fibre CU was extremely helpful with our needs and were quick to communicate and help solve any concerns we had. Would recommend Fibre CU and their helpful staff!
Rolly B.
They’ve never wanted to push me into any kind of direction as far as loans. We sit down, they tell you the truth [and] the right path to go.
Mark
Very helpful and informative. All my questions were answered to the fullest and everything was made crystal clear in reference to opening my accounts.
Jordan M.
I have been with them for both personal and business accounts. I find their checking to be great (online is easy to use) and their Choice Checking account pays some of the best rates on my balance. Visa account has some of the lowest interest rates available.
David L.
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.
Shantelle
I used the chat feature in the Fibre Federal Credit Union app to resolve a problem with funds in one of our accounts and I couldn’t be happier with the experience. I work in a loud environment where phone calls aren’t always the best option for contacting people, so having the ability to chat with someone is a great option I think all banking institutions should implement.
Trevor N.
It was reported to me by a life insurance company that they had a data breach and my banking information was stolen. The thief tried to charge my card, but Fibre saw the charge as suspicious and declined the charge. Thank you, Fibre Federal Credit Union, for having my back. I have a tight budget and losing any amount of my money could be devastating to me and my family.
Cherilynn
Great customer service! I accidentally made a loan payment 2x and instead of telling me, ‘Sorry, Charlie,' as I expected, they reversed it right away no questions asked! Never had a bad experience with them. Great job all.
Danielle

Customizable buttons Customizable Title

Great Service deserves to be celebrated. Tell us about the experience that made a difference for you!
It was reported to me by a life insurance company that they had a data breach and my banking information was stolen. The thief tried to charge my card, but Fibre saw the charge as suspicious and declined the charge. Thank you, Fibre Federal Credit Union, for having my back. I have a tight budget and losing any amount of my money could be devastating to me and my family.
Cherilynn
My friends, family and I do all of our banking at Fibre Federal because they consistently provide such good service. Their employees and branches are so professional, and the staff is so helpful that I don't want to go to any other bank.
Maddie W., Longview, WA
I am very satisfied with my experience, especially due to the fact it was my first time using the text feature. The agent I talked to was very professional, answered all of my questions, operated in timely fashion, and left me with a good first impression. I will be using this again because of her.
Brad O.
They’ve never wanted to push me into any kind of direction as far as loans. We sit down, they tell you the truth [and] the right path to go.
Mark
I love being a part of the Fibre Family! Everyone is always so kind and helpful and I really appreciate the drive up ITM with virtual help!
Melissa T.
They are always friendly, fast, and always helpful with anything you need. I come here for all my banking needs and always leave feeling appreciated. This place is absolutely amazing.
Lisa W.
Best financial institution I have ever used! Super friendly, helpful staff members who give excellent service and are very knowledgeable about their products and services. I love how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
The first loan I got was for a pickup, then I had an RV, and now I have a boat loan. Each loan was simple and went through so good that I’ve come back to deal with Kim every time. That was the quality that made me decide to switch to Fibre Federal.
Kelly
I have been with them for both personal and business accounts. I find their checking to be great (online is easy to use) and their Choice Checking account pays some of the best rates on my balance. Visa account has some of the lowest interest rates available.
David L.
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.
Shantelle
The loan department at Fibre CU was extremely helpful with our needs and were quick to communicate and help solve any concerns we had. Would recommend Fibre CU and their helpful staff!
Rolly B.
We have both personal and business accounts with Fibre, and have only good things to say! The staff is extremely helpful and friendly, especially in the business aspect of things. We couldn't ask for a better credit union!
Bryce B.
Fibre Federal have been my backbone in every time of need. They have been my credit union now for nearly 10 years and I would not have it any other way! Thank you to Fibre Federal for always being amazing and going above and beyond for your members even if we aren't on top of the game ourselves!
Holly
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Carolena Q.
I would like to start off by saying that I really appreciate all the ways available to communicate with tellers: they have an online chat, call, video call, and online assistant to help with basic things. Whenever I interact with the tellers, they are kind and intelligent. I have always been able to fix the issues I come across with this credit union!
Tabatha B.
Very helpful and informative. All my questions were answered to the fullest and everything was made crystal clear in reference to opening my accounts.
Jordan M.
Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.
I used the chat feature in the Fibre Federal Credit Union app to resolve a problem with funds in one of our accounts and I couldn’t be happier with the experience. I work in a loud environment where phone calls aren’t always the best option for contacting people, so having the ability to chat with someone is a great option I think all banking institutions should implement.
Trevor N.
Fibre FCU has been a shining light for our business. We are always met with professionalism and know they care about us and the business we have brought to the Longview community. Thank you, thank you FibreFCU. We look forward to another great year.
Martha S.
Great customer service! I accidentally made a loan payment 2x and instead of telling me, ‘Sorry, Charlie,' as I expected, they reversed it right away no questions asked! Never had a bad experience with them. Great job all.
Danielle

Testimonial Random list shows a random single testimonial from those selected. 

Style 1 is a designed element. Style 2 is a simple presentation that can be dropped inside any section. 

The title is customizable too.

Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.

Real Words, Real People from the PNW

Best financial institution I have ever used! Super friendly, helpful staff members who give excellent service and are very knowledgeable about their products and services. I love how easy it is to talk to a person or get assistance when needed.
Geoffrey P.

Documents List

Provide a simple list of documents.

docx
test (docx)

Featured Blogs

Show the latest post from each selected blog. 

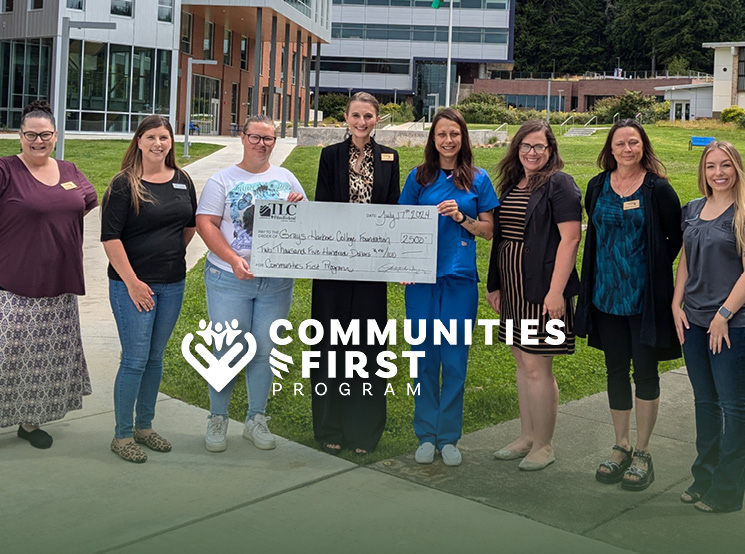
Community Communities First Program Founded in 2018, our Communities First Program supports education and healthcare related services. To date, we've donated $284,500 to seven community college foundations and 13 hospital foundations in our service areas. Read More
Financial Wellness Blog How Business Equipment Loans Can Help Your Company Grow Growing a business is always a tough balancing act between driving revenue and paying the bills. The right business equipment loan can help you get off the ground or reach the next level by making it easier to acquire the critical machinery or technology your company needs. Read More

Number Feature

Is a widget implemented to showcase numbers. Currently, the only style is the one shown on the homepage. It was set up as a widget so that the numbers can be easily changed at any time. It can be extended with more styles if needed for landing pages or promotionals (Contact your LKCS sales rep.) 

$1,000 Featured dollars.
500 This is a test number.

Quicklinks Group

This was set up to allow a group of quicklinks with a title and image to be showcased. The title of the main template defaults to "Other Members Also Liked" but can be customized. It can also be used to generate a list of features with the same special styling if quicklinks without links are selected.

It can be extended with more templates as needed.

Steps

Another widget with specialized styling. More templates can be added if needed.

  1. 1 Step 1 Step 1 Description

  2. 2 Careful! Do not make these too long.

Comparison Feature

Scroll all the way down to the special section to find this widget.

Compare

Product 1

Use the Comparison Feature to compare items Yes Click on More Details to access ability to add product rows
Row titles are optional Use Small for normal content
On mobile Basic is large
Row titles are used to label No No creates the X
Each column. Yes Yes creates the check
Schedule an Appointment

Product 2

Use the Comparison Feature to compare items Yes Types can be mixed between products if needed
Row titles are optional Yes
On mobile No
Row titles are used to label Yes
Each column. If an uneven number are provided, the widget will automatically generate rows to compensate. 
Apply for a Credit Card

Additional Widgets 

These were created later and do not have a full guide.

August 30, 2013

Received NCUA's Low-Income Designation (LDI), which extends the credit union's resources, funding, and flexibility to better serve people with limited incomes.
View the enlarged NCUA image

August 8, 2025

Designated a Juntos Avanzamos credit union, recognizing our commitment to empowering Hispanic and immigrant communities and supporting financial well-being for all.
View the enlarged Juntos Avanzamos image

August 24, 2022

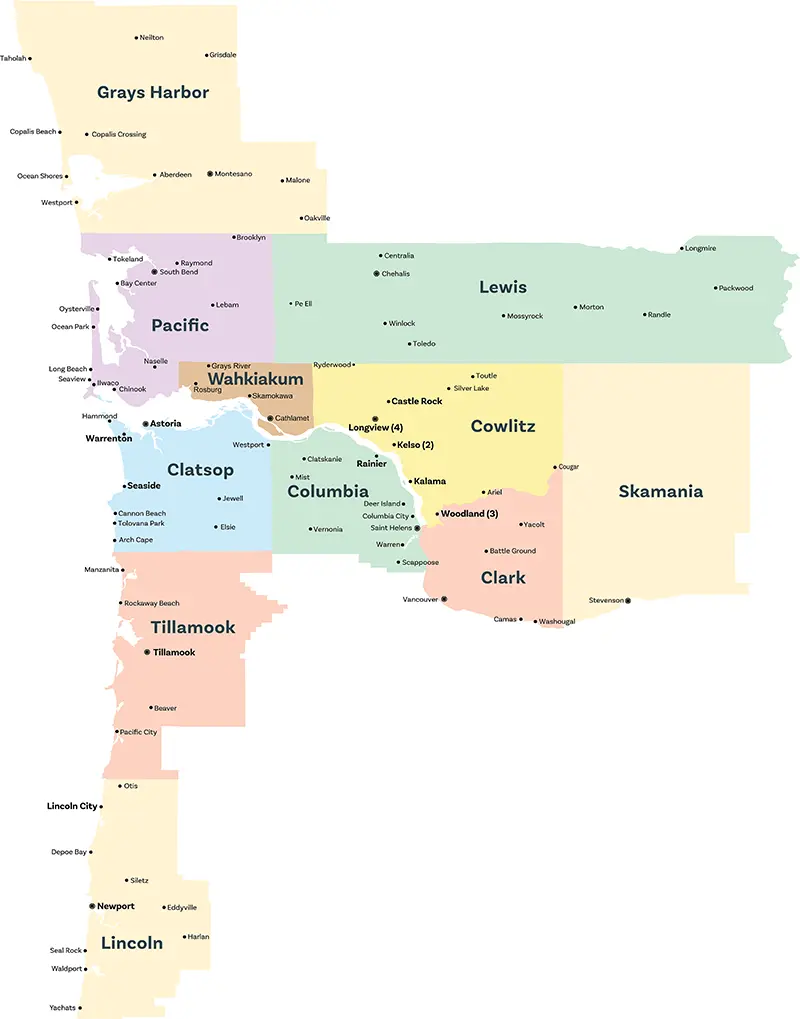
Field of Membership expansion into Clark, Grays Harbor, Lewis, and Skamania Counties in Washington.

May 1, 2015

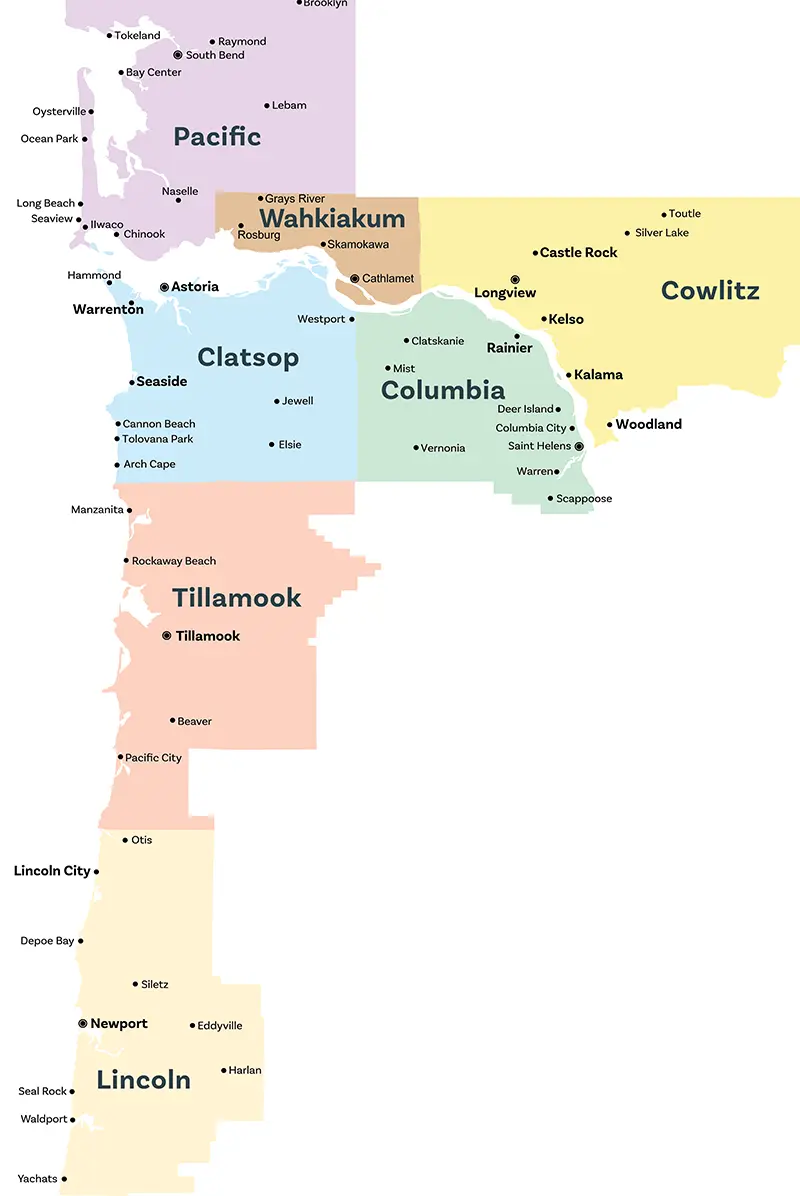
Acquired TLC Federal Credit Union, expanding the branch network and Field of Membership into Tillamook and Lincoln Counties, along the Oregon Coast.

June 13, 2013

Field of Membership expansion into Pacific County in Washington.

September 24, 2012

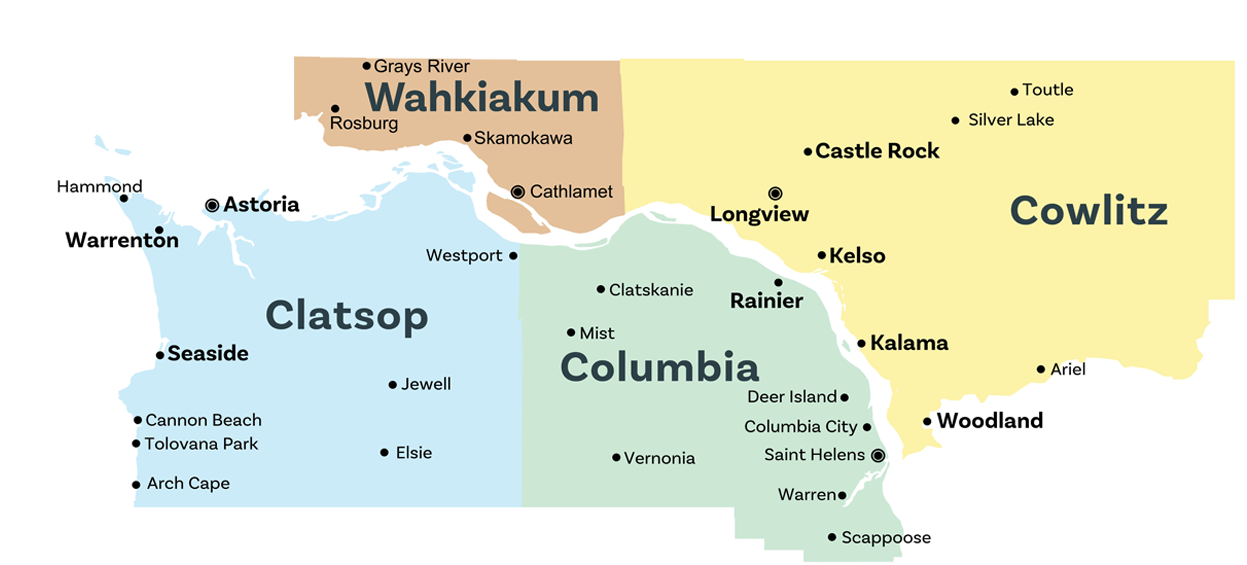
Field of Membership expansion into Columbia and Clatsop Counties in Oregon, and Wahkiakum County in Washington.
View the enlarged map image

January 1, 2008

Merged with 1st Citizens Federal Credit Union in Longview, WA.

January 1, 1982

Merged with International Paper Company (IPCO) Federal Credit Union in Longview, WA.

September 1975

Fibre Federal changed to a community charter, allowing non-Fibre mill workers and their families in Cowlitz County to become members.

1971

Main Office branch opened (and is still in use to this day!).
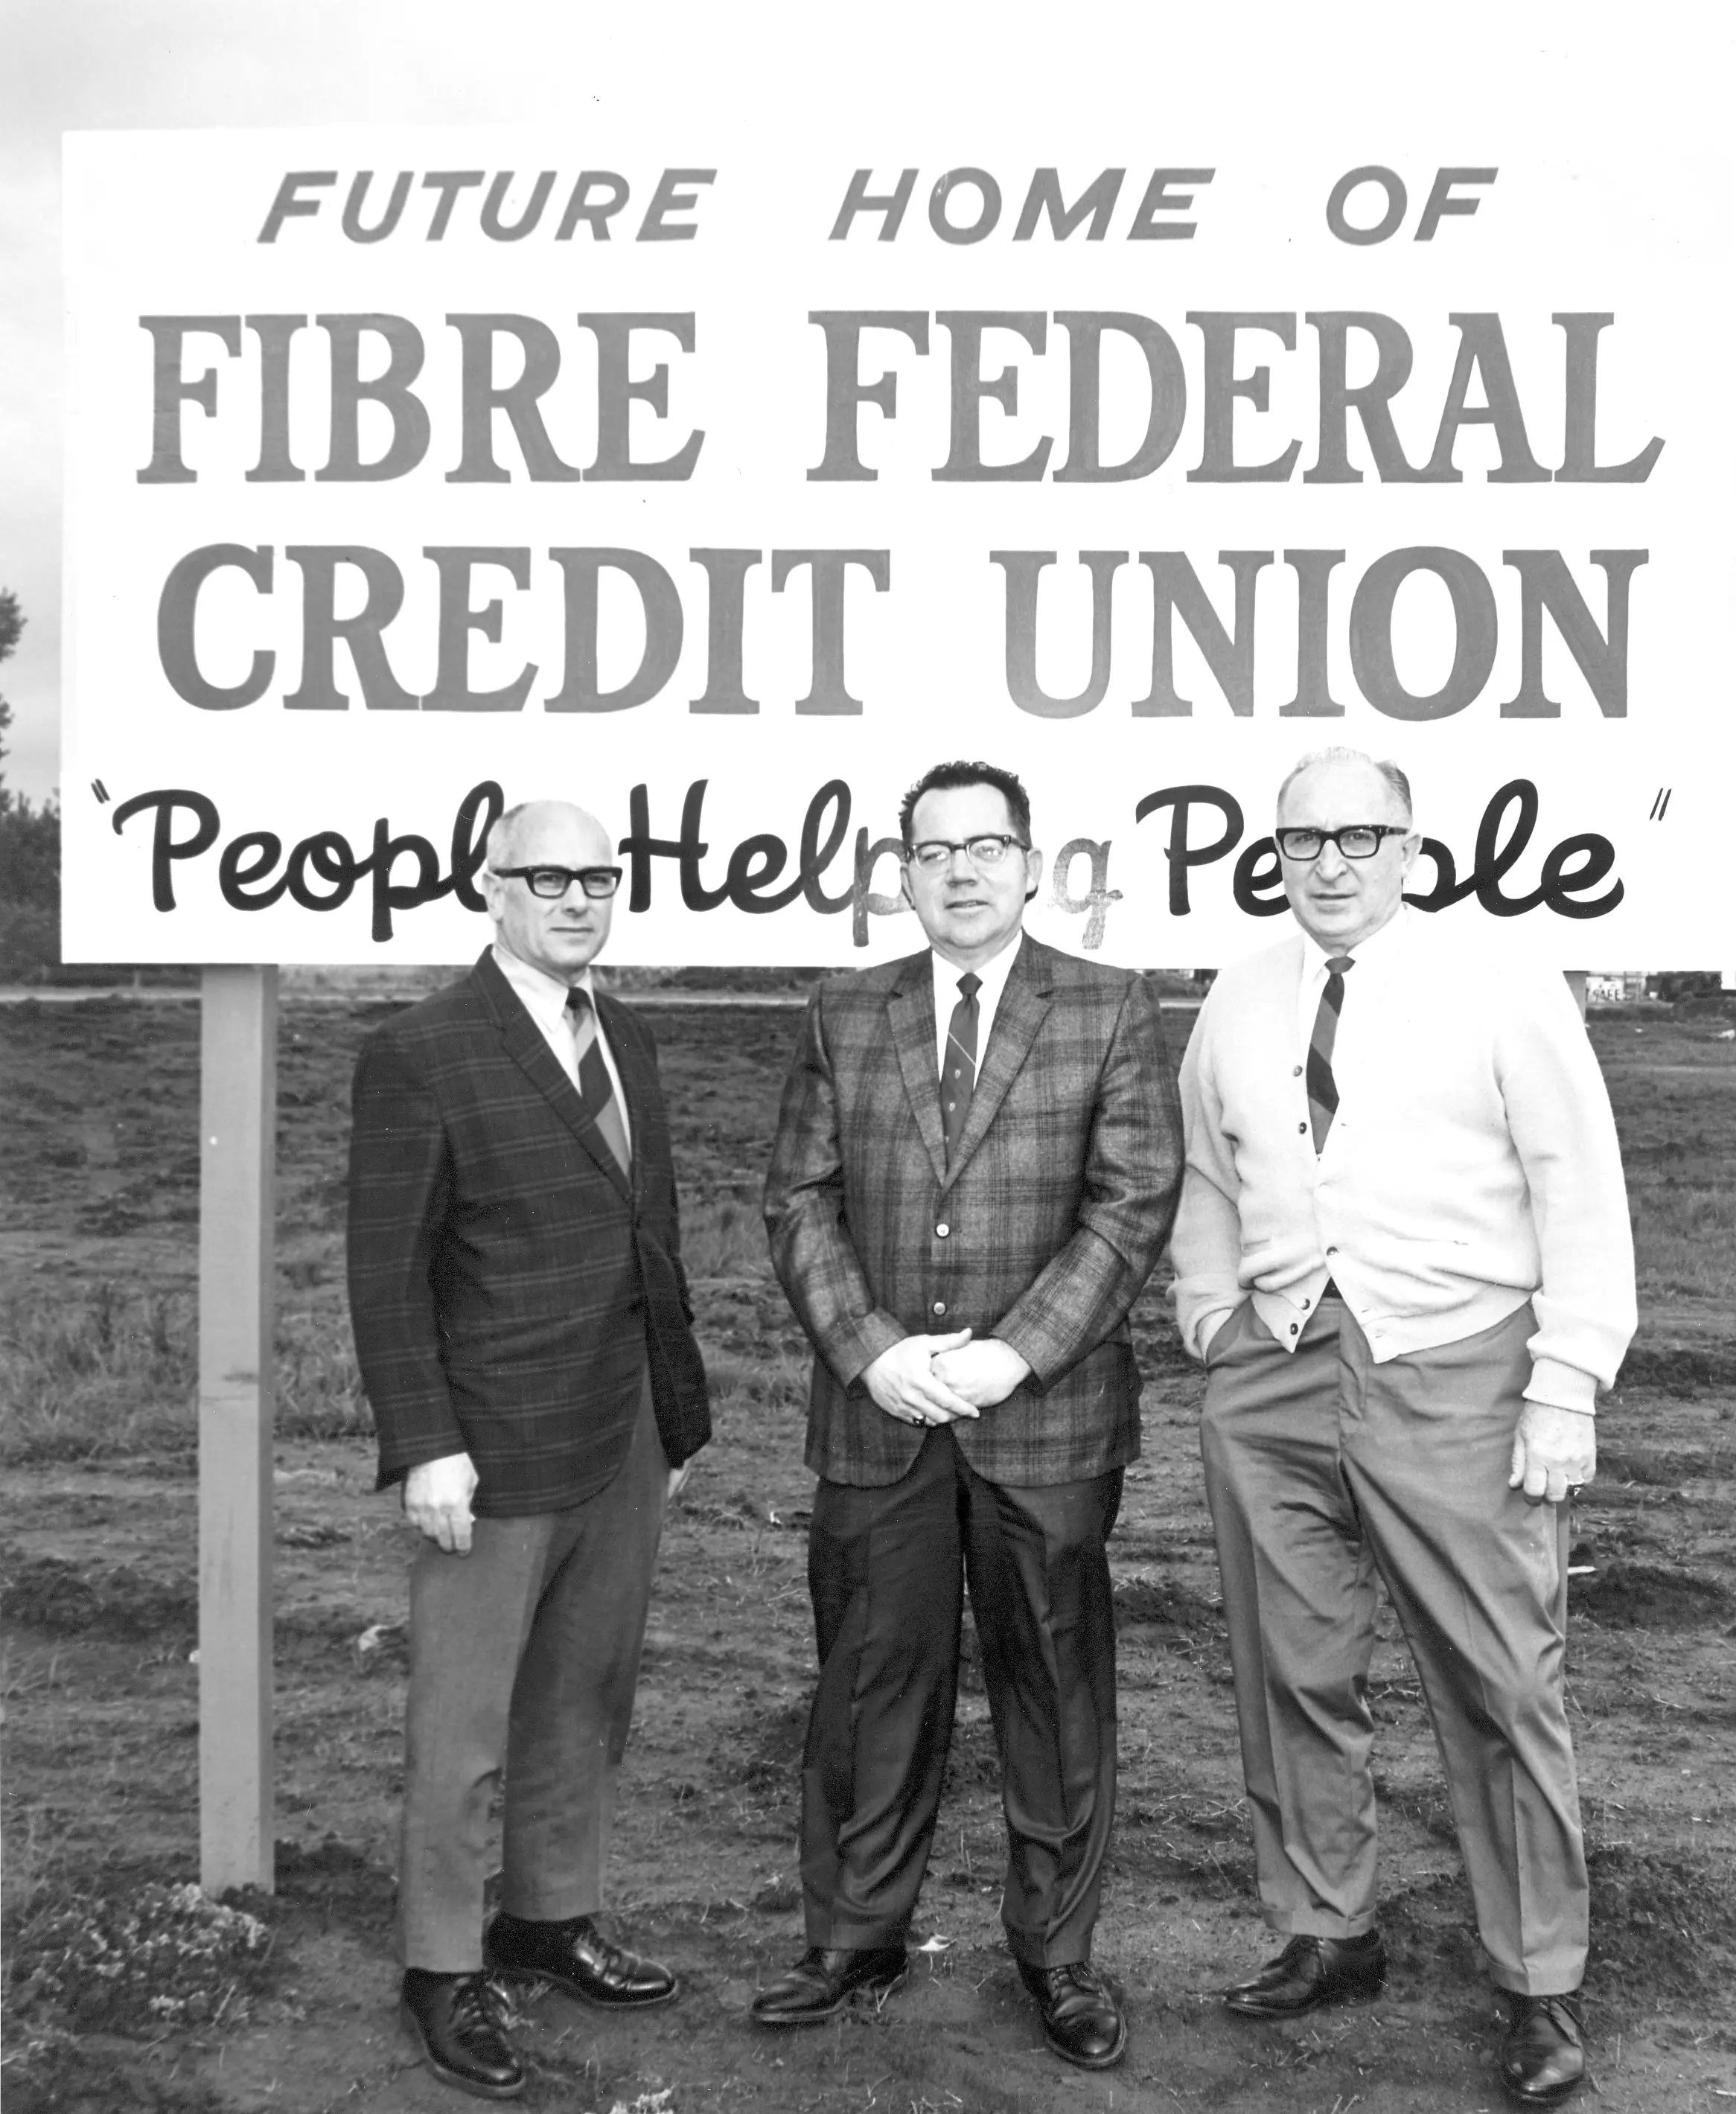
Future Home of Fibre Federal Credit Union - People Helping People

1937

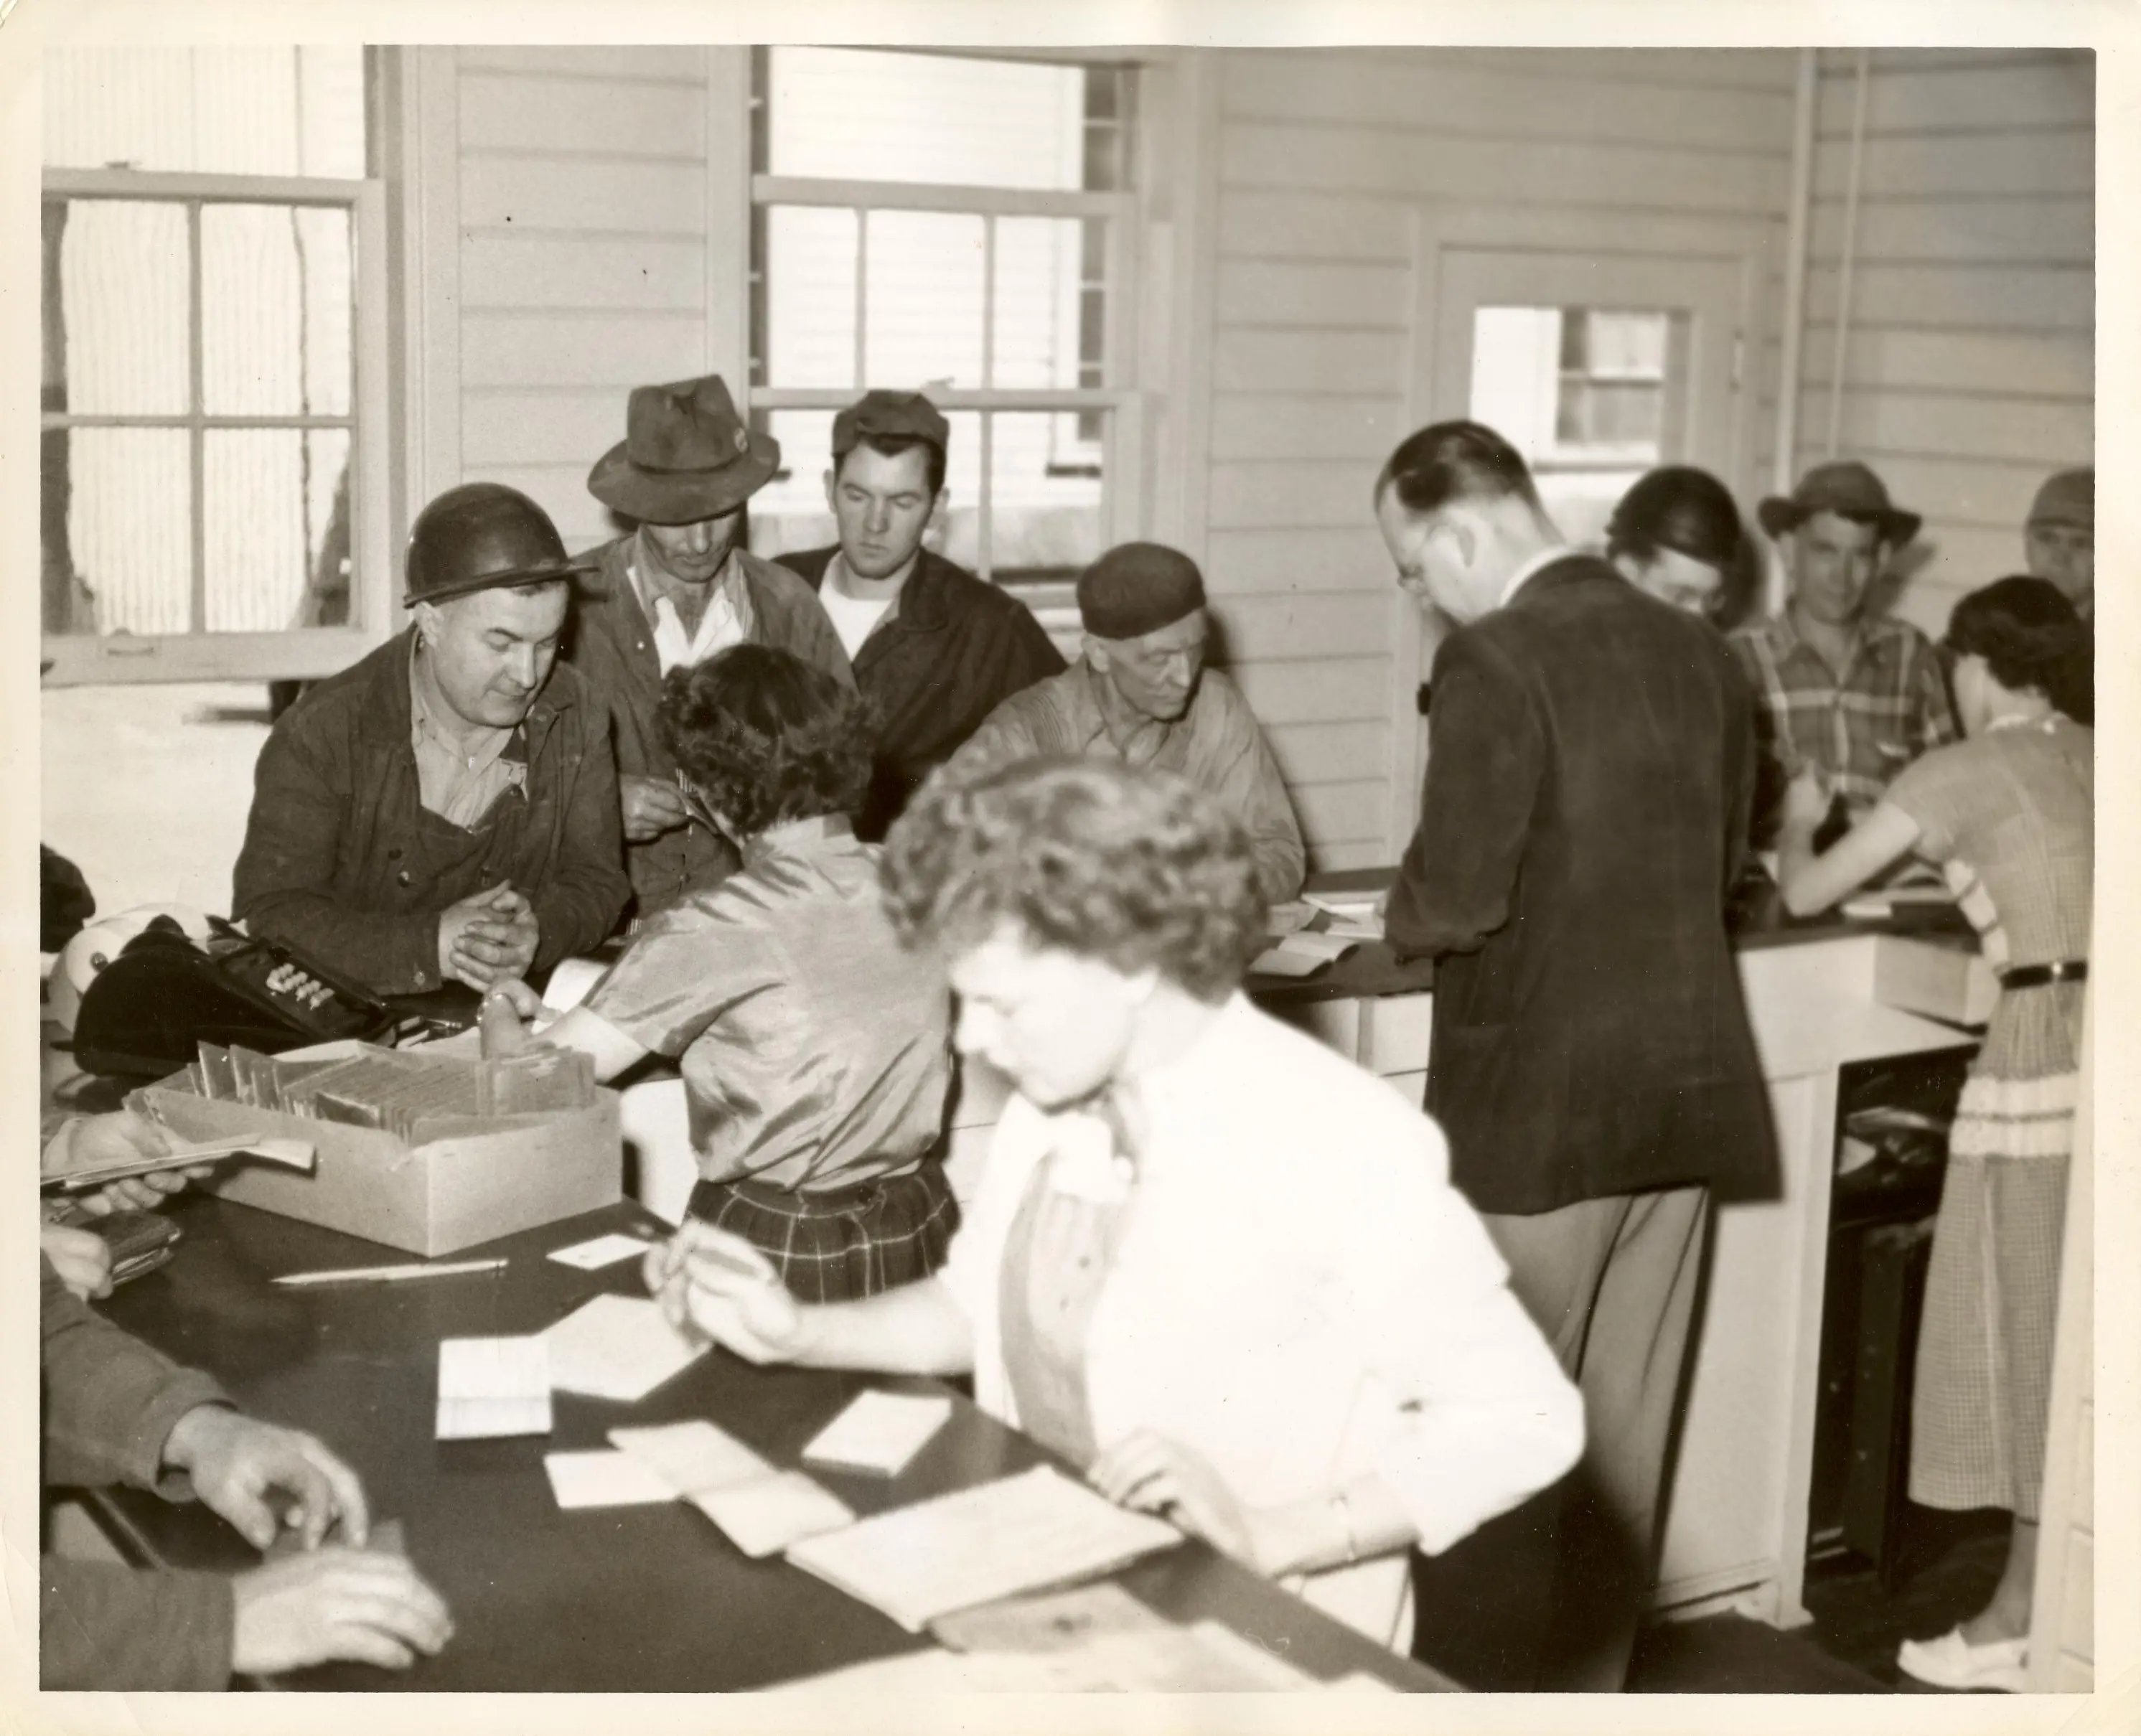
Sixty-three employees of Longview Fibre Company pooled together $315 and founded Fibre Federal Credit Union.

Anchor: richTextHtml

Accessing the HTML view in the Rich Text Editor

Although most of the site's features should not require anyone to do this, there exist a few column styles for paragraphs and lists and some other special features that could not be added to the sitefinity editor naturally. Additionally, this view can be used to clean up or double check code when needed.
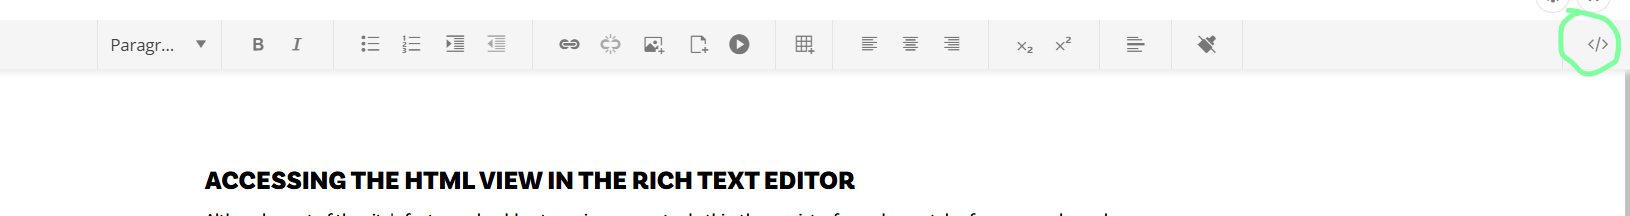
To access the html view, click somewhere in the text box and then select the  </> in the top right corner. (If the </> isn't visible, the window may need to be made larger.) 


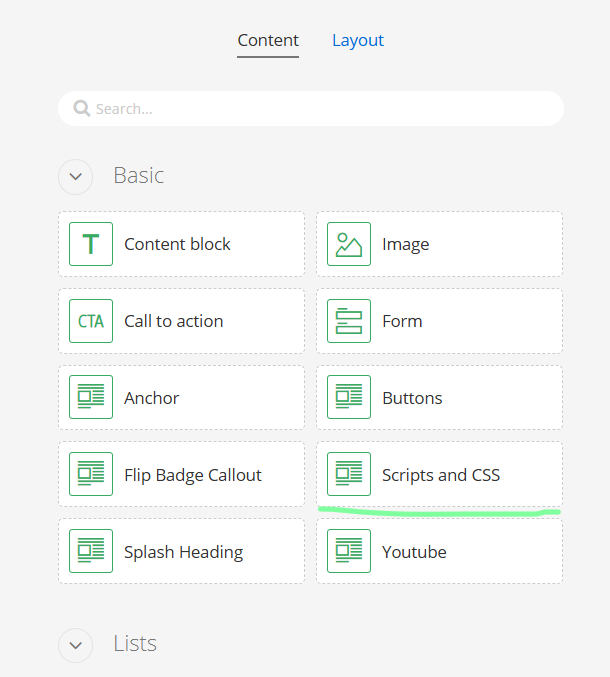
This view should not be used to add iframes, embed codes, etc. Those may get "cleansed" by the rich text editor's code cleaner. For embeds, please use the scripts and css widget instead.

Multi-column paragraphs

In order to avoid having to use the html view at all, these starter templates can just be copied where desired to preserve the relevant styling. To make a list or paragraph that already exists contain columns, tab to the html view and add class="cols-2" or class="cols-3" to the paragraph or list. A paragraph with cols-2 code looks like this, as an example of placement for the class:

<p class="cols-2">Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut

    aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.</p>

And a list looks like this:

<ul class="cols-2">
    <li>List item 1</li>
    <li>List item 2</li>
    <li>List Item 3</li>
    <li>List item 4</li>
</ul>


For lists, the class check-list can also be added to unordered lists to invoke special styling, with examples below: 

<ul class="check-list ">
    <li>List item 1</li>
    <li>List item 2</li>
    <li>List Item 3</li>
    <li>List item 4</li>
</ul>

Renders as : 

  • List item 1
  • List item 2
  • List Item 3
  • List item 4

With columns, the check list's code looks like:

<ul class="check-list cols-2">

    <li>List item 1</li>
    <li>List item 2</li>
    <li>List Item 3</li>
    <li>List item 4</li>
</ul>


cols-2

Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.

cols-3

Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.

Multi-column lists

cols-2

  1. List item 1
  2. List item 2
  3. List Item 3
  4. List item 4

cols-3

  1. List item 1
  2. List item 2
  3. List Item 3
  4. List item 4
  5. List Item 5
  6. List item 6

Examples of interactions with dark backgrounds

Style Guide

This page is a guide to the text and widget styles available on the site.


Text Styles


H2 Title

H3 Title

H4 Title

H5 Title
H6 Title

Paragraph Copy Lorem Ipsum

Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.

Color Text

Color2 Text

Color3 Text

Grey Text

Large Text

Small Text

Uppercase Text

Thin Text

Extra Bold Text

Color, Color2, Color 3, and Grey Text in a title

Lists

  • List Item 1
    1. List Item 1
    2. List Item 2
      • List item 1
      • List item 2
    • List item 1
    • List item 2
  • List Item 2
  • List Item 3
  • List item 4
  1. List Item 1
  2. List Item 2
    • List item 1
    • List item 2
  3. List Item 3
  4. List item 4
  • List item 1
  • List item 2
  • List Item 3
  • List item 4
  • List Item 1
    1. List Item 1
    2. List Item 2
      • List item 1
      • List item 2
    • List item 1
    • List item 2
  • List Item 2
  • List Item 3
  • List item 4
  • List item 1
  • List item 2
  • List Item 3
  • List item 4

Other

Callout Text Here

Quotation Cite

Line Rules

Separator


Flip badge callout

The flip badge would need a new color set of image designed. 

Splash Heading

Custom Title

Not all home loans are the same, and mortgage terms can vary significantly. That's why understanding how home loans work is so important. Knowing how different loan terms and types of mortgages affect your budget can help you choose the right home loan for your needs. Let's take a look at how different loan terms work, what they mean for your monthly payment, and how they affect your total borrowing costs.

UNDERSTANDING MORTGAGE TERMS

When you take out a mortgage, the loan term is the maximum amount of time you have to repay the money you borrowed, plus interest. For example, a 30-year mortgage gives you 30 years to pay off your home loan. However, you can always make extra payments or pay off your mortgage early to save on interest. 

If your financial goals change, refinancing may allow you to switch to a shorter or longer loan term. Refinancing replaces your mortgage with a new mortgage that may have a different interest rate and monthly payment. Closing costs apply when you refinance, so be sure to consider whether the benefits outweigh the costs.  

How long are home loans? In the U.S., the most common home loan term is 30 years. At Fibre Federal, we offer mortgages with terms of 10, 15, 20, and 30 years. The right term for you depends on your budget, long-term plans, and how quickly you want to build equity. 

The chart below compares the advantages and trade-offs of common mortgage terms:

Mortgage Term

Monthly Payment

Total Interest Paid

Equity Growth

10 Years

Highest

Lowest

Fastest

15 Years

Higher

Lower

Faster

20 Years

Moderate

Moderate

Moderate

30 Years

Lowest

Highest

Slowest

The shortest mortgage term lenders offer is 10 years, while the longest is 40 years. While 30-year mortgages are the most popular option, terms longer than 30 years aren't common. A 40-year loan may give you a lower monthly payment, but it usually has stricter qualification requirements and a higher interest rate, meaning you'll pay significantly more interest over time.

HOW MORTGAGE AMORTIZATION WORKS

Mortgage amortization is the process that determines how much of your monthly payment goes toward the principal and interest over the life of the loan. When you start making payments on your loan, a larger portion goes toward interest. As you continue paying down the loan, more of your payment goes toward the principal.

Amortization affects how quickly you can build equity. Because more of your payments go toward interest in the beginning, your equity grows slowly at first. Later, as more of your payments go toward the principal, you build equity more quickly. Making extra payments can increase your home equity, reduce the amount of interest you pay, and potentially help you pay off your loan sooner.

The chart below shows how principal and interest are allocated:

Loan Stage

Payment Allocation

Equity Growth

Early Years

More interest, less principal

Slower

Middle Years

More balanced

Moderate

Later Years

More principal, less interest

Faster

HOW MORTGAGE TERMS AFFECT INTEREST RATES

When comparing mortgage terms, it's important to look at the annual percentage rate (APR) rather than just the interest rate. The APR includes the interest rate, loan fees, and mortgage points, giving you a more complete picture of your borrowing costs. 

The length of the mortgage term can have a significant impact on your APR. Short-term fixed-rate loans of 10 or 15 years usually have lower APRs because they're considered less risky and are repaid more quickly. On the other hand, longer loan terms of 20 or 30 years typically have higher APRs because the longer repayment period extends the loan and increases the lender's risk. 

Here are the key differences between shorter and longer mortgage terms:

Short-term mortgages (10 to 15 years)

  • Typically have lower APRs

  • Have higher monthly payments

  • Cost less in total interest 

Long-term mortgages (20 to 30 years)

  • Typically have higher APRs

  • Have lower monthly payments

  • Cost more in total interest 

With adjustable-rate mortgages (ARMs), your interest rate can increase or decrease over time based on market conditions. With fixed-rate mortgages, your rate is locked in and won't change over the life of the loan. Other factors can also affect your interest rate, including your credit score, loan-to-value (LTV) ratio, down payment amount, and current market conditions.

HOW MORTGAGE TERMS AFFECT MONTHLY PAYMENTS & BORROWING COSTS

The loan term you choose doesn't just affect your APR; it also affects your monthly payment. A longer loan term of 30 years allows you to spread out your payments over more time, giving you lower monthly payments. This can make your mortgage easier to fit into your budget, and it may even give you the flexibility to afford a higher-priced home.

If you finance a home with a shorter term, you'll pay off your loan balance sooner. Although a shorter term typically gives you a higher monthly payment, it often comes with a lower APR and allows you to build equity in your home more quickly.

A longer loan term can lower your monthly payment, but it can significantly increase your borrowing costs. The longer your repayment period, the more total interest you'll pay.

The chart below compares the monthly payment and total interest paid for a $400,000 fixed-rate conventional mortgage at 6% interest for 15- and 30-year terms.

Mortgage Term

Monthly Payment

Total Interest Paid

15 Years

$3,375.43

$207,576.92

30 Years

$2,398.20 

$463,352.76 

A 30-year mortgage can cost more than twice as much in total interest as a 15-year mortgage. That's why it's important to choose the shortest loan term that you can comfortably afford. 

WHEN TO CHOOSE A SHORT-TERM MORTGAGE

A short-term home loan can help you save money and build equity faster, but it’s not the right choice for every borrower. A 15- or 20-year mortgage may be a good fit if:

You Can Afford a Higher Monthly Mortgage Payment 

Although a shorter loan term will increase your monthly payment, it could help you save tens of thousands of dollars in interest over the life of your mortgage, depending on your loan balance. It can help you become mortgage-free sooner and free up money for other goals, like planning for retirement.

You Want to Build Equity Faster  

With a 15-year mortgage, a larger portion of your payment goes toward the principal each month. This allows you to build home equity more quickly than you would with a longer loan term. Having more equity can give you additional borrowing options in the future, like a home equity loan or HELOC, which can be used for home improvements, debt consolidation, or other major expenses. 

You Don’t Plan to Stay in Your Home Long

If you expect to sell your home within a few years, a shorter mortgage term may help you pay down your loan balance more quickly. This could leave you with more equity when you sell, potentially increasing the amount you can put toward your next home.

WHEN TO CHOOSE A LONG-TERM MORTGAGE

A long-term mortgage of 20 to 30 years helps you spread your loan payments over a longer period. A longer loan term may make sense when:

You Want a Lower Monthly Mortgage Payment

A 30-year loan provides more time to pay off your home, which lowers your monthly payment. This can give you more breathing room in your budget to cover daily expenses, build an emergency fund, contribute to retirement savings, or work toward other financial goals. Lower monthly payments may also make it easier to qualify for a home that fits your needs.

You Want the Flexibility to Make Extra Payments

Choosing a longer-term mortgage doesn't mean you have to pay it off slowly. You can make additional payments toward the principal whenever your budget allows. This gives you the benefit of lower monthly payments while allowing you to pay off your mortgage ahead of schedule if your financial situation changes.

You Want to Buy the Most House You Can Afford

A longer loan term may increase the amount you qualify to borrow by lowering your monthly mortgage payment. This can give you more flexibility when choosing a home and help you find one that truly fits your needs. It may allow you to purchase a larger home or choose a property in a preferred neighborhood.

Frequently Asked Questions

Can you change your mortgage term?

Yes. You can change your mortgage term later by refinancing your home loan. Keep in mind, however, that refinancing may change your interest rate and involve closing costs, so it's important to compare your options before making a decision.

What's the difference between a fixed-rate and adjustable-rate mortgage?

With a fixed-rate mortgage, the interest rate stays the same throughout the life of the loan, and your principal and interest payments won't change. An adjustable-rate mortgage (ARM) offers a fixed interest rate that may be lower than fixed-rate mortgages for an introductory period. After that, the rate can increase or decrease over time based on market conditions.

What is the average mortgage term?

The most common mortgage term is 30 years. However, many lenders also offer mortgages with terms of 10, 15, and 20 years.

Should I get a 15- or 30-year mortgage?

It depends on your budget and financial goals. A 15-year mortgage can help you pay off your home sooner, build equity faster, and save money on interest, but it comes with higher monthly payments. A 30-year mortgage offers lower monthly payments, but you'll typically pay more interest over the life of the loan. 

Can you pay off a mortgage early?

It depends on the mortgage lender. With Fibre Federal, there are no early prepayment penalties. Paying off your mortgage early could help you save money on interest, depending on your remaining balance.

CHOOSE THE MORTGAGE THAT’S RIGHT FOR YOU

Choosing the right mortgage term is one of the most important financial decisions you'll make when buying a home. That's why comparing different loan terms and considering how long you plan to stay in your home is essential. The mortgage you choose will affect your monthly payment, total borrowing costs, and how quickly you build equity. 

Ready to take the next step? Explore our low-rate mortgage loans and find the term that works best for your needs and budget.
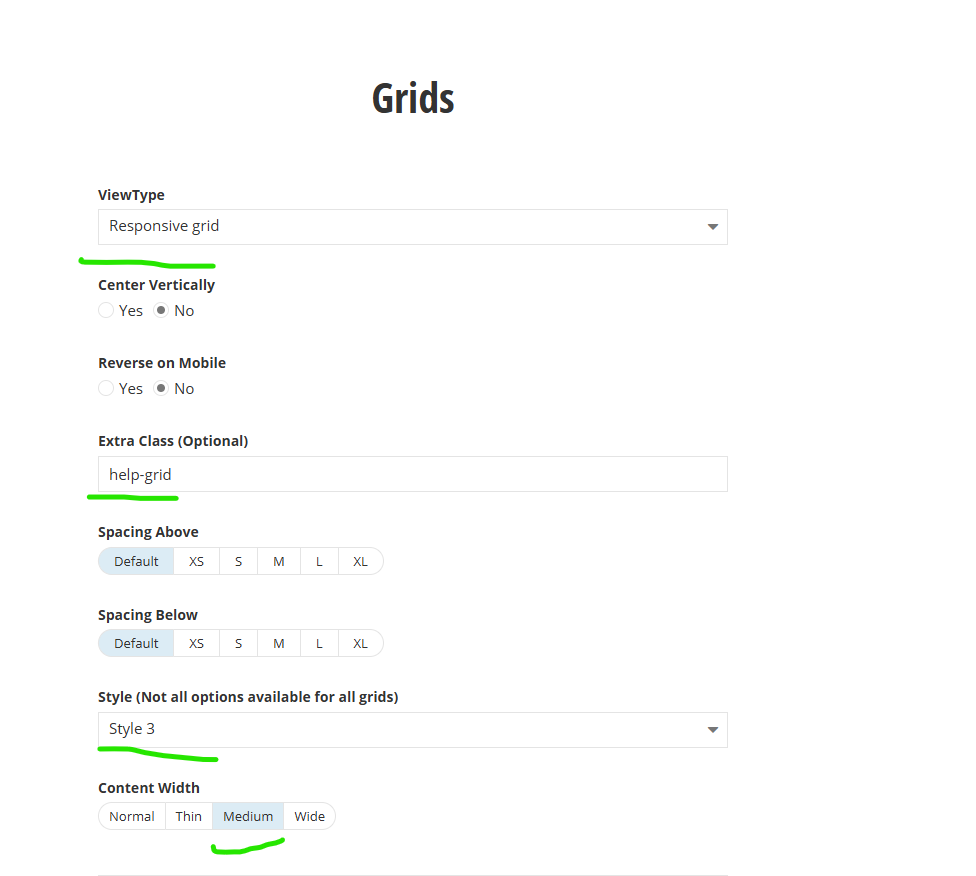
Frequently Asked Questions

Need technical support or have additional questions about Digital Wallets?

As much as we’d like to help you with all your concerns and questions, “technical” means different things to different smartphone users! But check out our handy list of providers who can help you get digital wallet set up on your mobile device today. By clicking on your mobile provider, you can get answers on how to use digital wallet and which devices are compatible.

If my card is blocked, can I still use my Digital Wallet to make purchases?

Fibre Federal Digital Wallet does not transfer your card number data but uses a unique “token” code for each transaction. This process is called “tokenization” and it helps safeguard your card information when you make a purchase.

This means that when you make a purchase, the digital wallet will generate a token instead of sending your credit or debit card information to the merchant. The token is used to process the payment while your personal information stays secure.
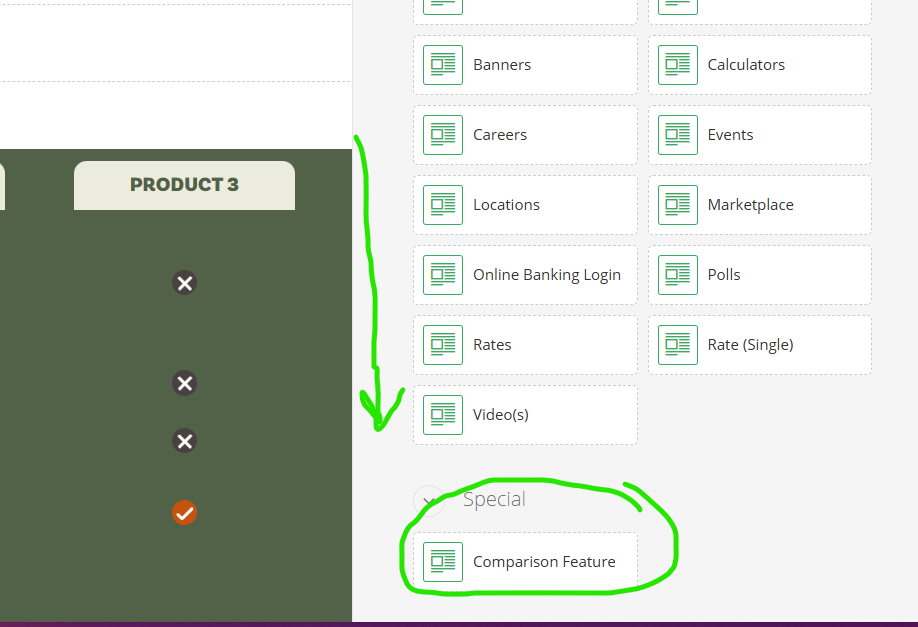
Plus, as an extra layer of protection, access to your Fibre Federal Digital Wallet is protected by a PIN or other security measure to prevent unwanted access.

Finally, by storing your cards digitally, you can worry less about them being lost or stolen. 

What do I do if I lose my device?

Password protect your smartphone, and install anti-virus software on your phone, such as Avast. Phones have been the latest targeting in SMS messaging, and apps that mimic banking apps, or run while using banking apps.

If you lose your device, contact your cell phone provider immediately. As a precaution, you can contact us at 1-800-205-7872 during business hours or 1-833-462-0796 after hours to block your card.


What do I do if my debit or credit card is lost or stolen?

If your card is lost or stolen, we are here to help. If you report suspicious activity to us we will stop further use of the impacted card, replace it and issue a new card number at no cost to you. Contact our 24/7 Card Care Center at 1-833-462-0796.

Real Words, Real People from the PNW

Best financial institution I have ever used! Super friendly, helpful staff members who give excellent service and are very knowledgeable about their products and services. I love how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
Translate »