These are styles that can be added through the tools and style dropdown in the rich text editor (Content blocks, other areas with a rich text editor like the content blocks')
H2 Title
H3 Title
H4 Title
H5 Title
H6 Title
Paragraph Copy Lorem Ipsum
Color Text
Color2 Text
Color3 Text
Grey Text
Large Text
Larger Text
Small Text
Uppercase Text
Thin Text
Extra Bold Text
Color, Color2, Color 3, and Grey Text in a title
Lists
List Item 1
List Item 1
List Item 2
List item 1
List item 2
List item 1
List item 2
List Item 2
List Item 3
List item 4
List Item 1
List Item 2
List item 1
List item 2
List Item 3
List item 4
List Item 1
List Item 1
List Item 2
List item 1
List item 2
List item 1
List item 2
List Item 2
List Item 3
List item 4
Other
Callout Text Here
Quotation Cite
Line Rules
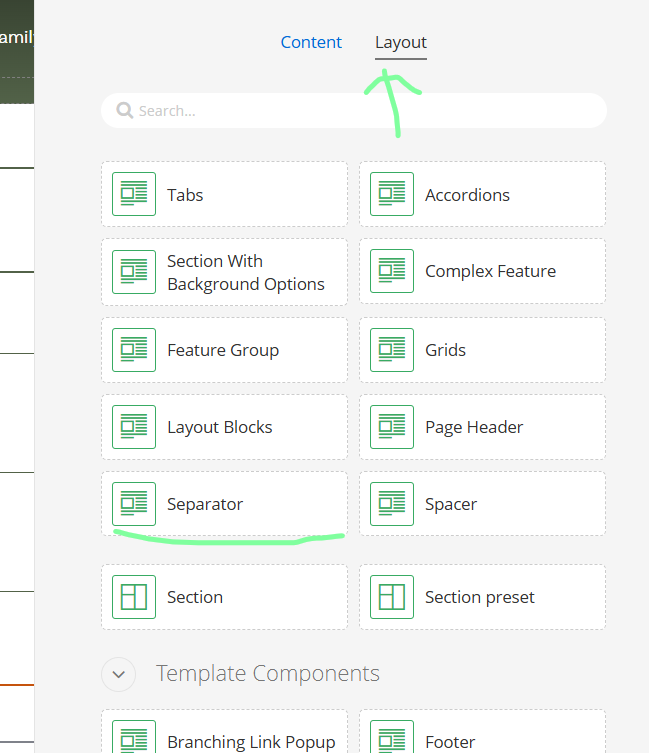
Separator
Further styles and more customized separators are available under the "separators" tool under "layout"
Link Styles
The button variants should only be used when a single button is needed and it doesn't need to be shared anywhere. These can be added through the "Link Style" dropdown under "More Options" when creating a link in the rich text editor.
A button can be added through the link style dropdown in any link within a rich text editor or content block.
CTAs widget can provide buttons unique to a page.
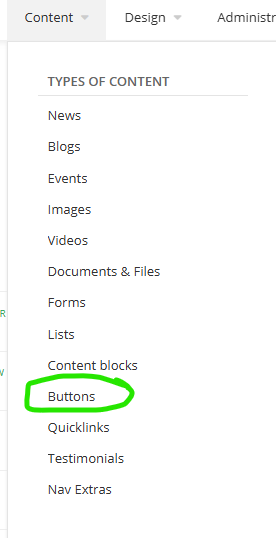
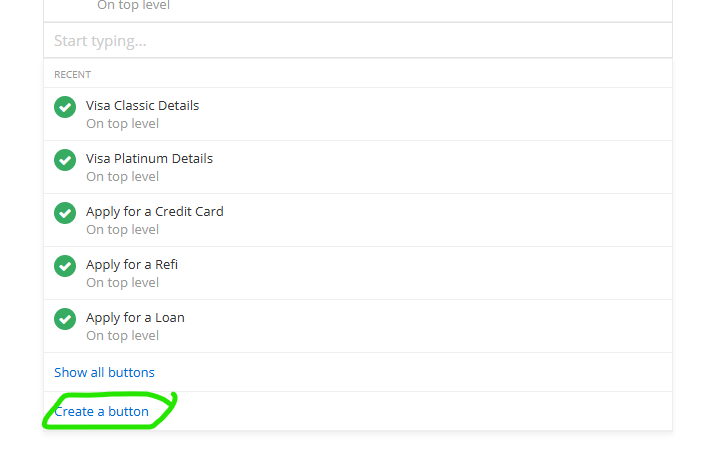
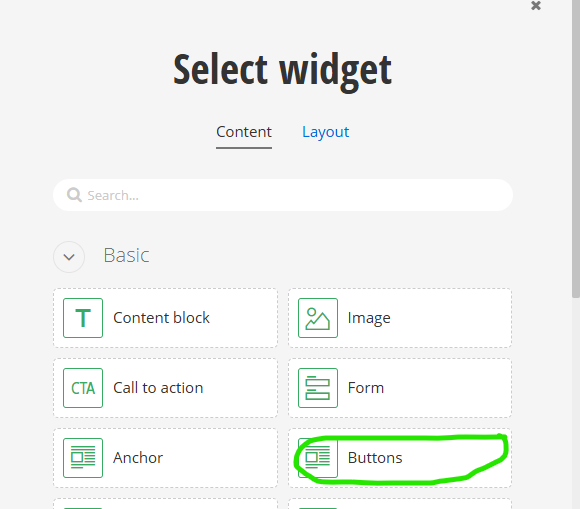
Furthermore, buttons can be added to the buttons widget. Buttons added to the buttons widget are shared between all instances of the button. Shared buttons are recommended because if a link is changed later, then all buttons linking to the link be changed at once.
Call to Action (CTAs) Widget
CTAs are recommended when no more than two buttons are needed, and the buttons are unique to the page and aren't to be used anywhere else on the site.
The options available in the CTAs widget are also more limited than the options available through the shared buttons widget.
By default, the front is the fibre logo, but it can be customized.
Just drop content here after adding the widget
It's simple
It's easy
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor .
Splash Heading
These are the headings used on the home page. Although they are not used on the inside pages by default, support for them exists to allow future use in potential landing pages.
Pre-Heading
Splash Heading
Anchor
Anchor is used to easily add a location to the page that can be linked to by any link's "anchor" field. Note that each anchor's value can only be used once per page, or the linking will break.
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis. Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Quis ipsum suspendisse ultrices gravida. Risus commodo viverra maecenas accumsan lacus vel facilisis.
Anchor: jumpLink
Youtube
Allows easy embedding of a youtube video. Simply copy this part of the end of the youtube video's url (after ?v= and before any other &)
and paste it into the video id field in the widget's edit panel.
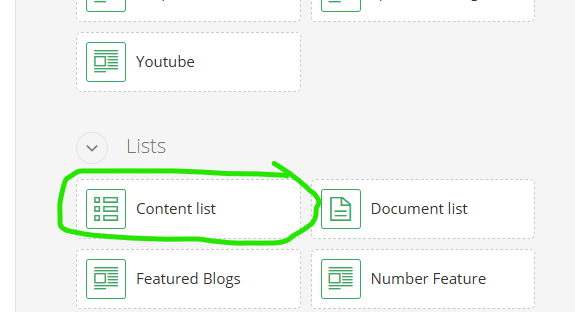
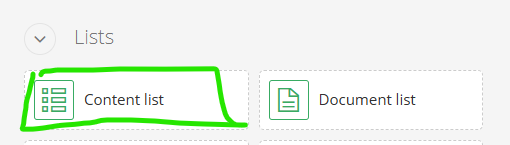
The Content List
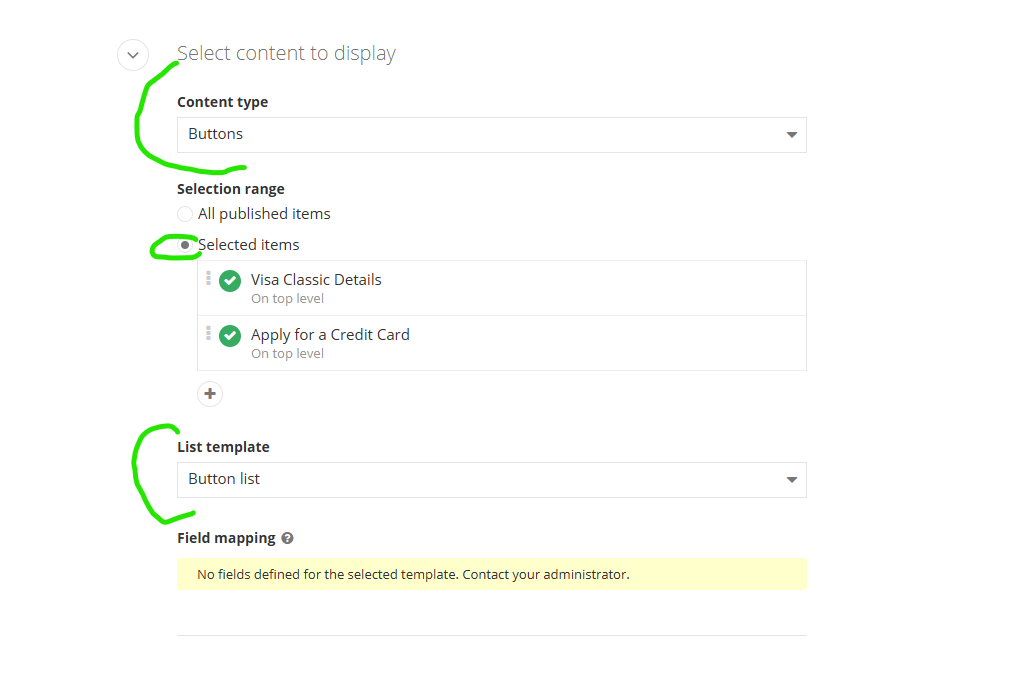
A number of different types of content can be selected through this widget.
Buttons have already been listed above, so they are skipped here.
News shares an appearance with Blogs but is not used because of the greater flexibility added by Blogs' ability to contain posts under a parent blog.
Events is not used on this site and rarely used in general-- if needed later, please contact us to add styling for it.
Nav extras is a module set up to allow the items to be selected into top level pages' title and properties tab for display on their nav dropdown. It should not be used in page content.
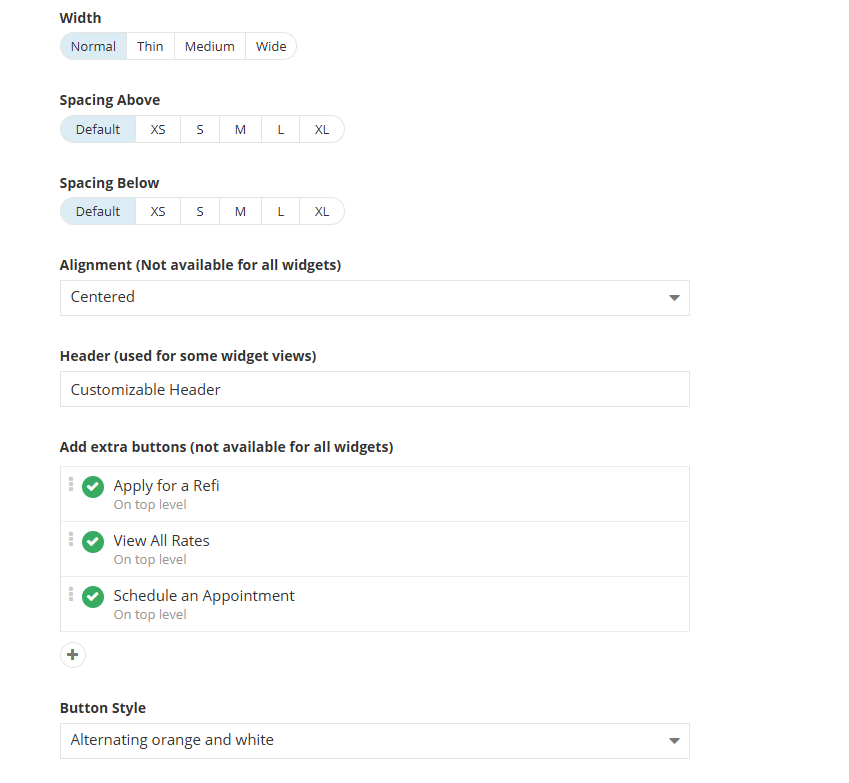
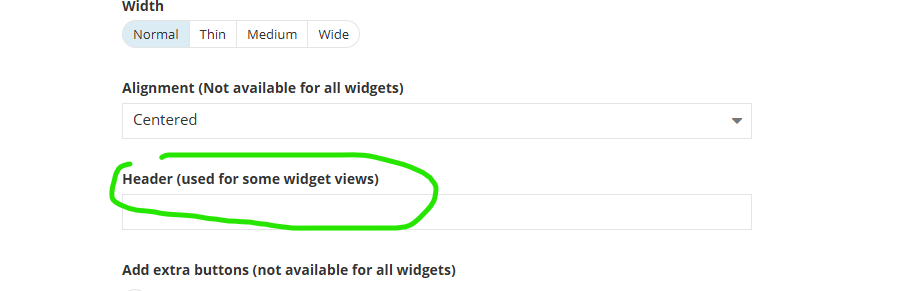
Depending on the widget, various other options may be available under list settings. Order By, Spacing, and Width are available for all widgets. Buttons are available for quicklinks, lists, and some testimonial templates and styles. Header is available for quicklinks, lists, blog lists, and some testimonial templates. Alignment is only relevant for buttons (for now).
Only blog and news take advantage of the items under detail view settings.
Blogs
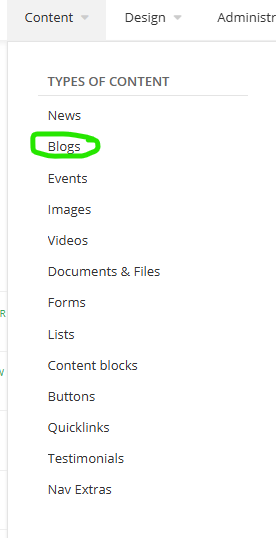
Blog posts can be added under content - > Blogs, then clicking into the blog the post should be added to.
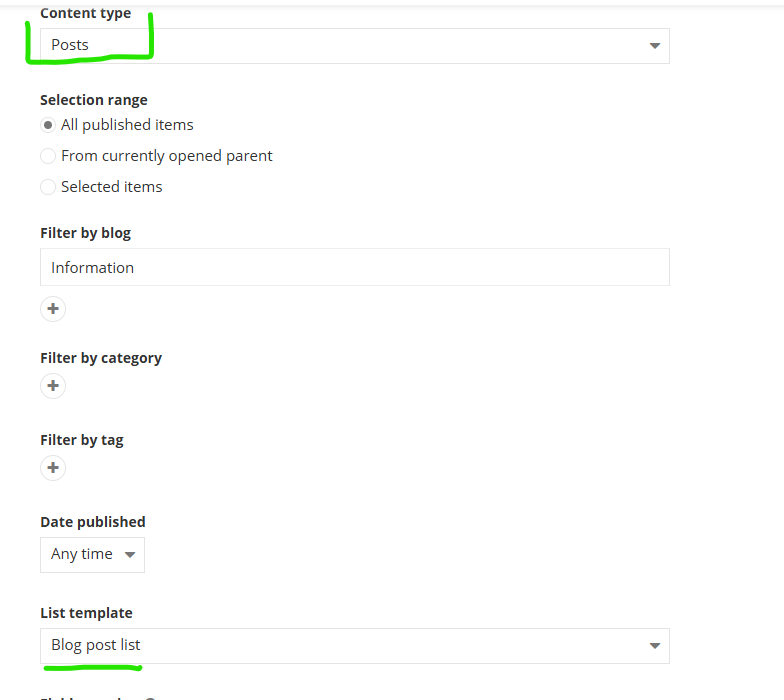
To add the posts to the page, "Posts" should be set as the Content type, and "Blog post list" should be set as the template.
To display all blog posts, all published items can be set to show without modification. However, the posts can be set to draw only posts from a specific blog and/or category, which allows more nuanced selection of content. For example, featured posts on the auto loans page can be set to draw only posts from the Information blog and the Auto Loans category. This allows for a much easier maintenance of the post system across multiple pages, because the post lists can then automatically update with the latest information as new posts are added, without each post list needing the posts selected manually every time.
Style 1 shows all posts.
Aug 24, 2026
What Type of Home Loans Are There? Explore Your Options
Every family is different and all homes are different, which is why there's a range of mortgages to cater to different needs and wants. Whether you're a first-time buyer or a homeowner looking for a change— it can be confusing when navigating all your options.
Our quick guide can help you figure out what types of home loans are available and which one might be best for you.
AN OVERVIEW OF DIFFERENT MORTGAGE LOANS
We can split mortgages into two broad categories to help answer the question, “What type of home loans are there?” Government-backed home loans come with certain conditions and offer great benefits if you're eligible. For everyone else, a conventional loan is probably best.
Conventional Loans
These loans are offered by private lenders like credit unions, banks, and online mortgage brokers. They may be conforming (meet the guidelines of Fannie Mae and Freddie Mac) or non-conforming.
Fixed-rate home loans: Offer a steady interest rate over loan terms of 10, 15, 20, or 30 years for your primary residence.
Adjustable-rate mortgage (ARM) loans: Offer a low, fixed rate for an initial period and then adjust with market rates on a predetermined schedule.
Jumbo Loans: These non-conforming loans let you borrow higher loan amounts if you have the necessary down payment and meet other criteria.
Bare Land Loans: Help you buy land on which you plan to build a home (Build Land Loans) or empty land that you don't plan to develop (Raw Land Loans).
Vacation Home Loans: Give you the financing to buy a second property for vacation purposes.
Government-Backed Loans
These loans are partially insured by government departments so private lenders can offer loans to people who may not otherwise qualify, or offer better rates than the person might get for a conventional loan. The insurance covers the lender in case the borrower defaults.
FHA Loans: Insured by the Federal Housing Authority so more people may qualify for a home loan, as long as the property meets appraisal guidelines.
VA Loans: Insured by the U.S. Department of Veterans Affairs to provide competitive home loans to veterans and other eligible military personnel, with appraisal guidelines.
USDA Loans: Insured by the U.S. Department of Agriculture to help people buy a home in eligible rural areas, as long as their household income is below a certain limit.
FIXED-RATE MORTGAGE LOANS
A fixed-rate mortgage is a popular choice because you get to lock in a rate for the life of your loan, so your monthly payments remain steady which makes budgeting simple.
Key Details
Rates: The APR you get may be slightly higher than the initial rate for an adjustable-rate mortgage (ARM), but then your rate stays the same, while an ARM may go up and down.
Fees: You'll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: Choose from 10, 15, 20, or 30 years. Shorter terms get lower rates and accrue less total interest, while longer terms give lower monthly payments.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of a Fixed-Rate Mortgage
Pros: Budgeting is easy because your payments will remain steady apart from any changes to taxes and insurance.
Cons: Market rates may drop compared to what you lock in, so then you may need to refinance your mortgage to get a lower rate.
ADJUSTABLE-RATE MORTGAGE (ARM) LOANS
ARM home loans offer a low, fixed rate for an initial period that may be around 5 or 7 years which means you can enjoy lower payments at the start of your home loan. ARMs often suit people who plan to move, sell, or refinance in the short term.
Key Details
Rates: The APR you get for your initial period may be slightly lower than a fixed-rate loan, but then it will adjust with the markets and therefore could go higher or lower.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: ARMs offer a range of terms so be sure to read the fine print. There are caps on how much your rate can adjust the first time, each time, and in total over the life of your loan.
A 5/6 ARM means you get a fixed rate for 5 years, then it will adjust every 6 years until your loan is paid off in full.
A 7/6 ARM means you get a fixed rate for 7 years, then it adjusts every 6 years.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of an Adjustable-Rate Mortgage
Pros: You get lower payments at the start of your loan term and you may get a lower rate if market rates fall in the future.
Cons: Your rate may go up if market rates rise and your monthly payments may also go up and down over the life of your loan, so you need to plan for a possible increase.
JUMBO LOANS
A jumbo-loan is ideal if you want to buy a home that has a purchase price above the amount set by the Federal Housing Finance Agency (FHFA) each year.
Key Details
Rates: Jumbo loan rates are sometimes slightly higher than conforming loans but your rate will depend on your financial situation and chosen loan term.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is under 20%—though this may be the minimum down payment needed for a Jumbo Loan.
Loan terms: You may have fewer choices than for a conforming loan. For example, you may get the choice of a 15- or 30-year fixed-rate loan or a 10/1 ARM.
Qualifying: You may need very good credit, a significant down payment, and significant cash reserves to qualify.
Pros and Cons
Pro: You can buy a high-value home.
Cons: You need to have a large down payment and/or borrow a large loan amount so you should make sure you can comfortably afford the payments.
BARE LAND LOANS
A Build Land Loan is ideal if you have your eye on a nice piece of empty land or a vacant lot and you want to eventually build your home there. You might then get a construction loan and convert it to a regular home loan once your build is complete.
If you don't plan to develop the land, you can consider a Raw Land Loan.
Key Details
Rates: Land loan rates tend to be slightly higher than a mortgage for an existing home.
Fees: You don't need to pay private mortgage insurance (PMI).
Loan terms: You may get a term of 10 or 20 years.
Qualifying: As well as good credit and steady income, you may need to make a down payment of around 30% or as much as 50% for raw land.
Pros and Cons
Pros: You can buy the perfect spot for your future dream home.
Cons: You may need to prove you plan to build within a certain time frame and you may need a sizable down payment.
Build Land financing isn't available if the land can't be developed or doesn't perk.
Raw Land financing isn't available for commercial or industrial zoning.
VACATION HOME LOANS
You may qualify for a Vacation Home Loan if the property you want to buy is at least 50 miles from your primary residence and you don't plan to rent it out. Mortgages for primary homes, vacation homes, and rental or investment properties each have different rules.
Key Details
Rates: Rates for second homes may be slightly higher than for your first mortgage.
Fees: The standard down payment is 10% vs the typical 3%-5% for primary residences. PMI is needed for any purchase with less than 20% down.
Loan terms: Terms are available from 10, 15, 20, and 30 years.
Qualifying: You’ll need to show you have a debt-to-income (DTI) ratio that can carry two mortgages, you have great credit, a sufficient income, and a sizable down payment to get approved.
Pros and Cons
Pros: You can buy that alpine cottage or beach house to enjoy vacation time with the family.
Cons: You’ll need to manage two mortgages and use the property strictly as intended.
FHA LOANS
Federal Housing Administration (FHA) loans are designed to help more Americans become homeowners. You can be a first-time or repeat homebuyer as long as you meet the lending criteria and your home passes appraisal.
Key Details
Rates: FHA rates might be slightly higher than conventional homes.
Fees: You need to pay a Mortgage Insurance Premium (MIP) to help offset the risk of your loan. You might pay some MIP upfront, and some may get rolled into your APR.
Loan terms: You may get a choice of 15 or 30 years.
Qualifying: You may qualify with slightly lower credit and income levels compared to conventional loans and you need a down payment of just 3.5%.
Pros and Cons
Pros: FHA loans tend to offer easier qualifying criteria than conventional loans and lower down payments.
Cons: You need to buy a property that meets the appraisal guidelines, and this extra step sometimes means sellers prefer buyers with conventional loans.
VA LOANS
Veterans Affairs (VA) loans are available for eligible U.S. Veterans, active-duty service members, reservists, National Guard members, and surviving spouses. It's a lifetime benefit you can use to buy successive homes with no down payment needed. Your home needs to meet VA appraisal guidelines.
Key Details
Rates: VA loan rates tend to be slightly higher than for conventional loans.
Fees: You need to pay a VA funding fee (upfront or rolled into your APR) but you don't need to pay mortgage insurance.
Loan terms: You may get fewer or no choices compared to conventional loans. The most common term is 30 years.
Qualifying: You may qualify more easily than for conventional loans as long as you meet the eligibility criteria and minimum income and credit requirement, and pass the home appraisal.
Pros and Cons
Pros: You don't need a down payment and don't need to pay mortgage insurance.
Cons: You need to pay a VA funding fee and the property needs to go through the VA appraisal process. Because of this extra step, some sellers prefer buyers with conventional loans.
USDA LOANS
U.S. Department of Agriculture (USDA) Loans are available to people with moderate income who want to purchase a home in an eligible rural area. You may not need a down payment if you meet the other eligibility criteria.
Key Details
Rates: USDA loan rates tend to be slightly higher than for conventional loans.
Fees: You pay an upfront guarantee fee equal to 1% of the loan amount and an annual fee equal to 0.35 percent of the loan amount. You don't pay PMI.
Loan terms: You may get fewer choices than for conventional loans. The most common term is 30 years.
Qualifying: You may qualify with a lower income than for conventional loans and your income must be within a limit determined by where you live. The home must be in an eligible rural area and meet USDA appraisal guidelines.
Pros and Cons
Pro: You likely don't need a down payment.
Cons: Your income cannot be above a certain limit and your home must be in an eligible rural area and pass the appraisal.
CHOOSING THE BEST MORTGAGE LENDER
We hope we've answered your question, “What type of home loans are there?” But if you still have questions about which exact home loan and term is best for you, the most important thing is to choose a lender you trust who can work with you to make sure you have an enjoyable home buying experience.
Click below to see how Fibre Federal Credit Union can serve your needs!
Every family is different and all homes are different, which is why there's a range of mortgages to cater to different needs and wants. Whether you're a first-time buyer or a homeowner looking for a change— it can be confusing when navigating all your options.
Our quick guide can help you figure out what types of home loans are available and which one might be best for you.
AN OVERVIEW OF DIFFERENT MORTGAGE LOANS
We can split mortgages into two broad categories to help answer the question, “What type of home loans are there?” Government-backed home loans come with certain conditions and offer great benefits if you're eligible. For everyone else, a conventional loan is probably best.
Conventional Loans
These loans are offered by private lenders like credit unions, banks, and online mortgage brokers. They may be conforming (meet the guidelines of Fannie Mae and Freddie Mac) or non-conforming.
Fixed-rate home loans: Offer a steady interest rate over loan terms of 10, 15, 20, or 30 years for your primary residence.
Adjustable-rate mortgage (ARM) loans: Offer a low, fixed rate for an initial period and then adjust with market rates on a predetermined schedule.
Jumbo Loans: These non-conforming loans let you borrow higher loan amounts if you have the necessary down payment and meet other criteria.
Bare Land Loans: Help you buy land on which you plan to build a home (Build Land Loans) or empty land that you don't plan to develop (Raw Land Loans).
Vacation Home Loans: Give you the financing to buy a second property for vacation purposes.
Government-Backed Loans
These loans are partially insured by government departments so private lenders can offer loans to people who may not otherwise qualify, or offer better rates than the person might get for a conventional loan. The insurance covers the lender in case the borrower defaults.
FHA Loans: Insured by the Federal Housing Authority so more people may qualify for a home loan, as long as the property meets appraisal guidelines.
VA Loans: Insured by the U.S. Department of Veterans Affairs to provide competitive home loans to veterans and other eligible military personnel, with appraisal guidelines.
USDA Loans: Insured by the U.S. Department of Agriculture to help people buy a home in eligible rural areas, as long as their household income is below a certain limit.
FIXED-RATE MORTGAGE LOANS
A fixed-rate mortgage is a popular choice because you get to lock in a rate for the life of your loan, so your monthly payments remain steady which makes budgeting simple.
Key Details
Rates: The APR you get may be slightly higher than the initial rate for an adjustable-rate mortgage (ARM), but then your rate stays the same, while an ARM may go up and down.
Fees: You'll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: Choose from 10, 15, 20, or 30 years. Shorter terms get lower rates and accrue less total interest, while longer terms give lower monthly payments.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of a Fixed-Rate Mortgage
Pros: Budgeting is easy because your payments will remain steady apart from any changes to taxes and insurance.
Cons: Market rates may drop compared to what you lock in, so then you may need to refinance your mortgage to get a lower rate.
ADJUSTABLE-RATE MORTGAGE (ARM) LOANS
ARM home loans offer a low, fixed rate for an initial period that may be around 5 or 7 years which means you can enjoy lower payments at the start of your home loan. ARMs often suit people who plan to move, sell, or refinance in the short term.
Key Details
Rates: The APR you get for your initial period may be slightly lower than a fixed-rate loan, but then it will adjust with the markets and therefore could go higher or lower.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: ARMs offer a range of terms so be sure to read the fine print. There are caps on how much your rate can adjust the first time, each time, and in total over the life of your loan.
A 5/6 ARM means you get a fixed rate for 5 years, then it will adjust every 6 years until your loan is paid off in full.
A 7/6 ARM means you get a fixed rate for 7 years, then it adjusts every 6 years.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of an Adjustable-Rate Mortgage
Pros: You get lower payments at the start of your loan term and you may get a lower rate if market rates fall in the future.
Cons: Your rate may go up if market rates rise and your monthly payments may also go up and down over the life of your loan, so you need to plan for a possible increase.
JUMBO LOANS
A jumbo-loan is ideal if you want to buy a home that has a purchase price above the amount set by the Federal Housing Finance Agency (FHFA) each year.
Key Details
Rates: Jumbo loan rates are sometimes slightly higher than conforming loans but your rate will depend on your financial situation and chosen loan term.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is under 20%—though this may be the minimum down payment needed for a Jumbo Loan.
Loan terms: You may have fewer choices than for a conforming loan. For example, you may get the choice of a 15- or 30-year fixed-rate loan or a 10/1 ARM.
Qualifying: You may need very good credit, a significant down payment, and significant cash reserves to qualify.
Pros and Cons
Pro: You can buy a high-value home.
Cons: You need to have a large down payment and/or borrow a large loan amount so you should make sure you can comfortably afford the payments.
BARE LAND LOANS
A Build Land Loan is ideal if you have your eye on a nice piece of empty land or a vacant lot and you want to eventually build your home there. You might then get a construction loan and convert it to a regular home loan once your build is complete.
If you don't plan to develop the land, you can consider a Raw Land Loan.
Key Details
Rates: Land loan rates tend to be slightly higher than a mortgage for an existing home.
Fees: You don't need to pay private mortgage insurance (PMI).
Loan terms: You may get a term of 10 or 20 years.
Qualifying: As well as good credit and steady income, you may need to make a down payment of around 30% or as much as 50% for raw land.
Pros and Cons
Pros: You can buy the perfect spot for your future dream home.
Cons: You may need to prove you plan to build within a certain time frame and you may need a sizable down payment.
Build Land financing isn't available if the land can't be developed or doesn't perk.
Raw Land financing isn't available for commercial or industrial zoning.
VACATION HOME LOANS
You may qualify for a Vacation Home Loan if the property you want to buy is at least 50 miles from your primary residence and you don't plan to rent it out. Mortgages for primary homes, vacation homes, and rental or investment properties each have different rules.
Key Details
Rates: Rates for second homes may be slightly higher than for your first mortgage.
Fees: The standard down payment is 10% vs the typical 3%-5% for primary residences. PMI is needed for any purchase with less than 20% down.
Loan terms: Terms are available from 10, 15, 20, and 30 years.
Qualifying: You’ll need to show you have a debt-to-income (DTI) ratio that can carry two mortgages, you have great credit, a sufficient income, and a sizable down payment to get approved.
Pros and Cons
Pros: You can buy that alpine cottage or beach house to enjoy vacation time with the family.
Cons: You’ll need to manage two mortgages and use the property strictly as intended.
FHA LOANS
Federal Housing Administration (FHA) loans are designed to help more Americans become homeowners. You can be a first-time or repeat homebuyer as long as you meet the lending criteria and your home passes appraisal.
Key Details
Rates: FHA rates might be slightly higher than conventional homes.
Fees: You need to pay a Mortgage Insurance Premium (MIP) to help offset the risk of your loan. You might pay some MIP upfront, and some may get rolled into your APR.
Loan terms: You may get a choice of 15 or 30 years.
Qualifying: You may qualify with slightly lower credit and income levels compared to conventional loans and you need a down payment of just 3.5%.
Pros and Cons
Pros: FHA loans tend to offer easier qualifying criteria than conventional loans and lower down payments.
Cons: You need to buy a property that meets the appraisal guidelines, and this extra step sometimes means sellers prefer buyers with conventional loans.
VA LOANS
Veterans Affairs (VA) loans are available for eligible U.S. Veterans, active-duty service members, reservists, National Guard members, and surviving spouses. It's a lifetime benefit you can use to buy successive homes with no down payment needed. Your home needs to meet VA appraisal guidelines.
Key Details
Rates: VA loan rates tend to be slightly higher than for conventional loans.
Fees: You need to pay a VA funding fee (upfront or rolled into your APR) but you don't need to pay mortgage insurance.
Loan terms: You may get fewer or no choices compared to conventional loans. The most common term is 30 years.
Qualifying: You may qualify more easily than for conventional loans as long as you meet the eligibility criteria and minimum income and credit requirement, and pass the home appraisal.
Pros and Cons
Pros: You don't need a down payment and don't need to pay mortgage insurance.
Cons: You need to pay a VA funding fee and the property needs to go through the VA appraisal process. Because of this extra step, some sellers prefer buyers with conventional loans.
USDA LOANS
U.S. Department of Agriculture (USDA) Loans are available to people with moderate income who want to purchase a home in an eligible rural area. You may not need a down payment if you meet the other eligibility criteria.
Key Details
Rates: USDA loan rates tend to be slightly higher than for conventional loans.
Fees: You pay an upfront guarantee fee equal to 1% of the loan amount and an annual fee equal to 0.35 percent of the loan amount. You don't pay PMI.
Loan terms: You may get fewer choices than for conventional loans. The most common term is 30 years.
Qualifying: You may qualify with a lower income than for conventional loans and your income must be within a limit determined by where you live. The home must be in an eligible rural area and meet USDA appraisal guidelines.
Pros and Cons
Pro: You likely don't need a down payment.
Cons: Your income cannot be above a certain limit and your home must be in an eligible rural area and pass the appraisal.
CHOOSING THE BEST MORTGAGE LENDER
We hope we've answered your question, “What type of home loans are there?” But if you still have questions about which exact home loan and term is best for you, the most important thing is to choose a lender you trust who can work with you to make sure you have an enjoyable home buying experience.
Click below to see how Fibre Federal Credit Union can serve your needs!
Please do not use this one inside of a tab, unless the tab is the first tab (being hidden on page load can cause issues with the slider's initial calculations.)
Aug 24, 2026
What Type of Home Loans Are There? Explore Your Options
Every family is different and all homes are different, which is why there's a range of mortgages to cater to different needs and wants. Whether you're a first-time buyer or a homeowner looking for a change— it can be confusing when navigating all your options.
Our quick guide can help you figure out what types of home loans are available and which one might be best for you.
AN OVERVIEW OF DIFFERENT MORTGAGE LOANS
We can split mortgages into two broad categories to help answer the question, “What type of home loans are there?” Government-backed home loans come with certain conditions and offer great benefits if you're eligible. For everyone else, a conventional loan is probably best.
Conventional Loans
These loans are offered by private lenders like credit unions, banks, and online mortgage brokers. They may be conforming (meet the guidelines of Fannie Mae and Freddie Mac) or non-conforming.
Fixed-rate home loans: Offer a steady interest rate over loan terms of 10, 15, 20, or 30 years for your primary residence.
Adjustable-rate mortgage (ARM) loans: Offer a low, fixed rate for an initial period and then adjust with market rates on a predetermined schedule.
Jumbo Loans: These non-conforming loans let you borrow higher loan amounts if you have the necessary down payment and meet other criteria.
Bare Land Loans: Help you buy land on which you plan to build a home (Build Land Loans) or empty land that you don't plan to develop (Raw Land Loans).
Vacation Home Loans: Give you the financing to buy a second property for vacation purposes.
Government-Backed Loans
These loans are partially insured by government departments so private lenders can offer loans to people who may not otherwise qualify, or offer better rates than the person might get for a conventional loan. The insurance covers the lender in case the borrower defaults.
FHA Loans: Insured by the Federal Housing Authority so more people may qualify for a home loan, as long as the property meets appraisal guidelines.
VA Loans: Insured by the U.S. Department of Veterans Affairs to provide competitive home loans to veterans and other eligible military personnel, with appraisal guidelines.
USDA Loans: Insured by the U.S. Department of Agriculture to help people buy a home in eligible rural areas, as long as their household income is below a certain limit.
FIXED-RATE MORTGAGE LOANS
A fixed-rate mortgage is a popular choice because you get to lock in a rate for the life of your loan, so your monthly payments remain steady which makes budgeting simple.
Key Details
Rates: The APR you get may be slightly higher than the initial rate for an adjustable-rate mortgage (ARM), but then your rate stays the same, while an ARM may go up and down.
Fees: You'll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: Choose from 10, 15, 20, or 30 years. Shorter terms get lower rates and accrue less total interest, while longer terms give lower monthly payments.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of a Fixed-Rate Mortgage
Pros: Budgeting is easy because your payments will remain steady apart from any changes to taxes and insurance.
Cons: Market rates may drop compared to what you lock in, so then you may need to refinance your mortgage to get a lower rate.
ADJUSTABLE-RATE MORTGAGE (ARM) LOANS
ARM home loans offer a low, fixed rate for an initial period that may be around 5 or 7 years which means you can enjoy lower payments at the start of your home loan. ARMs often suit people who plan to move, sell, or refinance in the short term.
Key Details
Rates: The APR you get for your initial period may be slightly lower than a fixed-rate loan, but then it will adjust with the markets and therefore could go higher or lower.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: ARMs offer a range of terms so be sure to read the fine print. There are caps on how much your rate can adjust the first time, each time, and in total over the life of your loan.
A 5/6 ARM means you get a fixed rate for 5 years, then it will adjust every 6 years until your loan is paid off in full.
A 7/6 ARM means you get a fixed rate for 7 years, then it adjusts every 6 years.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of an Adjustable-Rate Mortgage
Pros: You get lower payments at the start of your loan term and you may get a lower rate if market rates fall in the future.
Cons: Your rate may go up if market rates rise and your monthly payments may also go up and down over the life of your loan, so you need to plan for a possible increase.
JUMBO LOANS
A jumbo-loan is ideal if you want to buy a home that has a purchase price above the amount set by the Federal Housing Finance Agency (FHFA) each year.
Key Details
Rates: Jumbo loan rates are sometimes slightly higher than conforming loans but your rate will depend on your financial situation and chosen loan term.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is under 20%—though this may be the minimum down payment needed for a Jumbo Loan.
Loan terms: You may have fewer choices than for a conforming loan. For example, you may get the choice of a 15- or 30-year fixed-rate loan or a 10/1 ARM.
Qualifying: You may need very good credit, a significant down payment, and significant cash reserves to qualify.
Pros and Cons
Pro: You can buy a high-value home.
Cons: You need to have a large down payment and/or borrow a large loan amount so you should make sure you can comfortably afford the payments.
BARE LAND LOANS
A Build Land Loan is ideal if you have your eye on a nice piece of empty land or a vacant lot and you want to eventually build your home there. You might then get a construction loan and convert it to a regular home loan once your build is complete.
If you don't plan to develop the land, you can consider a Raw Land Loan.
Key Details
Rates: Land loan rates tend to be slightly higher than a mortgage for an existing home.
Fees: You don't need to pay private mortgage insurance (PMI).
Loan terms: You may get a term of 10 or 20 years.
Qualifying: As well as good credit and steady income, you may need to make a down payment of around 30% or as much as 50% for raw land.
Pros and Cons
Pros: You can buy the perfect spot for your future dream home.
Cons: You may need to prove you plan to build within a certain time frame and you may need a sizable down payment.
Build Land financing isn't available if the land can't be developed or doesn't perk.
Raw Land financing isn't available for commercial or industrial zoning.
VACATION HOME LOANS
You may qualify for a Vacation Home Loan if the property you want to buy is at least 50 miles from your primary residence and you don't plan to rent it out. Mortgages for primary homes, vacation homes, and rental or investment properties each have different rules.
Key Details
Rates: Rates for second homes may be slightly higher than for your first mortgage.
Fees: The standard down payment is 10% vs the typical 3%-5% for primary residences. PMI is needed for any purchase with less than 20% down.
Loan terms: Terms are available from 10, 15, 20, and 30 years.
Qualifying: You’ll need to show you have a debt-to-income (DTI) ratio that can carry two mortgages, you have great credit, a sufficient income, and a sizable down payment to get approved.
Pros and Cons
Pros: You can buy that alpine cottage or beach house to enjoy vacation time with the family.
Cons: You’ll need to manage two mortgages and use the property strictly as intended.
FHA LOANS
Federal Housing Administration (FHA) loans are designed to help more Americans become homeowners. You can be a first-time or repeat homebuyer as long as you meet the lending criteria and your home passes appraisal.
Key Details
Rates: FHA rates might be slightly higher than conventional homes.
Fees: You need to pay a Mortgage Insurance Premium (MIP) to help offset the risk of your loan. You might pay some MIP upfront, and some may get rolled into your APR.
Loan terms: You may get a choice of 15 or 30 years.
Qualifying: You may qualify with slightly lower credit and income levels compared to conventional loans and you need a down payment of just 3.5%.
Pros and Cons
Pros: FHA loans tend to offer easier qualifying criteria than conventional loans and lower down payments.
Cons: You need to buy a property that meets the appraisal guidelines, and this extra step sometimes means sellers prefer buyers with conventional loans.
VA LOANS
Veterans Affairs (VA) loans are available for eligible U.S. Veterans, active-duty service members, reservists, National Guard members, and surviving spouses. It's a lifetime benefit you can use to buy successive homes with no down payment needed. Your home needs to meet VA appraisal guidelines.
Key Details
Rates: VA loan rates tend to be slightly higher than for conventional loans.
Fees: You need to pay a VA funding fee (upfront or rolled into your APR) but you don't need to pay mortgage insurance.
Loan terms: You may get fewer or no choices compared to conventional loans. The most common term is 30 years.
Qualifying: You may qualify more easily than for conventional loans as long as you meet the eligibility criteria and minimum income and credit requirement, and pass the home appraisal.
Pros and Cons
Pros: You don't need a down payment and don't need to pay mortgage insurance.
Cons: You need to pay a VA funding fee and the property needs to go through the VA appraisal process. Because of this extra step, some sellers prefer buyers with conventional loans.
USDA LOANS
U.S. Department of Agriculture (USDA) Loans are available to people with moderate income who want to purchase a home in an eligible rural area. You may not need a down payment if you meet the other eligibility criteria.
Key Details
Rates: USDA loan rates tend to be slightly higher than for conventional loans.
Fees: You pay an upfront guarantee fee equal to 1% of the loan amount and an annual fee equal to 0.35 percent of the loan amount. You don't pay PMI.
Loan terms: You may get fewer choices than for conventional loans. The most common term is 30 years.
Qualifying: You may qualify with a lower income than for conventional loans and your income must be within a limit determined by where you live. The home must be in an eligible rural area and meet USDA appraisal guidelines.
Pros and Cons
Pro: You likely don't need a down payment.
Cons: Your income cannot be above a certain limit and your home must be in an eligible rural area and pass the appraisal.
CHOOSING THE BEST MORTGAGE LENDER
We hope we've answered your question, “What type of home loans are there?” But if you still have questions about which exact home loan and term is best for you, the most important thing is to choose a lender you trust who can work with you to make sure you have an enjoyable home buying experience.
Click below to see how Fibre Federal Credit Union can serve your needs!
The list content type is an easy and convenient way to create and sort lists of simple FAQs and similar content. List Items display like layout accordions.
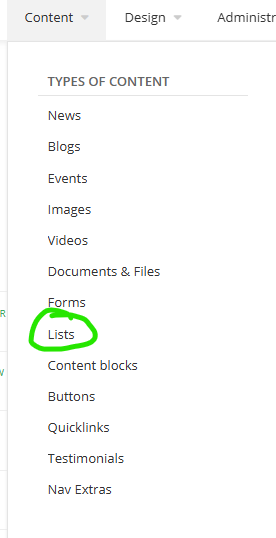
Lists can be created under Content - > Lists.
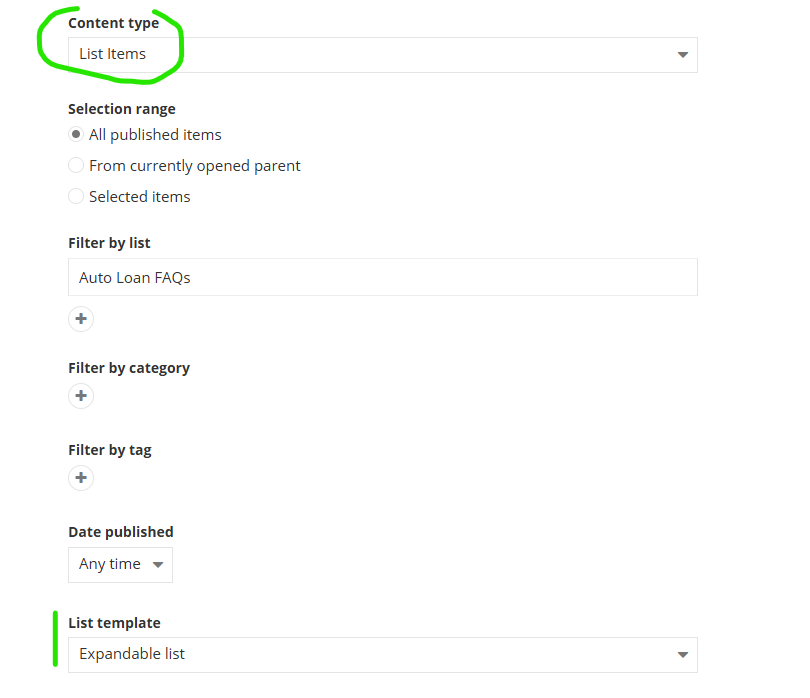
To show list items, select Content type : Lists. It can then be filtered by parent list. List items can also be manually selected if needed.
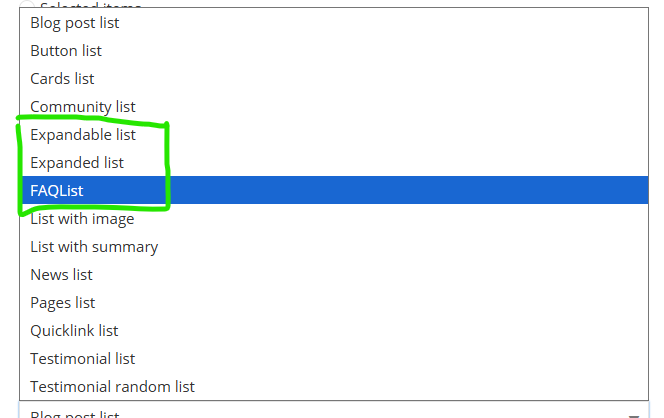
Set the template to either Expandable List, Expanded List, or FAQ list. FAQ list comes pre-programmed with SEO relevant to FAQs.
For all list templates, Style 1 is basic, Style 2 adds an expand all button, and Style 3 is a double column. With the FAQ list template, a title is automatically added at the top, which can be customized through the Title field in the widget's edit panel if needed. The other list templates only create the title if it is explicitly provided in this field.
Can I finance with Fibre Federal & TLC at the dealership?
Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.
Can I get help with starting my auto loan application?
Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.
Can you help me find a new car?
Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.
What benefits can I expect from a Fibre Federal & TLC auto loan?
We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.
What is the Drive4Less loan?
Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.
Can I finance with Fibre Federal & TLC at the dealership?
Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.
Can I get help with starting my auto loan application?
Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.
Can you help me find a new car?
Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.
What benefits can I expect from a Fibre Federal & TLC auto loan?
We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.
What is the Drive4Less loan?
Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.
Can I finance with Fibre Federal & TLC at the dealership?
Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.
Can I get help with starting my auto loan application?
Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.
Can you help me find a new car?
Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.
What benefits can I expect from a Fibre Federal & TLC auto loan?
We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.
What is the Drive4Less loan?
Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.
Can I finance with Fibre Federal & TLC at the dealership?
Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.
Can I get help with starting my auto loan application?
Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.
Can you help me find a new car?
Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.
What benefits can I expect from a Fibre Federal & TLC auto loan?
We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.
What is the Drive4Less loan?
Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.
Frequently Asked Questions
Can I finance with Fibre Federal & TLC at the dealership?
Yes! In many cases, there's no need to go back and forth between the dealer and a lender to buy a car. We make it easy with Credit Union Direct Lending (CUDL)! We work directly with many local dealerships, so you can get your loan through us right on-site when you find your perfect car.
Can I get help with starting my auto loan application?
Applying for a loan can feel easier when you’ve got someone by your side—or on-screen—to guide you through it. That’s why we now offer live, one-on-one video appointments for consumer loans. A loan officer will walk you through the process step by step and answer your questions, so you feel confident from start to finish. Schedule an appointment here.
Can you help me find a new car?
Absolutely! We have a robust vehicle search tool that lets you search for your ideal make and model, compare prices, take virtual test drives, and contact dealers directly.
What benefits can I expect from a Fibre Federal & TLC auto loan?
We practice Rate Equality, so every qualified member gets the same great low rate. Enjoy flexible terms up to 84 months, choose from a variety of insurance and protection options, get access to CARFAX reports, and more auto loan benefits.
What is the Drive4Less loan?
Our Drive4Less loan offers low monthly payments like a lease, with fewer restrictions. Plus, you’d own the vehicle with full flexibility and all the benefits of ownership.
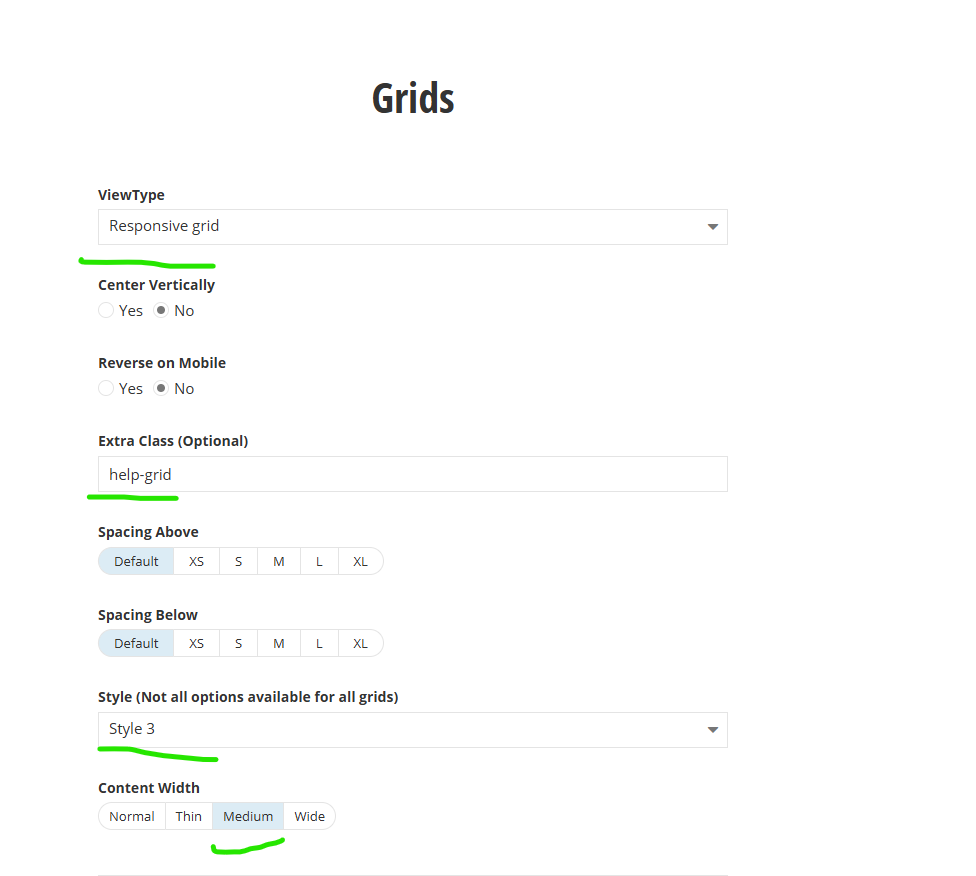
Drop a grid. set the template to Responsive Grid and the style to "Style 3". Set the width to "Medium". Add the class "help-grid". The width setting is optional, the others are important. Technically, for a 3-wide help grid, Style 1 and "wide" width could be used.
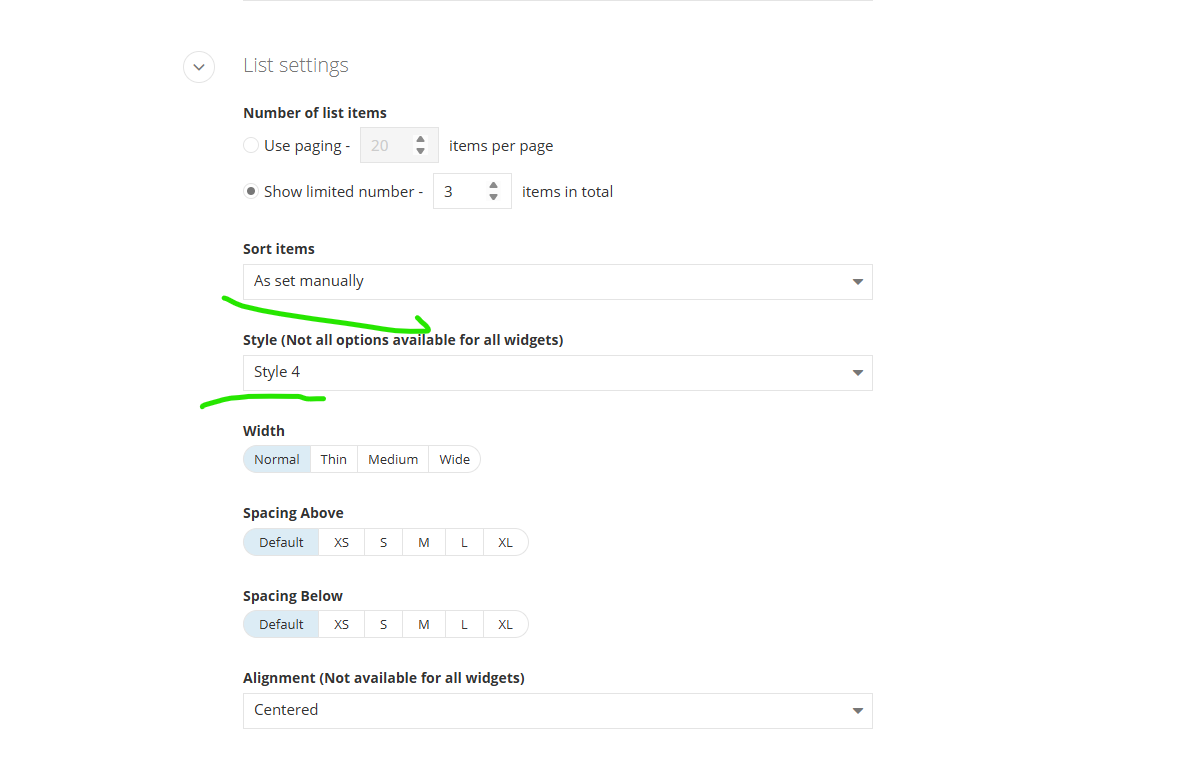
Drop FAQs. Select three. Set the Style to Style 4.
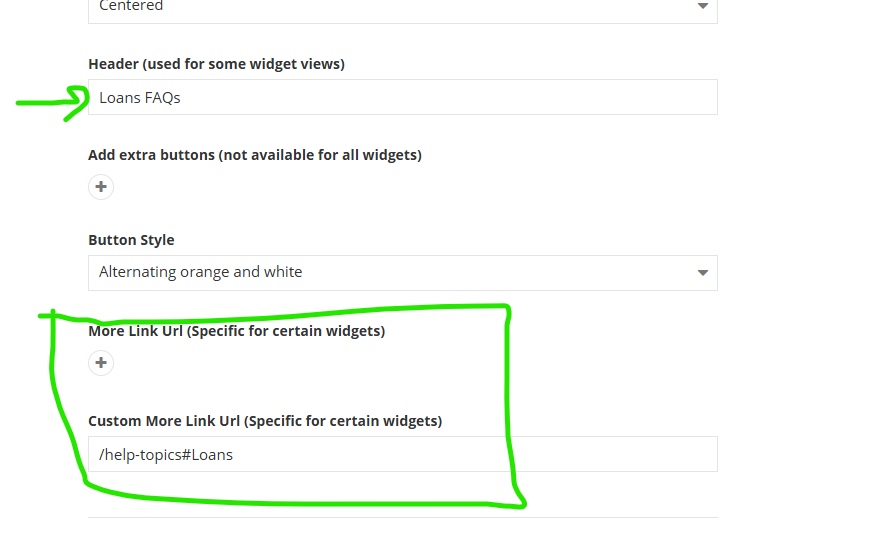
Each FAQ group's title and link are added through the Header and the two More Link fields under "List Settings". The first link allows selection of pages, the second is for pasting an url -- useful when linking to an anchor. If available, a page link will always take precedence over the custom link, so if using a custom link, ensure that More Link Url doesn't have a page selected.
Loans FAQs
How do I prevent fraud on my account?
Being proactive about fraud and scam situations is essential! You can find helpful tips and tricks for stopping fraud before it happens on our Fraud Prevention page.
What can I do if I am a fraud victim?
If you’ve provided sensitive account information to a scammer, contact us right away to help secure your accounts. If you believe you’ve become a victim of identity theft, refer to the Federal Trade Commission’s information about Identity Theft: What To Know – What To Do.
Despite the name, quicklinks should be considered as "quicklinks and features" because it also can be used to add icon-title-summary sets to pages. These can have a link but do not need to. They can be displayed either through the "Quicklinks group" widget (discussed later) or the Content List widget.
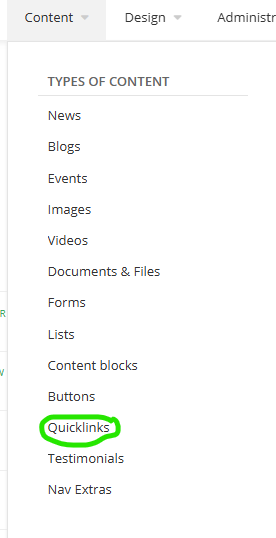
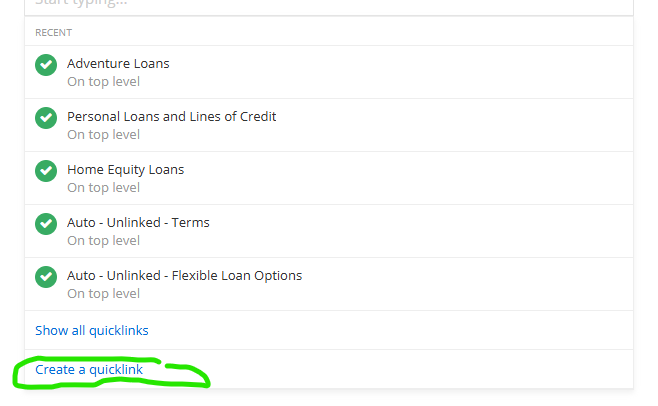
Quicklinks can be created either under Content -> Quicklinks
Or when selecting quicklinks to add to the list
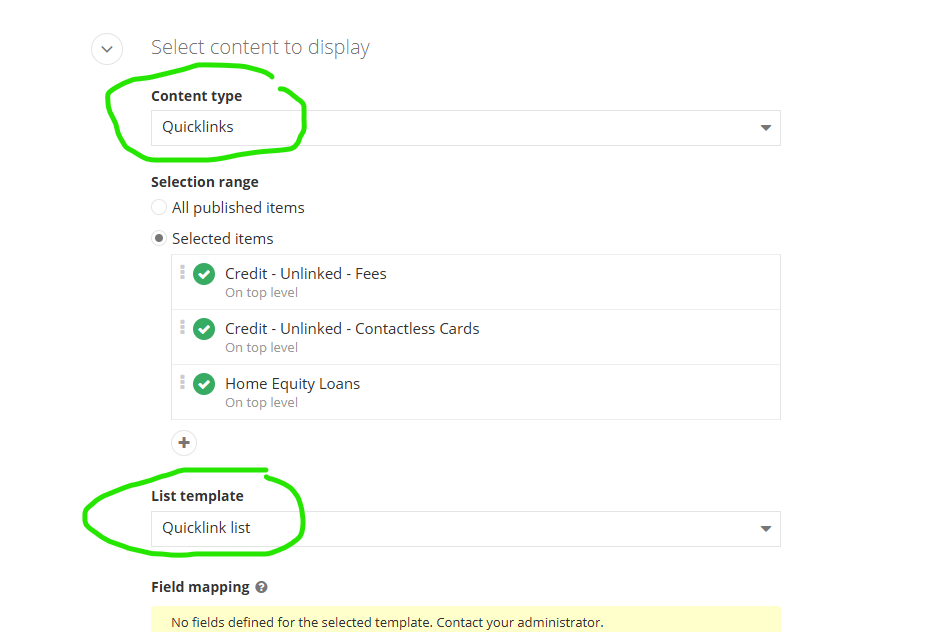
Quicklinks can be displayed through the Content List widget by setting the Content type to "Quicklinks" and the list to "Quicklink List"
Further styles can be added to the Content List for Quicklinks if needed--for now, only one exists.
Paying off credit card debt can come with a lot of stress, but it doesn't have to. When you're a Visa® Classic Credit Card holder, you can enjoy a non-variable annual percentage rate of just {{RATE}}* - much lower than the 30.5% average rate on a bank credit card.**
Competitive Rates
Paying off credit card debt can come with a lot of stress, but it doesn't have to. When you're a Visa® Platinum Credit Card holder, you get a special low introductory rate of 1.9% APR* on purchases and balance transfers for the first six billing cycles. After that, you'll enjoy a competitive {{RATE}}APR* - much lower than the 30.5% average rate on a bank credit card.**
Higher Balance, Lower Rate
Enjoy a higher limit than our Visa Classic Card with a low rate to go with it!
Home Equity Limited Draw Line of Credit
This fixed rate secured loan provides a lump sum amount with regular monthly payments. This is a good choice for consolidating your debts, purchasing big ticket items, or taking that dream vacation.
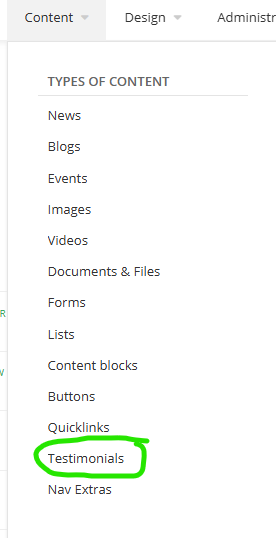
Testimonials can be created under Content -> Testimonials
Or when selecting testimonials in the content list widget.
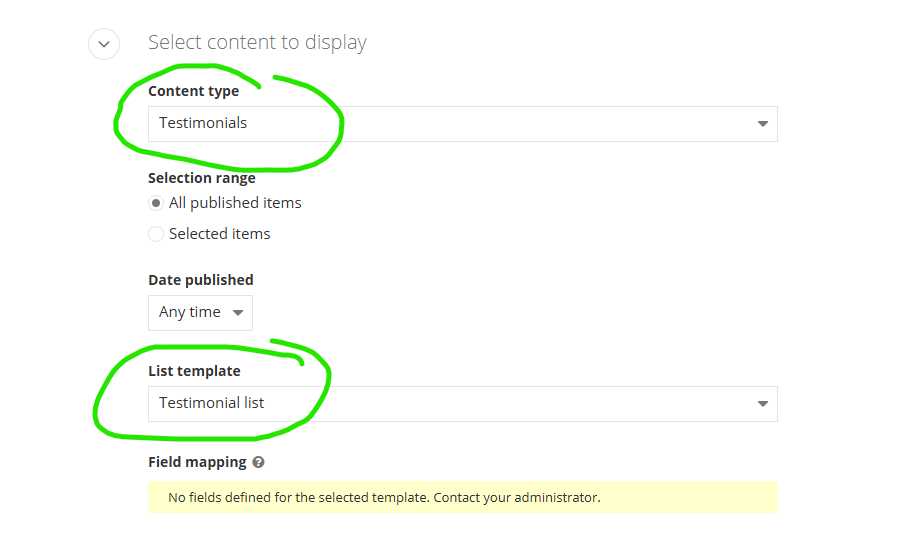
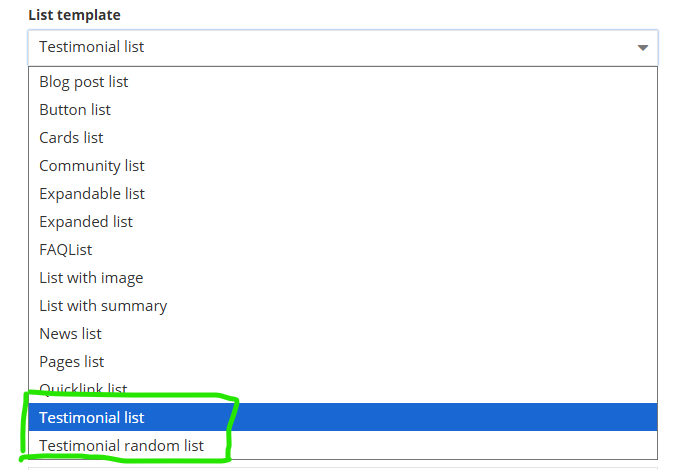
They can be shown using the content list widget with the Content type set to Testimonials and the template set to Testimonial List or Testimonial Random List.
Testimonials have two templates: "Testimonial List" and "Testimonial Random List".
Testimonial list shows all selected testimonials, either as a list or slider.
Style 1 is a basic list. Style 2 is a simple slider. Style 3 is the same slider, but with additional styling and a title/button area.
My friends, family and I do all of our banking at Fibre Federal because they consistently provide such good service. Their employees and branches are so professional, and the staff is so helpful that I don't want to go to any other bank.
Maddie W., Longview, WA
It was reported to me by a life insurance company that they had a data breach and my banking information was stolen. The thief tried to charge my card, but Fibre saw the charge as suspicious and declined the charge. Thank you, Fibre Federal Credit Union, for having my back. I have a tight budget and losing any amount of my money could be devastating to me and my family.
Cherilynn
I am very satisfied with my
experience, especially due to the fact it was my first time using the text
feature. The agent I talked to was very professional, answered all of my
questions, operated in timely fashion, and left me with a good first impression.
I will be using this again because of her.
Brad O.
I used the chat feature in
the Fibre Federal Credit Union app to resolve a problem with funds in one of our accounts and I
couldn’t be happier with the experience. I work in a loud environment where
phone calls aren’t always the best option for contacting people, so having the
ability to chat with someone is a great option I think all banking institutions
should implement.
Trevor N.
I would like to start off by saying that I really appreciate all the ways available to communicate with tellers: they have an online chat, call, video call, and online assistant to help with basic things. Whenever I interact with the tellers, they are kind and intelligent. I have always been able to fix the issues I come across with this credit union!
Tabatha B.
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Carolena Q.
I love being a part of the Fibre Family! Everyone is always so kind and helpful
and I really appreciate the drive up ITM with virtual help!
Melissa T.
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.
Shantelle
The loan department at Fibre CU was extremely helpful with our needs and were quick to communicate and help solve any concerns we had. Would recommend Fibre CU and their helpful staff!
Rolly B.
Great customer service! I accidentally made a
loan payment 2x and instead of telling me, ‘Sorry, Charlie,' as I expected, they
reversed it right away no questions asked! Never had a bad experience with
them. Great job all.
Danielle
The first loan I got was for a pickup, then I had an RV, and now I have a boat loan. Each loan was simple and went through so good that I’ve come back to deal with Kim every time. That was the quality that made me decide to switch to Fibre Federal.
Kelly
They’ve never wanted to push me into any kind of direction as far as loans. We sit down, they tell you the truth [and] the right path to go.
Mark
We have both personal and business accounts with Fibre, and have only good things to say! The staff is extremely helpful and friendly, especially in the business aspect of things. We couldn't ask for a better credit union!
Bryce B.
Fibre FCU has been a shining light for our business. We are always met
with professionalism and know they care about us and the business we have
brought to the Longview community. Thank you, thank you FibreFCU. We look
forward to another great year.
Martha S.
I have been with them for both personal and
business accounts. I find their checking to be great (online is easy to use)
and their Choice Checking account pays some of the best rates on my balance.
Visa account has some of the lowest interest rates available.
David L.
Very helpful and informative. All my questions were answered to the fullest and everything was made crystal clear in reference to opening my accounts.
Jordan M.
Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.
They are always friendly, fast, and always helpful with anything you need. I come here for all my banking needs and always leave feeling appreciated. This place is absolutely amazing.
Lisa W.
Best financial institution
I have ever used! Super friendly, helpful staff members who give excellent
service and are very knowledgeable about their products and services. I love
how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
Fibre Federal have been my backbone in every
time of need. They have been my credit union now for nearly 10 years and I
would not have it any other way! Thank you to Fibre Federal for always being
amazing and going above and beyond for your members even if we aren't on top of
the game ourselves!
Holly
My friends, family and I do all of our banking at Fibre Federal because they consistently provide such good service. Their employees and branches are so professional, and the staff is so helpful that I don't want to go to any other bank.
Maddie W., Longview, WA
The first loan I got was for a pickup, then I had an RV, and now I have a boat loan. Each loan was simple and went through so good that I’ve come back to deal with Kim every time. That was the quality that made me decide to switch to Fibre Federal.
Kelly
I used the chat feature in
the Fibre Federal Credit Union app to resolve a problem with funds in one of our accounts and I
couldn’t be happier with the experience. I work in a loud environment where
phone calls aren’t always the best option for contacting people, so having the
ability to chat with someone is a great option I think all banking institutions
should implement.
Trevor N.
I am very satisfied with my
experience, especially due to the fact it was my first time using the text
feature. The agent I talked to was very professional, answered all of my
questions, operated in timely fashion, and left me with a good first impression.
I will be using this again because of her.
Brad O.
I have been with them for both personal and
business accounts. I find their checking to be great (online is easy to use)
and their Choice Checking account pays some of the best rates on my balance.
Visa account has some of the lowest interest rates available.
David L.
They are always friendly, fast, and always helpful with anything you need. I come here for all my banking needs and always leave feeling appreciated. This place is absolutely amazing.
Lisa W.
Fibre FCU has been a shining light for our business. We are always met
with professionalism and know they care about us and the business we have
brought to the Longview community. Thank you, thank you FibreFCU. We look
forward to another great year.
Martha S.
Best financial institution
I have ever used! Super friendly, helpful staff members who give excellent
service and are very knowledgeable about their products and services. I love
how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
Fibre Federal have been my backbone in every
time of need. They have been my credit union now for nearly 10 years and I
would not have it any other way! Thank you to Fibre Federal for always being
amazing and going above and beyond for your members even if we aren't on top of
the game ourselves!
Holly
We have both personal and business accounts with Fibre, and have only good things to say! The staff is extremely helpful and friendly, especially in the business aspect of things. We couldn't ask for a better credit union!
Bryce B.
It was reported to me by a life insurance company that they had a data breach and my banking information was stolen. The thief tried to charge my card, but Fibre saw the charge as suspicious and declined the charge. Thank you, Fibre Federal Credit Union, for having my back. I have a tight budget and losing any amount of my money could be devastating to me and my family.
Cherilynn
They’ve never wanted to push me into any kind of direction as far as loans. We sit down, they tell you the truth [and] the right path to go.
Mark
Great customer service! I accidentally made a
loan payment 2x and instead of telling me, ‘Sorry, Charlie,' as I expected, they
reversed it right away no questions asked! Never had a bad experience with
them. Great job all.
Danielle
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.
Shantelle
Very helpful and informative. All my questions were answered to the fullest and everything was made crystal clear in reference to opening my accounts.
Jordan M.
The loan department at Fibre CU was extremely helpful with our needs and were quick to communicate and help solve any concerns we had. Would recommend Fibre CU and their helpful staff!
Rolly B.
I would like to start off by saying that I really appreciate all the ways available to communicate with tellers: they have an online chat, call, video call, and online assistant to help with basic things. Whenever I interact with the tellers, they are kind and intelligent. I have always been able to fix the issues I come across with this credit union!
Tabatha B.
I love being a part of the Fibre Family! Everyone is always so kind and helpful
and I really appreciate the drive up ITM with virtual help!
Melissa T.
Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Carolena Q.
Customizable buttons Customizable Title
Great Service deserves to be celebrated. Tell us about the experience that made a difference for you!
I used the chat feature in
the Fibre Federal Credit Union app to resolve a problem with funds in one of our accounts and I
couldn’t be happier with the experience. I work in a loud environment where
phone calls aren’t always the best option for contacting people, so having the
ability to chat with someone is a great option I think all banking institutions
should implement.
Trevor N.
The first loan I got was for a pickup, then I had an RV, and now I have a boat loan. Each loan was simple and went through so good that I’ve come back to deal with Kim every time. That was the quality that made me decide to switch to Fibre Federal.
Kelly
We have both personal and business accounts with Fibre, and have only good things to say! The staff is extremely helpful and friendly, especially in the business aspect of things. We couldn't ask for a better credit union!
Bryce B.
I love being a part of the Fibre Family! Everyone is always so kind and helpful
and I really appreciate the drive up ITM with virtual help!
Melissa T.
The loan department at Fibre CU was extremely helpful with our needs and were quick to communicate and help solve any concerns we had. Would recommend Fibre CU and their helpful staff!
Rolly B.
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Carolena Q.
Great customer service! I accidentally made a
loan payment 2x and instead of telling me, ‘Sorry, Charlie,' as I expected, they
reversed it right away no questions asked! Never had a bad experience with
them. Great job all.
Danielle
My friends, family and I do all of our banking at Fibre Federal because they consistently provide such good service. Their employees and branches are so professional, and the staff is so helpful that I don't want to go to any other bank.
Maddie W., Longview, WA
I have been with them for both personal and
business accounts. I find their checking to be great (online is easy to use)
and their Choice Checking account pays some of the best rates on my balance.
Visa account has some of the lowest interest rates available.
David L.
They’ve never wanted to push me into any kind of direction as far as loans. We sit down, they tell you the truth [and] the right path to go.
Mark
I would like to start off by saying that I really appreciate all the ways available to communicate with tellers: they have an online chat, call, video call, and online assistant to help with basic things. Whenever I interact with the tellers, they are kind and intelligent. I have always been able to fix the issues I come across with this credit union!
Tabatha B.
Very helpful and informative. All my questions were answered to the fullest and everything was made crystal clear in reference to opening my accounts.
Jordan M.
They are always friendly, fast, and always helpful with anything you need. I come here for all my banking needs and always leave feeling appreciated. This place is absolutely amazing.
Lisa W.
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.
Shantelle
Some of the best customer service I've ever experienced. Fun, genuine people who want to get to know you and have an uplifting attitude. When I ask a question, they know exactly how to fix whatever I need. Super helpful people who are passionate about that they do. 5/5 stars!
Josiah D.
I am very satisfied with my
experience, especially due to the fact it was my first time using the text
feature. The agent I talked to was very professional, answered all of my
questions, operated in timely fashion, and left me with a good first impression.
I will be using this again because of her.
Brad O.
Fibre Federal have been my backbone in every
time of need. They have been my credit union now for nearly 10 years and I
would not have it any other way! Thank you to Fibre Federal for always being
amazing and going above and beyond for your members even if we aren't on top of
the game ourselves!
Holly
Fibre FCU has been a shining light for our business. We are always met
with professionalism and know they care about us and the business we have
brought to the Longview community. Thank you, thank you FibreFCU. We look
forward to another great year.
Martha S.
It was reported to me by a life insurance company that they had a data breach and my banking information was stolen. The thief tried to charge my card, but Fibre saw the charge as suspicious and declined the charge. Thank you, Fibre Federal Credit Union, for having my back. I have a tight budget and losing any amount of my money could be devastating to me and my family.
Cherilynn
Best financial institution
I have ever used! Super friendly, helpful staff members who give excellent
service and are very knowledgeable about their products and services. I love
how easy it is to talk to a person or get assistance when needed.
Geoffrey P.
Testimonial Random list shows a random single testimonial from those selected.
Style 1 is a designed element. Style 2 is a simple presentation that can be dropped inside any section.
The title is customizable too.
Fibre Federal have been my backbone in every
time of need. They have been my credit union now for nearly 10 years and I
would not have it any other way! Thank you to Fibre Federal for always being
amazing and going above and beyond for your members even if we aren't on top of
the game ourselves!
Holly
Real Words, Real People from the PNW
Love the Virtual Reps at the ITM. Makes my banking feel more personal even for a simple transaction.
Is a widget implemented to showcase numbers. Currently, the only style is the one shown on the homepage. It was set up as a widget so that the numbers can be easily changed at any time. It can be extended with more styles if needed for landing pages or promotionals (Contact your LKCS sales rep.)
$1,000Featured dollars.
500This is a test number.
Quicklinks Group
This was set up to allow a group of quicklinks with a title and image to be showcased. The title of the main template defaults to "Other Members Also Liked" but can be customized. It can also be used to generate a list of features with the same special styling if quicklinks without links are selected.
It can be extended with more templates as needed.
Customizable title
Skip the Fees
No annual fee, no balance transfer fee, no cash advance fee, plus a 30-day grace period.
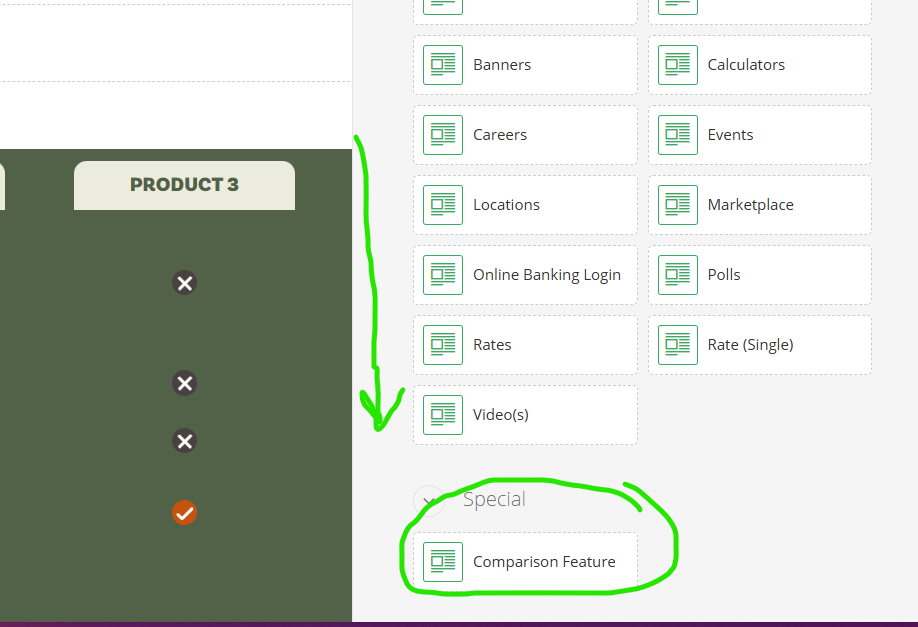
Use the Comparison Feature to compare items If too many items are provided, the widget will provide a slider as a fallback to prevent the widget styles from breaking.
Row titles are optional To show all at once, a new design would need to be made.
These were created later and do not have a full guide.
August 30, 2013
Received NCUA's Low-Income Designation (LDI), which extends the credit union's resources, funding, and flexibility to better serve people with limited incomes.
August 8, 2025
Designated a Juntos Avanzamos credit union, recognizing our commitment to empowering Hispanic and immigrant communities and supporting financial well-being for all.
August 24, 2022
Field of Membership
expansion into Clark, Grays Harbor, Lewis, and Skamania Counties in Washington.
May 1, 2015
Acquired TLC Federal Credit
Union, expanding the branch network and Field of Membership into Tillamook and
Lincoln Counties, along the Oregon Coast.
June 13, 2013
Field of Membership
expansion into Pacific County in Washington.
September 24, 2012
Field of Membership
expansion into Columbia and Clatsop Counties in Oregon, and Wahkiakum County in
Washington.
January 1, 2008
Merged with 1st Citizens
Federal Credit Union in Longview, WA.
January 1, 1982
Merged with International
Paper Company (IPCO) Federal Credit Union in Longview, WA.
September 1975
Fibre Federal changed to a
community charter, allowing non-Fibre mill workers and their families in
Cowlitz County to become members.
1971
Main Office branch opened
(and is still in use to this day!).
1937
Sixty-three employees of
Longview Fibre Company pooled together $315 and founded Fibre Federal Credit
Union.
Anchor: richTextHtml
Accessing the HTML view in the Rich Text Editor
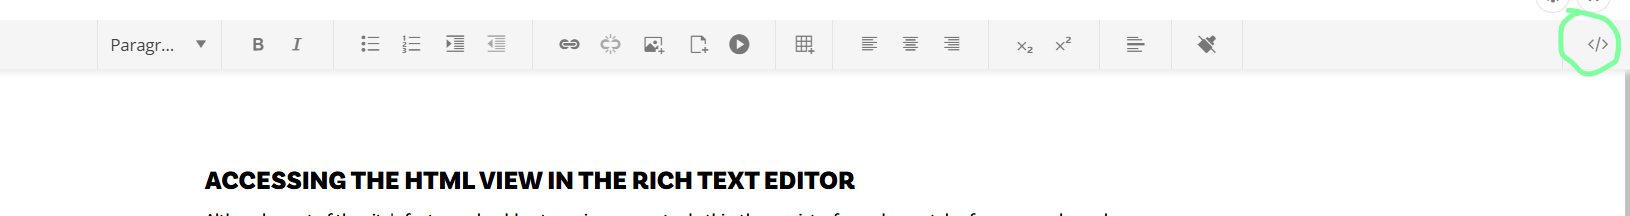
Although most of the site's features should not require anyone to do this, there exist a few column styles for paragraphs and lists and some other special features that could not be added to the sitefinity editor naturally. Additionally, this view can be used to clean up or double check code when needed. To access the html view, click somewhere in the text box and then select the </> in the top right corner. (If the </> isn't visible, the window may need to be made larger.)
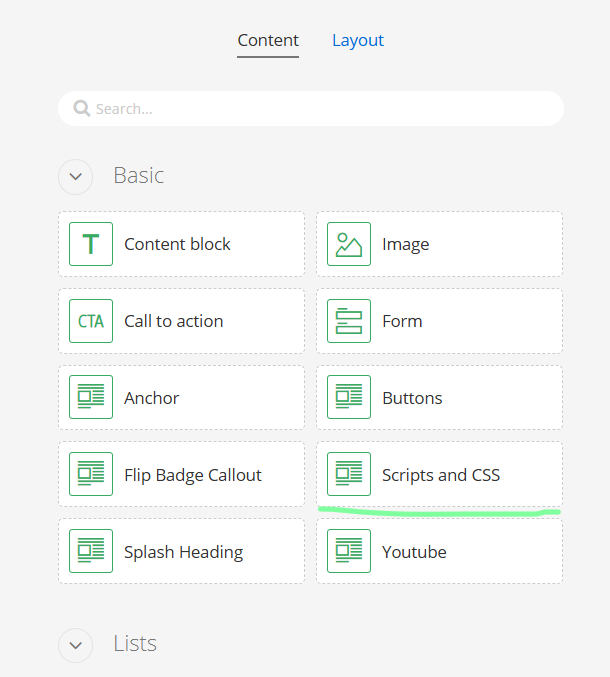
This view should not be used to add iframes, embed codes, etc. Those may get "cleansed" by the rich text editor's code cleaner. For embeds, please use the scripts and css widget instead.
Multi-column paragraphs
In order to avoid having to use the html view at all, these starter templates can just be copied where desired to preserve the relevant styling. To make a list or paragraph that already exists contain columns, tab to the html view and add class="cols-2" or class="cols-3" to the paragraph or list. A paragraph with cols-2 code looks like this, as an example of placement for the class:
<p class="cols-2">Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut
aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.</p>
And a list looks like this:
<ul class="cols-2">
<li>List item 1</li>
<li>List item 2</li>
<li>List Item 3</li>
<li>List item 4</li>
</ul>
For lists, the class check-list can also be added to unordered lists to invoke special styling, with examples below:
<ul class="check-list ">
<li>List item 1</li>
<li>List item 2</li>
<li>List Item 3</li>
<li>List item 4</li>
</ul>
Renders as :
List item 1
List item 2
List Item 3
List item 4
With columns, the check list's code looks like:
<ul class="check-list cols-2">
<li>List item 1</li>
<li>List item 2</li>
<li>List Item 3</li>
<li>List item 4</li>
</ul>
cols-2
Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut
aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
cols-3
Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut
aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Multi-column lists
cols-2
List item 1
List item 2
List Item 3
List item 4
List item 1
List item 2
List Item 3
List item 4
List item 1
List item 2
List Item 3
List item 4
cols-3
List item 1
List item 2
List Item 3
List item 4
List Item 5
List item 6
List item 1
List item 2
List Item 3
List item 4
List Item 5
List item 6
List item 1
List item 2
List Item 3
List item 4
List Item 5
List item 6
Examples of interactions with dark backgrounds
Style Guide
This page is a guide to the text and widget styles available on the site.
Text Styles
H2 Title
H3 Title
H4 Title
H5 Title
H6 Title
Paragraph Copy Lorem Ipsum
Two column paragraph copy Lorem Ipsum Dolor ist amet Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut
aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Every family is different and all homes are different, which is why there's a range of mortgages to cater to different needs and wants. Whether you're a first-time buyer or a homeowner looking for a change— it can be confusing when navigating all your options.
Our quick guide can help you figure out what types of home loans are available and which one might be best for you.
AN OVERVIEW OF DIFFERENT MORTGAGE LOANS
We can split mortgages into two broad categories to help answer the question, “What type of home loans are there?” Government-backed home loans come with certain conditions and offer great benefits if you're eligible. For everyone else, a conventional loan is probably best.
Conventional Loans
These loans are offered by private lenders like credit unions, banks, and online mortgage brokers. They may be conforming (meet the guidelines of Fannie Mae and Freddie Mac) or non-conforming.
Fixed-rate home loans: Offer a steady interest rate over loan terms of 10, 15, 20, or 30 years for your primary residence.
Adjustable-rate mortgage (ARM) loans: Offer a low, fixed rate for an initial period and then adjust with market rates on a predetermined schedule.
Jumbo Loans: These non-conforming loans let you borrow higher loan amounts if you have the necessary down payment and meet other criteria.
Bare Land Loans: Help you buy land on which you plan to build a home (Build Land Loans) or empty land that you don't plan to develop (Raw Land Loans).
Vacation Home Loans: Give you the financing to buy a second property for vacation purposes.
Government-Backed Loans
These loans are partially insured by government departments so private lenders can offer loans to people who may not otherwise qualify, or offer better rates than the person might get for a conventional loan. The insurance covers the lender in case the borrower defaults.
FHA Loans: Insured by the Federal Housing Authority so more people may qualify for a home loan, as long as the property meets appraisal guidelines.
VA Loans: Insured by the U.S. Department of Veterans Affairs to provide competitive home loans to veterans and other eligible military personnel, with appraisal guidelines.
USDA Loans: Insured by the U.S. Department of Agriculture to help people buy a home in eligible rural areas, as long as their household income is below a certain limit.
FIXED-RATE MORTGAGE LOANS
A fixed-rate mortgage is a popular choice because you get to lock in a rate for the life of your loan, so your monthly payments remain steady which makes budgeting simple.
Key Details
Rates: The APR you get may be slightly higher than the initial rate for an adjustable-rate mortgage (ARM), but then your rate stays the same, while an ARM may go up and down.
Fees: You'll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: Choose from 10, 15, 20, or 30 years. Shorter terms get lower rates and accrue less total interest, while longer terms give lower monthly payments.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of a Fixed-Rate Mortgage
Pros: Budgeting is easy because your payments will remain steady apart from any changes to taxes and insurance.
Cons: Market rates may drop compared to what you lock in, so then you may need to refinance your mortgage to get a lower rate.
ADJUSTABLE-RATE MORTGAGE (ARM) LOANS
ARM home loans offer a low, fixed rate for an initial period that may be around 5 or 7 years which means you can enjoy lower payments at the start of your home loan. ARMs often suit people who plan to move, sell, or refinance in the short term.
Key Details
Rates: The APR you get for your initial period may be slightly lower than a fixed-rate loan, but then it will adjust with the markets and therefore could go higher or lower.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is less than 20%.
Loan terms: ARMs offer a range of terms so be sure to read the fine print. There are caps on how much your rate can adjust the first time, each time, and in total over the life of your loan.
A 5/6 ARM means you get a fixed rate for 5 years, then it will adjust every 6 years until your loan is paid off in full.
A 7/6 ARM means you get a fixed rate for 7 years, then it adjusts every 6 years.
Qualifying: You'll need good credit, a steady income, and a down payment to qualify.
Pros and Cons of an Adjustable-Rate Mortgage
Pros: You get lower payments at the start of your loan term and you may get a lower rate if market rates fall in the future.
Cons: Your rate may go up if market rates rise and your monthly payments may also go up and down over the life of your loan, so you need to plan for a possible increase.
JUMBO LOANS
A jumbo-loan is ideal if you want to buy a home that has a purchase price above the amount set by the Federal Housing Finance Agency (FHFA) each year.
Key Details
Rates: Jumbo loan rates are sometimes slightly higher than conforming loans but your rate will depend on your financial situation and chosen loan term.
Fees: You’ll need to pay private mortgage insurance (PMI) if your down payment is under 20%—though this may be the minimum down payment needed for a Jumbo Loan.
Loan terms: You may have fewer choices than for a conforming loan. For example, you may get the choice of a 15- or 30-year fixed-rate loan or a 10/1 ARM.
Qualifying: You may need very good credit, a significant down payment, and significant cash reserves to qualify.
Pros and Cons
Pro: You can buy a high-value home.
Cons: You need to have a large down payment and/or borrow a large loan amount so you should make sure you can comfortably afford the payments.
BARE LAND LOANS
A Build Land Loan is ideal if you have your eye on a nice piece of empty land or a vacant lot and you want to eventually build your home there. You might then get a construction loan and convert it to a regular home loan once your build is complete.
If you don't plan to develop the land, you can consider a Raw Land Loan.
Key Details
Rates: Land loan rates tend to be slightly higher than a mortgage for an existing home.
Fees: You don't need to pay private mortgage insurance (PMI).
Loan terms: You may get a term of 10 or 20 years.
Qualifying: As well as good credit and steady income, you may need to make a down payment of around 30% or as much as 50% for raw land.
Pros and Cons
Pros: You can buy the perfect spot for your future dream home.
Cons: You may need to prove you plan to build within a certain time frame and you may need a sizable down payment.
Build Land financing isn't available if the land can't be developed or doesn't perk.
Raw Land financing isn't available for commercial or industrial zoning.
VACATION HOME LOANS
You may qualify for a Vacation Home Loan if the property you want to buy is at least 50 miles from your primary residence and you don't plan to rent it out. Mortgages for primary homes, vacation homes, and rental or investment properties each have different rules.
Key Details
Rates: Rates for second homes may be slightly higher than for your first mortgage.
Fees: The standard down payment is 10% vs the typical 3%-5% for primary residences. PMI is needed for any purchase with less than 20% down.
Loan terms: Terms are available from 10, 15, 20, and 30 years.
Qualifying: You’ll need to show you have a debt-to-income (DTI) ratio that can carry two mortgages, you have great credit, a sufficient income, and a sizable down payment to get approved.
Pros and Cons
Pros: You can buy that alpine cottage or beach house to enjoy vacation time with the family.
Cons: You’ll need to manage two mortgages and use the property strictly as intended.
FHA LOANS
Federal Housing Administration (FHA) loans are designed to help more Americans become homeowners. You can be a first-time or repeat homebuyer as long as you meet the lending criteria and your home passes appraisal.
Key Details
Rates: FHA rates might be slightly higher than conventional homes.
Fees: You need to pay a Mortgage Insurance Premium (MIP) to help offset the risk of your loan. You might pay some MIP upfront, and some may get rolled into your APR.
Loan terms: You may get a choice of 15 or 30 years.
Qualifying: You may qualify with slightly lower credit and income levels compared to conventional loans and you need a down payment of just 3.5%.
Pros and Cons
Pros: FHA loans tend to offer easier qualifying criteria than conventional loans and lower down payments.
Cons: You need to buy a property that meets the appraisal guidelines, and this extra step sometimes means sellers prefer buyers with conventional loans.
VA LOANS
Veterans Affairs (VA) loans are available for eligible U.S. Veterans, active-duty service members, reservists, National Guard members, and surviving spouses. It's a lifetime benefit you can use to buy successive homes with no down payment needed. Your home needs to meet VA appraisal guidelines.
Key Details
Rates: VA loan rates tend to be slightly higher than for conventional loans.
Fees: You need to pay a VA funding fee (upfront or rolled into your APR) but you don't need to pay mortgage insurance.
Loan terms: You may get fewer or no choices compared to conventional loans. The most common term is 30 years.
Qualifying: You may qualify more easily than for conventional loans as long as you meet the eligibility criteria and minimum income and credit requirement, and pass the home appraisal.
Pros and Cons
Pros: You don't need a down payment and don't need to pay mortgage insurance.
Cons: You need to pay a VA funding fee and the property needs to go through the VA appraisal process. Because of this extra step, some sellers prefer buyers with conventional loans.
USDA LOANS
U.S. Department of Agriculture (USDA) Loans are available to people with moderate income who want to purchase a home in an eligible rural area. You may not need a down payment if you meet the other eligibility criteria.
Key Details
Rates: USDA loan rates tend to be slightly higher than for conventional loans.
Fees: You pay an upfront guarantee fee equal to 1% of the loan amount and an annual fee equal to 0.35 percent of the loan amount. You don't pay PMI.
Loan terms: You may get fewer choices than for conventional loans. The most common term is 30 years.
Qualifying: You may qualify with a lower income than for conventional loans and your income must be within a limit determined by where you live. The home must be in an eligible rural area and meet USDA appraisal guidelines.
Pros and Cons
Pro: You likely don't need a down payment.
Cons: Your income cannot be above a certain limit and your home must be in an eligible rural area and pass the appraisal.
CHOOSING THE BEST MORTGAGE LENDER
We hope we've answered your question, “What type of home loans are there?” But if you still have questions about which exact home loan and term is best for you, the most important thing is to choose a lender you trust who can work with you to make sure you have an enjoyable home buying experience.
Click below to see how Fibre Federal Credit Union can serve your needs!
Terms up to 84 Months
Keep your monthly payments nice and low with flexible terms up to 84 months.
Frequently Asked Questions
Need technical support or have additional questions about Digital Wallets?
As much as we’d like to help you with all your concerns and questions, “technical” means different things to different smartphone users! But check out our handy list of providers who can help you get digital wallet set up on your mobile device today. By clicking on your mobile provider, you can get answers on how to use digital wallet and which devices are compatible.
If my card is blocked, can I still use my Digital Wallet to make purchases?
Fibre Federal Digital Wallet does not transfer your card number data but uses a unique “token” code for each transaction. This process is called “tokenization” and it helps safeguard your card information when you make a purchase.
This means that when you make a purchase, the digital wallet will generate a token instead of sending your credit or debit card information to the merchant. The token is used to process the payment while your personal information stays secure.
Plus, as an extra layer of protection, access to your Fibre Federal Digital Wallet is protected by a PIN or other security measure to prevent unwanted access.
Finally, by storing your cards digitally, you can worry less about them being lost or stolen.
What do I do if I lose my device?
Password protect your smartphone, and install anti-virus software on your phone, such as Avast. Phones have been the latest targeting in SMS messaging, and apps that mimic banking apps, or run while using banking apps.
If you lose your device, contact your cell phone provider immediately. As a precaution, you can contact us at 1-800-205-7872 during business hours or 1-833-462-0796 after hours to block your card.
What do I do if my debit or credit card is lost or stolen?
If your card is lost or stolen, we are here to help. If you report suspicious activity to us we will stop further use of the impacted card, replace it and issue a new card number at no cost to you. Contact our 24/7 Card Care Center at 1-833-462-0796.
Real Words, Real People from the PNW
Money was never something that we talked about growing up, so it’s something I really try to focus on with my kids. My kids each have accounts at the credit union. My daughter just turned six and feels like such a big girl when she’s able to make that transaction with a teller. If I had had those conversations with my family, I could have had more opportunities to do the things that I wanted to do.